
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Aurinia Stock Jumps After Earnings Beat And Pipeline Progress
- Aurinia Pharmaceuticals reported quarterly revenue of $83.2 million and net income of $37.4 million, with LUPKYNIS net product sales at $79.4 million and new clinical studies initiated.
- The combination of stronger LUPKYNIS demand and progress on aritinercept across four autoimmune indications points to a business increasingly defined by both commercialization and pipeline depth.
- In the following sections, we examine how Aurinia Pharmaceuticals' investment narrative is shaped by stronger LUPKYNIS sales and recent pipeline progress.
Scan Aurinia Pharmaceuticals alongside other autoimmune and biotech players gaining momentum by reviewing our curated 16 high quality undiscovered gems with similar fundamentals and under-the-radar potential.
Aurinia Pharmaceuticals Investment Narrative Recap
Aurinia Pharmaceuticals still asks you to believe in two things if you are a shareholder. First, that LUPKYNIS can remain a durable cash generator in a competitive autoimmune market. Second, that aritinercept can turn into a second pillar over time. The latest quarter, with $83.2 million in revenue and $37.4 million in net income, supports that operating thesis rather than changing it.
In the near term, the key catalyst remains continued LUPKYNIS demand and real world adoption as guidelines and prescriber habits evolve. The main risk is the company’s heavy dependence on this one product in the face of patent challenges, pricing pressure, and potential competitors. The new aritinercept spend and trial activity provide diversification potential, but they also keep R&D intensity and execution risk high.
The Phase 4 study that combines LUPKYNIS with other therapies is the announcement most tied to this quarter’s story. It directly concerns the existing commercial engine, not just the earlier stage pipeline. If the trial produces clear safety data and meaningful real world evidence, it could strengthen physician comfort and support sustained use in lupus nephritis treatment regimens.
At the same time, this kind of post approval work is a reminder of the risk side. Aurinia Pharmaceuticals is still committing meaningful resources to deepen LUPKYNIS evidence, in a setting where any safety signal or weaker than expected outcome would matter. For an investor, that trial sits at the intersection of the current cash flow stream, future reimbursement discussions, and the need to defend the product’s positioning against both guideline changes and rival therapies.
Aurinia Pharmaceuticals' analyst narrative points to forecast revenue of $453.5 million and earnings of $169.9 million by 2029. These figures are based on an assumed 13.3% yearly revenue growth rate and a projected earnings decline of $144.2 million from current earnings of $314.1 million.
Uncover why Aurinia Pharmaceuticals' fair value indicates a 7% potential upside to its current price before that discount gap closes.
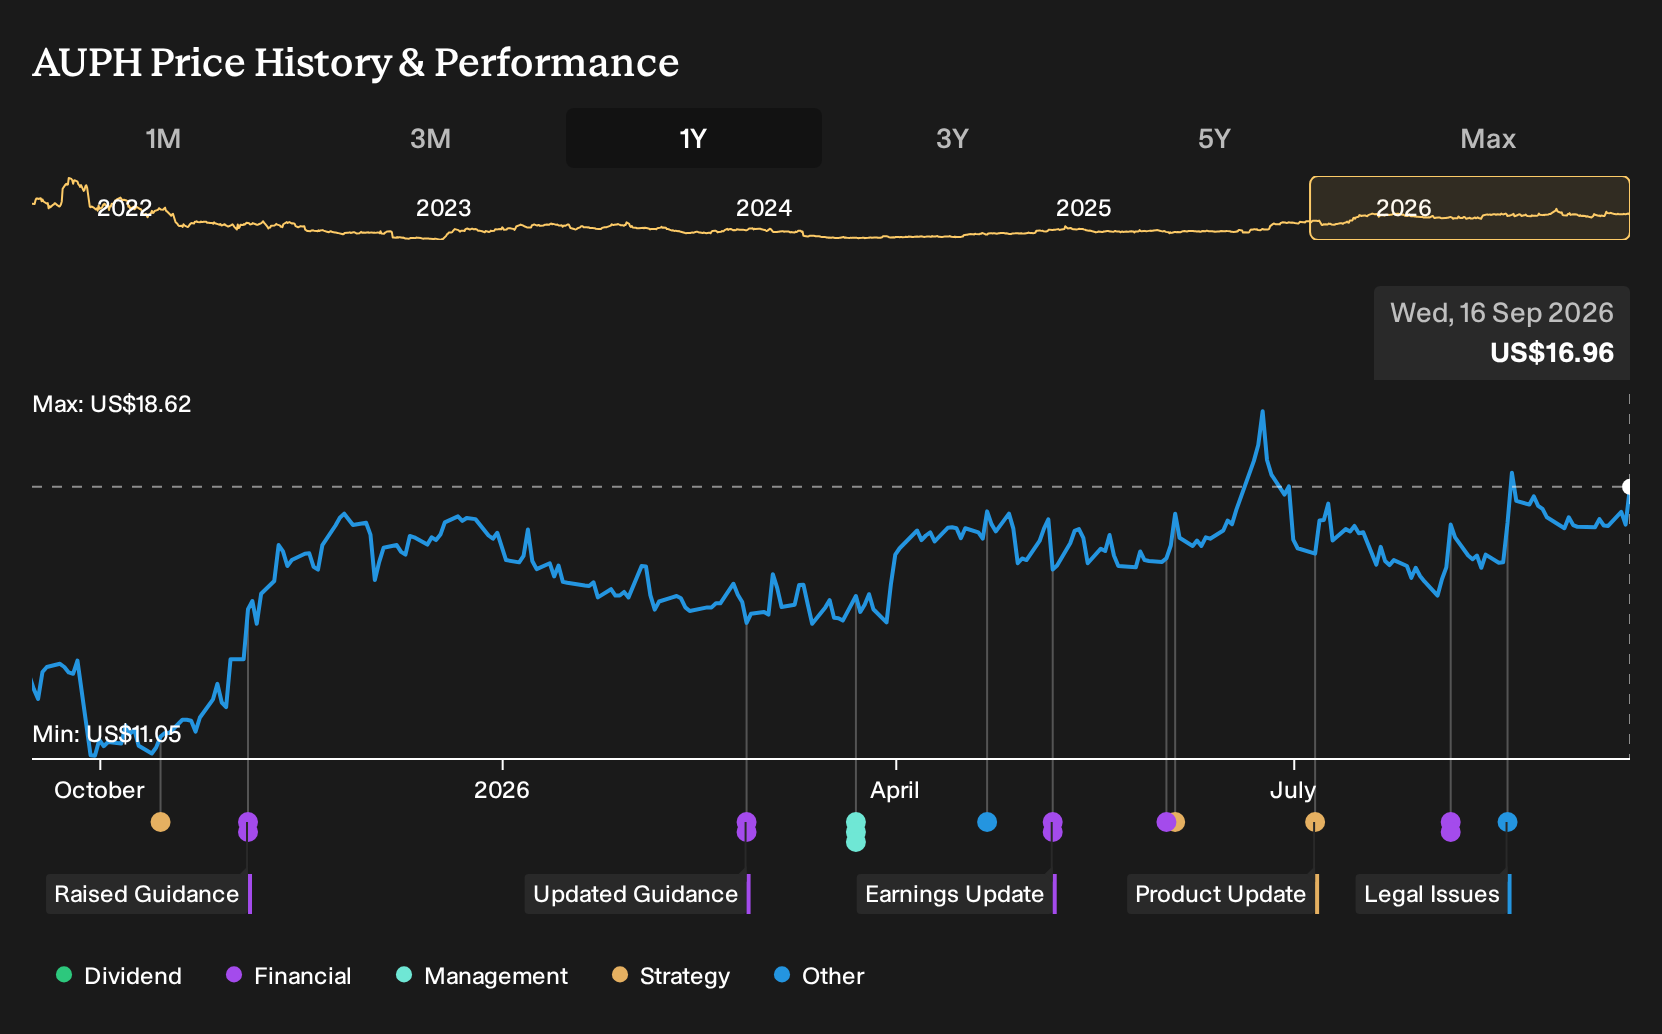
Exploring Other Perspectives
Some of the most optimistic analysts on Aurinia Pharmaceuticals focus on LUPKYNIS as a stronger catalyst than the consensus view suggests. Before this latest quarter, the bullish narrative was built around revenue reaching about $592.9 million and earnings near $290.7 million by 2029. You can treat today’s numbers as a fresh data point that might shift those expectations, then compare several viewpoints before deciding how you feel about the story.
Explore 4 other Aurinia Pharmaceuticals fair value estimates, including one that suggests as much as 149% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aurinia Pharmaceuticals research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Aurinia Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aurinia Pharmaceuticals' overall financial health at a glance.
Looking for more Aurinia Pharmaceuticals sized ideas?
If Aurinia Pharmaceuticals has sharpened your appetite for focused research, broaden the watchlist by scanning other businesses with clear stories, resilient finances, and room for the market to reassess them over time.
- For investors hunting for strong cash generators that the market may be pricing cautiously, start with a curated group of 33 high quality undervalued stocks with robust fundamentals.
- If capital preservation matters just as much as upside, filter for sturdier balance sheets through a targeted 11 resilient stocks with low risk scores that screens for resilience first.
- Income focused readers can anchor their research in companies that prioritize regular payouts by reviewing a hand picked 6 dividend fortresses that aims for steady yield with supportable cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com