
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Is Live Nation Entertainment’s Stock Performance Compared to Other Entertainment Stocks
Beverly Hills, California-based Live Nation Entertainment, Inc. (LYV) is a global live-entertainment company with a market cap of $40.6 billion. It promotes concerts, operates venues, sells tickets through Ticketmaster, and connects brands with music audiences through sponsorships and advertising.
Companies valued between $10 billion and $200 billion are generally classified as large-cap stocks, and Live Nation fits squarely within this range, highlighting its scale and influence in the global entertainment industry. Yet LYV’s appeal goes beyond its size. The company has built a vertically integrated live-entertainment powerhouse, spanning concert promotion, venue operations, and ticketing through Ticketmaster. Its global reach, deep artist relationships, extensive venue network, and massive fan base allow Live Nation to monetize audiences across multiple stages of the live-event experience.
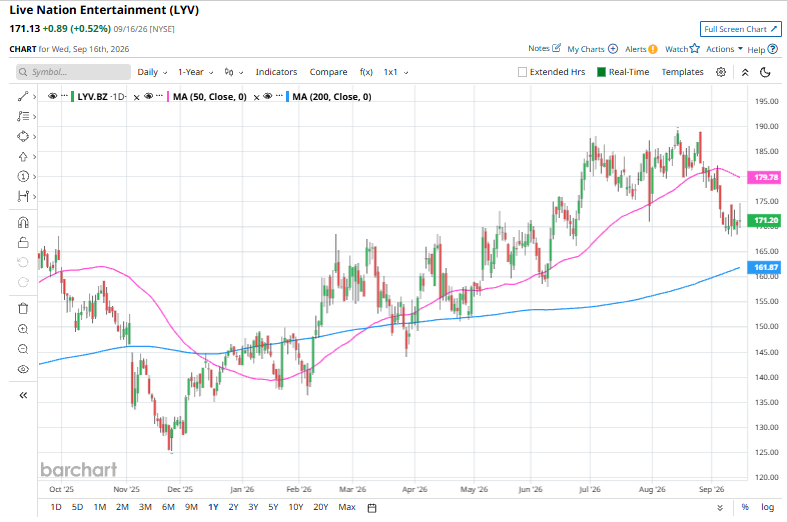
Live Nation Entertainment has fallen 9.6% from its 52-week high of $189.24 reached on Aug. 14. Still, the stock has held up relatively well in the near term, declining 1.7% over the past three months, compared to the Invesco Dynamic Leisure and Entertainment ETF (PEJ), which has dipped 5.1%.
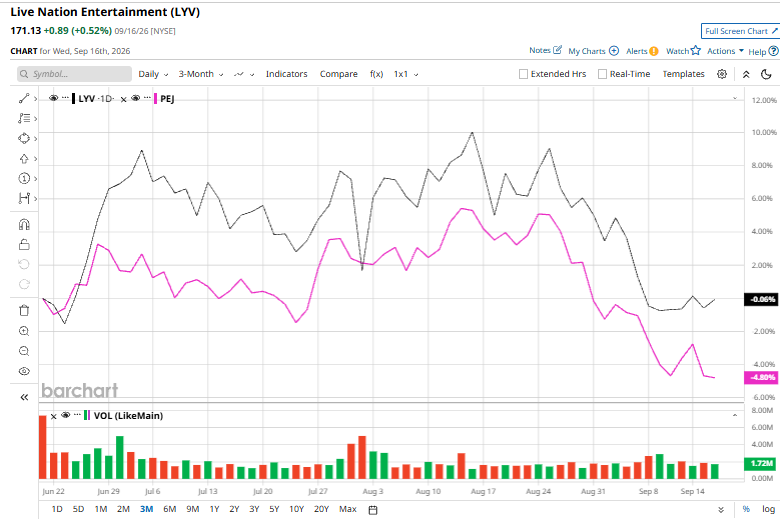
The longer-term picture is more encouraging. LYV has gained 20.1% year to date, dramatically outpacing the PEJ’s 1.6% rise. However, LYV has soared marginally over the past 52 weeks, trailing the ETF’s 1.9% return over the same time period.
Technically, the stock has stayed above its 200-day moving average since early February, signaling a broad upward trend, though it has slipped below its 50-day moving average since late August, suggesting recent weakness.
LYV’s relative underperformance over the past year appears to reflect execution and cost pressures rather than a lack of demand for live entertainment. Legal overhangs, uneven concert timing, and higher investment spending have weighed on the stock, while revenue growth of just 5.1% over the past two years has trailed the broader consumer discretionary sector. At the same time, LYV’s 3.6% operating margin provides a relatively thin cushion against unexpected costs, while rising capital requirements are expected to put further pressure on free cash flow.
On the bright side, LYV recently announced its Q2 2026 earnings, and it surpassed estimates on all fronts. Revenue rose 9% from the prior year to $7.67 billion, while earnings per share climbed 156.1% year over year to $1.05. Additionally, LYV also raised its outlook for fan growth, revenue, adjusted operating income, and margin expansion for the coming quarters.
Live Nation Entertainment has delivered a mixed performance against its entertainment peer Warner Bros. Discovery, Inc. (WBD). Over the past 52 weeks, WBD has surged 53.8%, putting LYV behind on the longer-term horizon. However, LYV has comfortably paced ahead of WBD’s 2.6% advance in 2026.
Analysts also remain positive on LYV, with a “Strong Buy” consensus among 25 analysts. Its mean price target of $205.46 represents a potential 20.1% premium to the stock’s current level.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.