
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Global Growth Companies With High Insider Ownership In September 2026
In September 2026, global markets are navigating a complex landscape marked by escalating geopolitical tensions and rising inflation concerns, driven by higher oil prices and shifting monetary policy expectations. Despite these challenges, investors continue to seek opportunities in growth companies with high insider ownership, as such stocks often demonstrate strong alignment between management and shareholder interests, potentially offering resilience amid market volatility.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Zhejiang Taotao Vehicles (SZSE:301345) | 27.9% | 30.6% |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.5% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 126% |
| Meitu (SEHK:1357) | 22.9% | 30.7% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's uncover some gems from our specialized screener.
JHT DesignLtd (SHSE:603061)
Simply Wall St Growth Rating: ★★★★★★
Overview: JHT Design Co., Ltd. focuses on the research, development, production, and sale of semiconductor chip testing equipment in China with a market cap of CN¥28.58 billion.
Operations: JHT Design Co., Ltd. generates revenue primarily from its semiconductor chip testing equipment operations in China.
Insider Ownership: 23.1%
JHT Design Ltd. reported impressive growth, with H1 2026 revenue reaching CNY 600.71 million, nearly doubling from the previous year. Net income also saw a substantial increase to CNY 171.17 million. The company's earnings are forecast to grow significantly at 48.63% annually, outpacing the Chinese market average of 27.2%. Despite this growth potential, its share price has been highly volatile recently and lacks recent insider trading activity for further insights into insider confidence levels.
- Click here and access our complete growth analysis report to understand the dynamics of JHT DesignLtd.
- According our valuation report, there's an indication that JHT DesignLtd's share price might be on the expensive side.
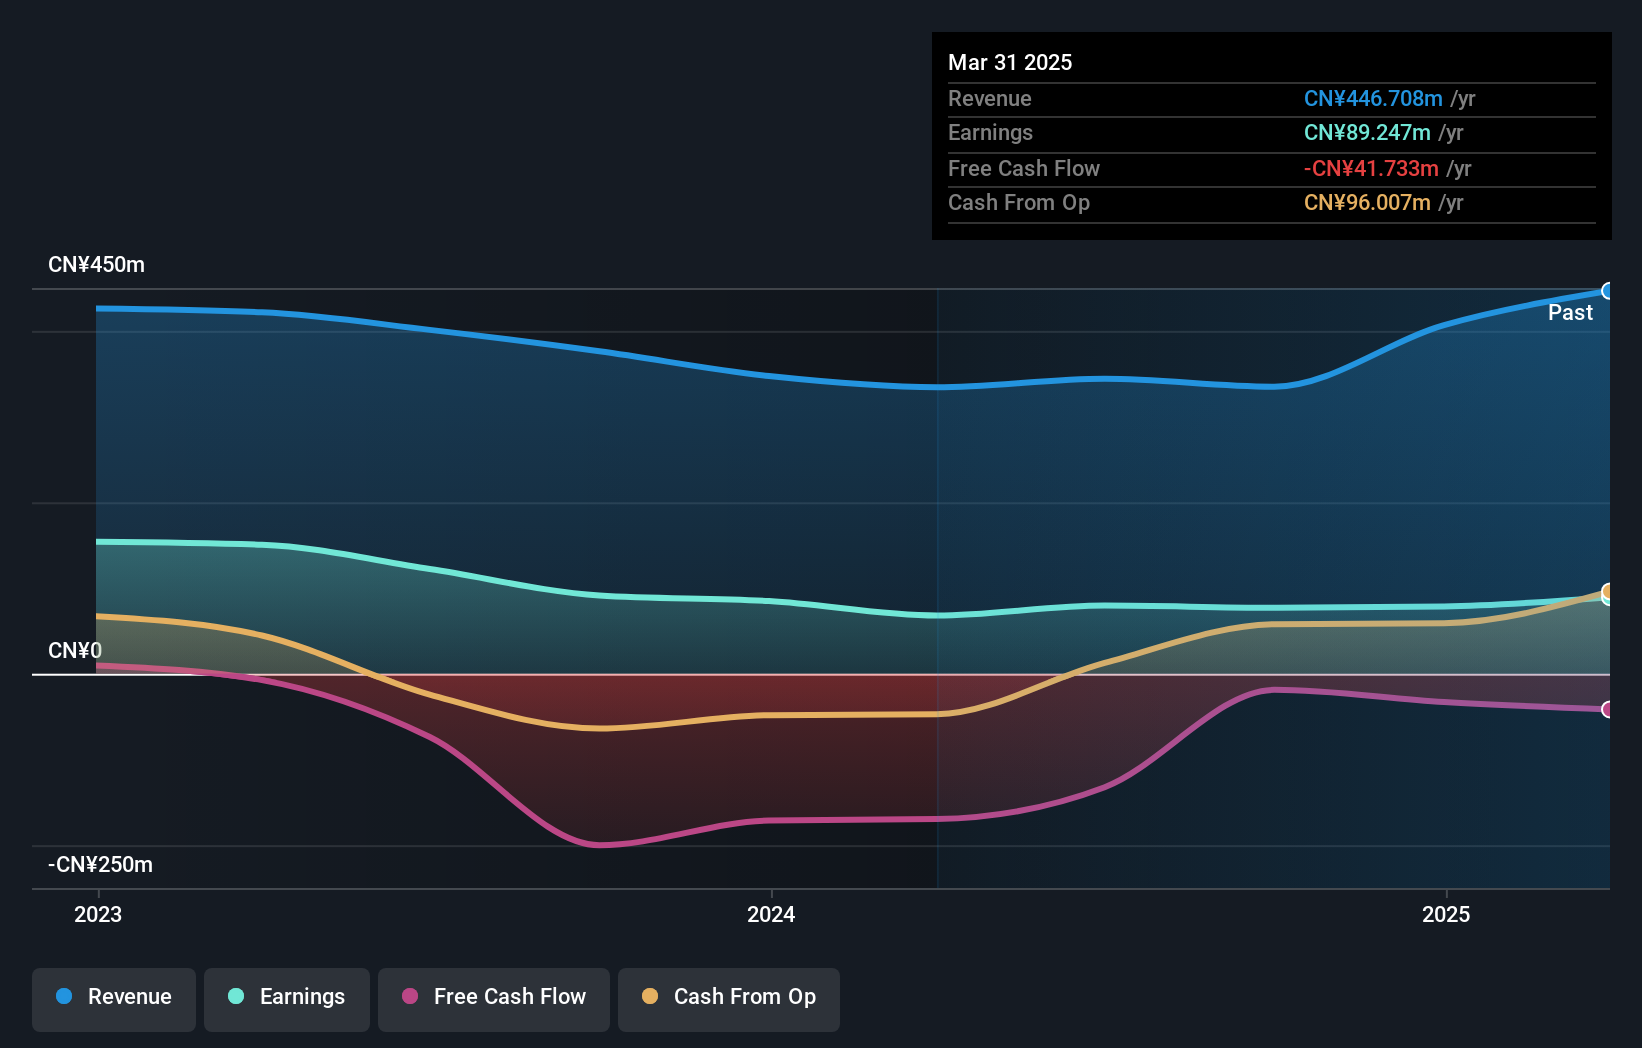
Wuxi NCE PowerLtd (SHSE:605111)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Wuxi NCE Power Co., Ltd. operates in the research, design, development, and sale of semiconductor chips and power devices both in China and internationally, with a market cap of approximately CN¥23.51 billion.
Operations: The company's revenue primarily comes from its electronic components segment, totaling CN¥2.11 billion.
Insider Ownership: 23.7%
Wuxi NCE Power Ltd. demonstrates strong growth potential, with earnings expected to increase 31% annually, outpacing the Chinese market average of 27.2%. Revenue is forecasted to grow at 21.5% per year, surpassing the market's 17.3%. Despite these prospects, recent earnings show stable net income with sales rising to CNY 1.16 billion in H1 2026 from CNY 926 million a year ago. The share price has been highly volatile recently without significant insider trading activity for additional insights.
- Take a closer look at Wuxi NCE PowerLtd's potential here in our earnings growth report.
- In light of our recent valuation report, it seems possible that Wuxi NCE PowerLtd is trading beyond its estimated value.

Suzhou Novosense Microelectronics (SHSE:688052)
Simply Wall St Growth Rating: ★★★★★☆
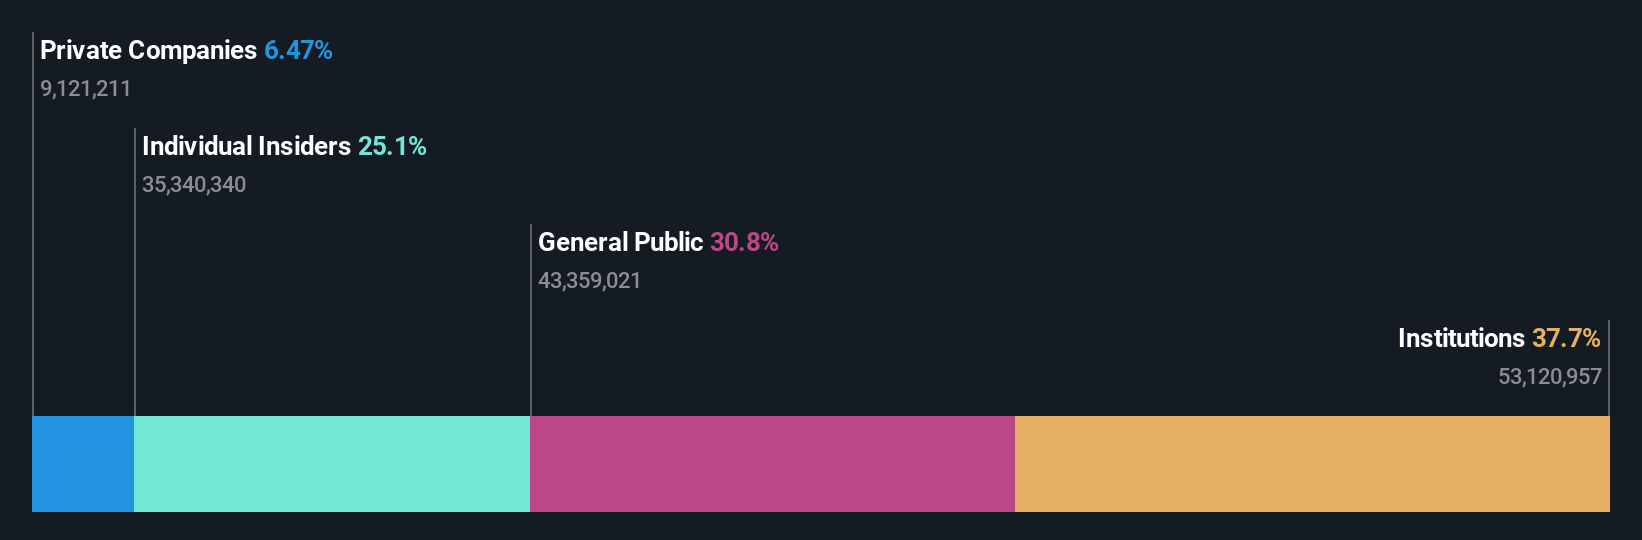
Overview: Suzhou Novosense Microelectronics Co., Ltd. operates in the semiconductor industry, focusing on designing and manufacturing microelectronic products, with a market cap of approximately CN¥36.12 billion.
Operations: Suzhou Novosense Microelectronics Co., Ltd. generates its revenue primarily from the design and manufacture of microelectronic products within the semiconductor industry.
Insider Ownership: 21.8%
Suzhou Novosense Microelectronics is experiencing robust growth, with earnings expected to rise 67.91% annually and revenue forecasted to grow at 21.6% per year, surpassing the Chinese market's average. Recent reports show a significant turnaround from a net loss to CNY 67.59 million profit in H1 2026, driven by increased demand in automotive electronics and AI infrastructure sectors. Despite high volatility in its share price, insider trading activity remains minimal over the past three months.
- Dive into the specifics of Suzhou Novosense Microelectronics here with our thorough growth forecast report.
- Our expertly prepared valuation report Suzhou Novosense Microelectronics implies its share price may be too high.
Key Takeaways
- Gain an insight into the universe of 727 Fast Growing Global Companies With High Insider Ownership by clicking here.
- Ready To Venture Into Other Investment Styles? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com