
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
BAE Systems Stock And 2 Defense Picks Backed By Rising Military Spending
Russia’s election, war costs and oil price shocks are colliding to reshape how money flows into defense and military equipment stocks. That mix creates both potential openings and traps, as governments rethink budgets while energy markets stay jumpy. This article walks through three stocks from our Global Defense and Military Equipment Contractors list that are positioned to benefit from the latest headlines, and explains what that could mean for your portfolio decisions.
The stocks covered below are just a sample. The full screen surfaced 50 more defense and military contractors with equally compelling stories that are not included here. To go further, head straight into the Global Defense and Military Equipment Contractors screener to identify, filter and analyze the highest conviction ideas for your watchlist.
Cohort (AIM:CHRT)
Cohort is firmly rooted in the defense technology theme of this screener, supplying mission systems, communications and sensing equipment to military and security customers across allied regions where governments are reassessing threat levels and committing more resources to long term capability programs.
Cohort generates about £159 million from Communications and Intelligence and £147 million from Sensors and Effectors, with central eliminations close to zero, on a market value of roughly £542 million.
There is order conversion risk across a long dated book of over £600m and a large pipeline of prospects. If customers defer or cancel programmes such as Italian Navy submarines, Atlantic Bastion or naval communications upgrades, revenue could be pushed out beyond current analyst timelines and increase earnings volatility.
What happens to Cohort’s earnings path if one key pressure point quietly keeps stretching those defense programme timelines?
If that pressure point is on your radar, the full narrative for Cohort explains how Cohort could turn stretched programmes into accelerating cash generation and contract resilience.

BAE Systems (LSE:BA.)
BAE Systems is one of the pure-play defense contractors that anchors this screener theme, with aircraft, warships, munitions and electronics sold into allied government programs that respond directly to rising geopolitical risk and pressure for higher NATO and partner defense budgets.
BAE Systems develops military air, maritime and land platforms along with electronic systems, munitions and cyber services, with Electronic Systems and Air each generating about £7.8b and £7.7b of revenue, Maritime £6.7b, Platforms & Services £5.3b, Cyber & Intelligence £2.4b and a market value near £57.5b.
The company's order backlog has surged to £75 billion, with a pipeline of new opportunities partly fueled by higher defense spending commitments across NATO, the US, UK, Europe, and Indo-Pacific. This provides visibility on future revenues and supports the topline outlook over multiple years.
The real swing factor is how one capacity bottleneck shapes the pace at which those booked contracts actually flow through into margins and cash.
That capacity question is exactly what the full narrative for BAE Systems unpacks, showing where BAE Systems’ backlog could accelerate cash, where it may stall, and what that means for you.

Kratos Defense & Security Solutions (KTOS)
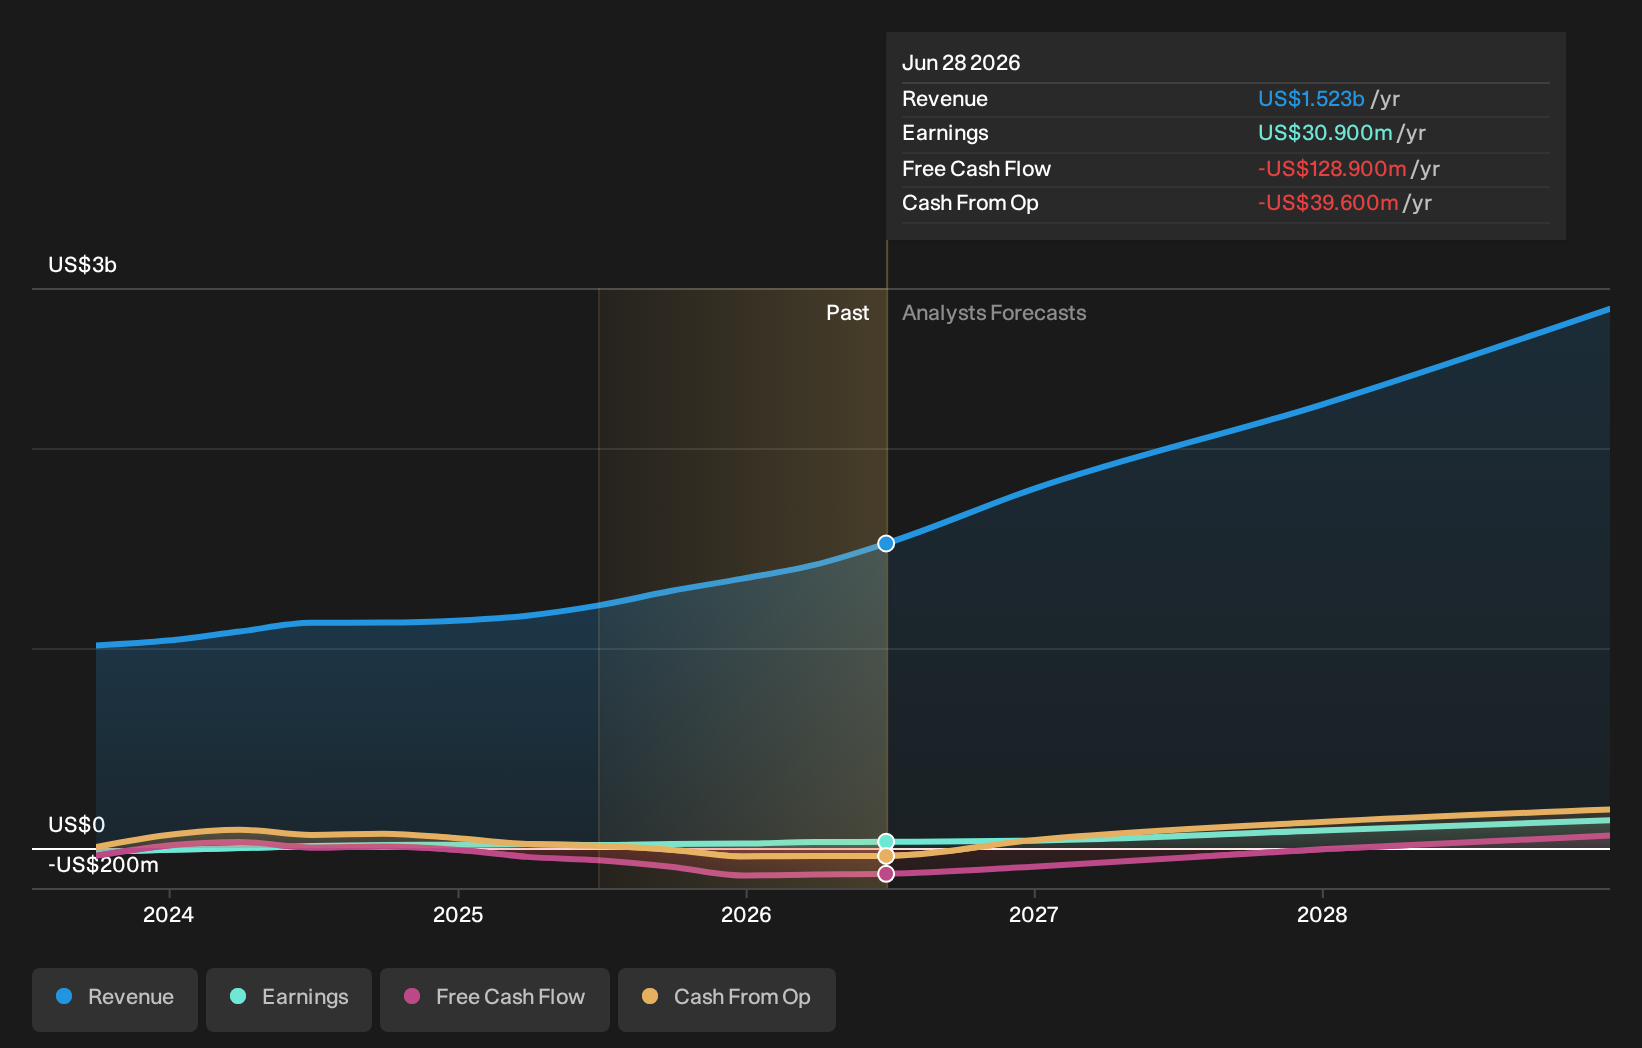
Kratos Defense & Security Solutions plugs directly into the defense modernization theme of this screen, supplying unmanned systems, hypersonics and space technology that tie closely to U.S. and allied procurement priorities. Unmanned Systems contributes about US$317 million and Kratos Government Solutions roughly US$1.2b of revenue, with the group valued near US$8.9b.
For investors focused on how rising geopolitical risk feeds through to actual hardware orders and software-heavy defense projects, Kratos Defense & Security Solutions offers a concentrated way to track that story without straying outside the screen’s core brief.
Kratos is exposed to a historic surge in global defense spending and modernization initiatives by the U.S., NATO and Pacific allies, as ongoing geopolitical tensions coincide with a multi-year expansion in defense budgets. The business model requires ongoing elevated R&D and capital expenditures to maintain technology capabilities in areas like hypersonics and unmanned systems, but successful commercialization is not guaranteed; as such, there is risk of diluted returns on invested capital and net margin compression if anticipated program ramps or sole-source positions do not scale as expected.
The real question is what happens to Kratos Defense & Security Solutions’ future cash generation if a single assumption on program scaling or funding timing starts to bend.
If that funding or scaling curve is what you care about, the full narrative for Kratos Defense & Security Solutions shows where Kratos Defense & Security Solutions could see accelerating upside versus perceived risk.
Seeking Alternatives Before The Crowd?
Fresh ideas can move fast when momentum builds and prices start flying. Use this window while it matters, before they stop looking under the radar for now, act now.
- Spot potential breakouts early by scanning the 9 high quality undervalued stocks, which couples cash generation with balance sheet strength before everyone else is caught chasing the move.
- Ride long term income themes by reviewing the 1 dividend fortresses, curated for sturdy payouts that could help you stay in the market when others drop out.
- Track the next wave of automation by checking the 38 robotics and automation stocks, focused on businesses building real-world robotics momentum while the crowd still treats them as niche.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com