
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Vistra Stock As AI Power Deals Expand
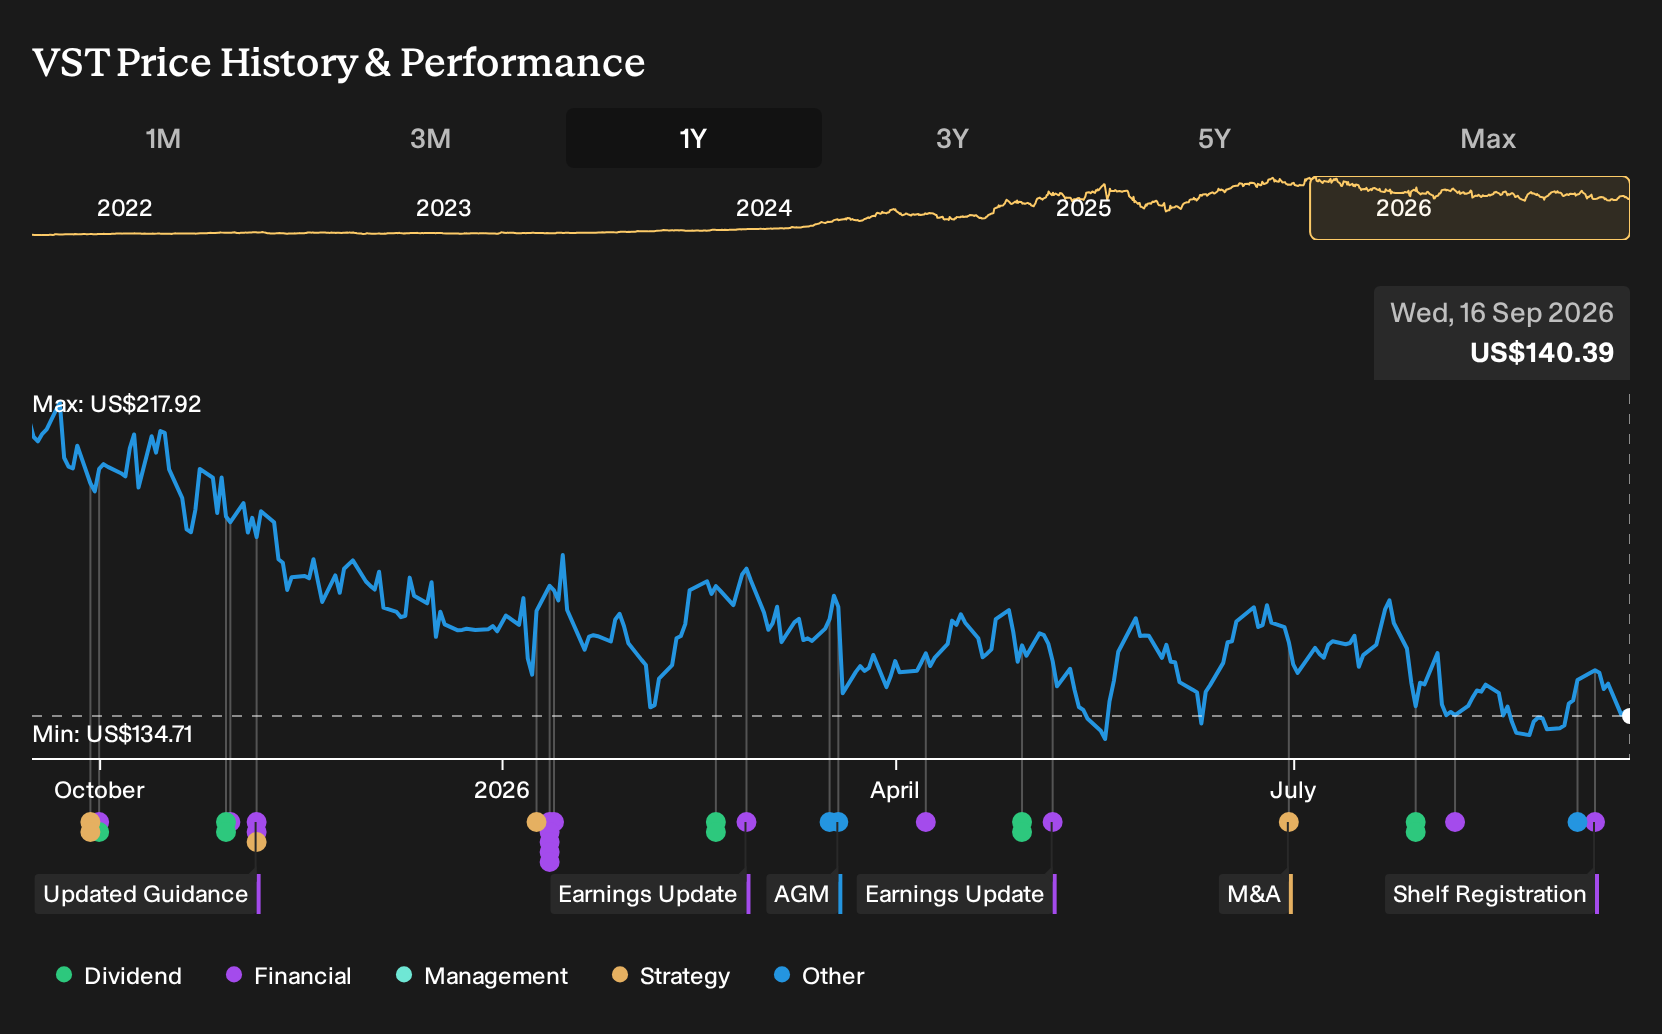
- Vistra filed an omnibus shelf registration in early September for common and preferred stock and recently moved to intervene in a Federal Energy Regulatory Commission proceeding, citing its roughly 44,000 MW generation fleet and about 15,000 MW in the PJM market.
- Vistra is increasingly tied to the AI data center buildout through long term nuclear power agreements with major customers such as Amazon Web Services and Meta, which links its generation portfolio directly to rising electricity needs from digital infrastructure.
- The focus is now on how Vistra's investment narrative is shaped by its AI driven nuclear contracts and its recent regulatory and financing moves.
What Is Vistra's Investment Narrative?
To own Vistra, you have to believe the AI driven buildout of data centers will keep demanding large, reliable blocks of power and that this utility style operator can keep executing on complex projects without letting capital needs run away from it. The long term nuclear contracts with Amazon Web Services and Meta give some visibility on demand and pricing. The new omnibus shelf registration simply adds financial flexibility. It does not by itself change the operating story unless it is used aggressively for equity issuance.
In the short term, the key questions are about execution and balance sheet discipline. Vistra carries meaningful debt and relies fully on higher risk funding sources, while earnings forecasts sit in the mid teens and revenue expectations around 6.6% a year lag the wider US market. Recent share performance has cooled, and the Zacks Rank cut plus insider selling indicate that not everyone is leaning in at this price. The FERC intervention ties into the real operational arena where capacity, market design, and pricing get decided, which is where Vistra will either justify its P/E premium to peers or struggle to do so.
Even so, before treating Vistra as a straightforward AI power play, there is a structural issue in the story that sits uncomfortably close to ...
There's only one way to know the right time to buy, sell or hold Vistra. Head to Simply Wall St's company report for the latest analysis of Vistra's Fair Value.
Exploring Other Perspectives
One alternate view on Vistra focuses on margin pressure instead of AI upside. The most cautious analysts were assuming revenue stays roughly flat near US$19.5b by 2029, with earnings around US$3.9b and a P/E of 13.7x. That is a far more conservative setup. Use that gap in expectations to stress test your own view on this shelf filing and FERC move.
Explore 9 other Vistra fair value estimates, including one that suggests it could be worth just $170.91!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vistra research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vistra. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vistra's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vistra?
Once you have a handle on Vistra, it can help to compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If resilience matters most to you, start with a group of companies that screen well on balance sheet strength and fundamentals using the list of solid balance sheet and fundamentals (22 results).
- If income is your priority, consider businesses that combine higher yields with stability by reviewing the 6 dividend fortresses.
- If you want something a bit less crowded, check out a curated pool of lesser known quality stocks via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com