
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kyocera (TSE:6971) Following Silicon Photonics Progress, Is The AI Data Center Story Fully Valued?
Kyocera (TSE:6971) is back on radar after working with Tohoku University to integrate optical isolators onto silicon photonics chips using localized laser annealing, a process aimed at cleaner and faster AI data center communications.
Recent trading has been choppy for Kyocera, with the share price slipping 6.29% over the past month and 3.26% over ninety days. The stock has still posted a strong year-to-date share price return of 59.53% and a 1-year total shareholder return of 76.58%. This suggests investors have already assigned meaningful value to developments like the silicon photonics work with Tohoku University while also reassessing shorter term expectations.
Capture the AI data center theme by scanning a hand picked set of 60 AI infrastructure stocks that, like Kyocera, are tied to the hardware behind faster, higher bandwidth communications.Kyocera’s sharp run over the past year now contrasts with a softer three-month stretch and a price slightly above analyst targets. Has most of the AI data center upside already been realized, or does the current valuation still leave room?
Price-to-Earnings of 28.1x: Is it justified?
Kyocera now trades on a P/E of 28.1x, with the last close at ¥3,560, after a strong run that has already pushed the share price above analyst targets and well ahead of the broader Japanese market over the past year.
The P/E ratio compares the current share price to earnings per share. For a diversified electronics group like Kyocera, it reflects what buyers are willing to pay today for each unit of current earnings, based on expectations for future profit trends, capital allocation, and the durability of its positions in areas such as semiconductor components, electronic devices, and document solutions.
Against its own history, recent earnings momentum has been sharp. Earnings growth over the past year is described as very large compared to its 5 year record of declining profits, and net profit margins have improved from 1.2% to 7.8%. That improvement helps explain why the market is prepared to pay more for each yen of profit. Even so, analysts expect revenue to grow 3.4% per year and earnings to increase 6.83% per year, which is slower than both the wider JP market and the JP Electronic industry. This suggests the current premium P/E already incorporates a fair amount of optimism about the AI data center opportunity and the quality of recent results.
The comparison with peers is stark. Kyocera trades below the peer group average P/E of 53.2x, which points to better value against that subset of companies, but it is expensive versus the broader JP Electronic industry on 16x. In addition, the estimated fair P/E for Kyocera is 19.5x, well below the current 28.1x. This strongly indicates that if the market eventually aligns with that fair ratio, the valuation multiple could compress from here.
Explore the SWS fair ratio for Kyocera.
Result: Price-to-Earnings of 28.1x (OVERVALUED)
Still, the AI data center story around Kyocera could be dented if silicon photonics uptake is slower than expected or if peers outspend it on similar hardware.
Find out about the key risks to this Kyocera narrative.
Another View on Kyocera’s Value
The market is already pricing Kyocera above the estimate from the SWS DCF model, which puts future cash flow value at ¥2,755.59 per share versus the current ¥3,560. That gap points to a stock that screens as overvalued on this measure. Is the AI data center story strong enough to keep investors comfortable with that premium?
Look into how the SWS DCF model arrives at its fair value.
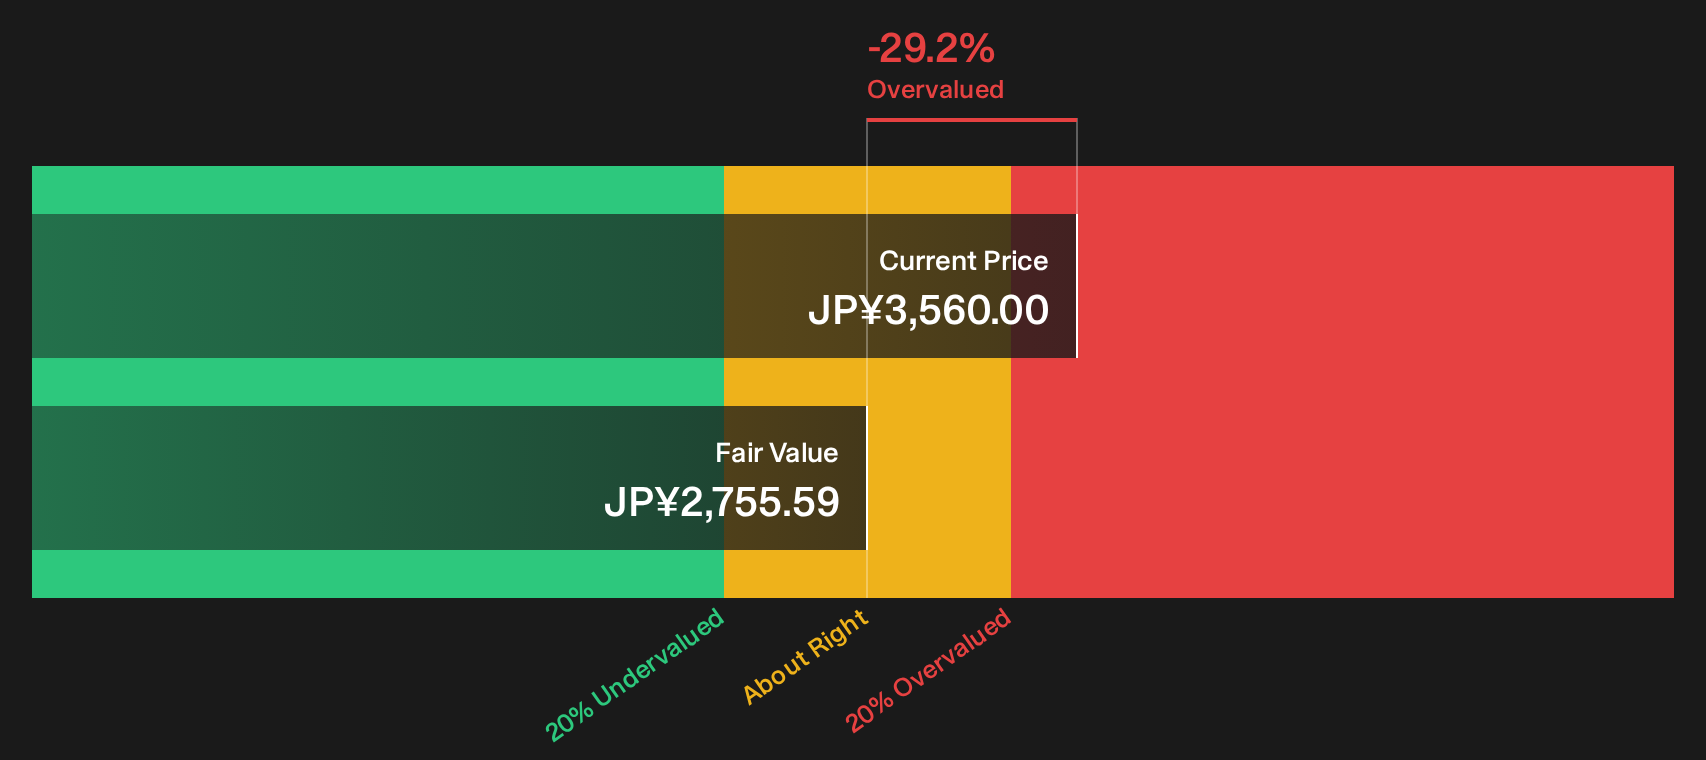
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kyocera for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Kyocera is mixed enough that it pays to look under the hood yourself and move quickly while the data is fresh. To see what the optimism is about, review the 2 key rewards
Looking for more Kyocera-like investment ideas?
If Kyocera has your attention, do not stop here. Broaden your watchlist with fresh ideas built from the same disciplined data that powers this analysis.
- Target potential mispricing by scanning companies that combine resilient cash flows with reasonable valuations through the 17 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated group of high-yield payers in the 15 dividend fortresses.
- Prioritise resilience by checking the 12 resilient stocks with low risk scores that score well on financial health and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com