
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Yum China Stock After Earnings Upgrades
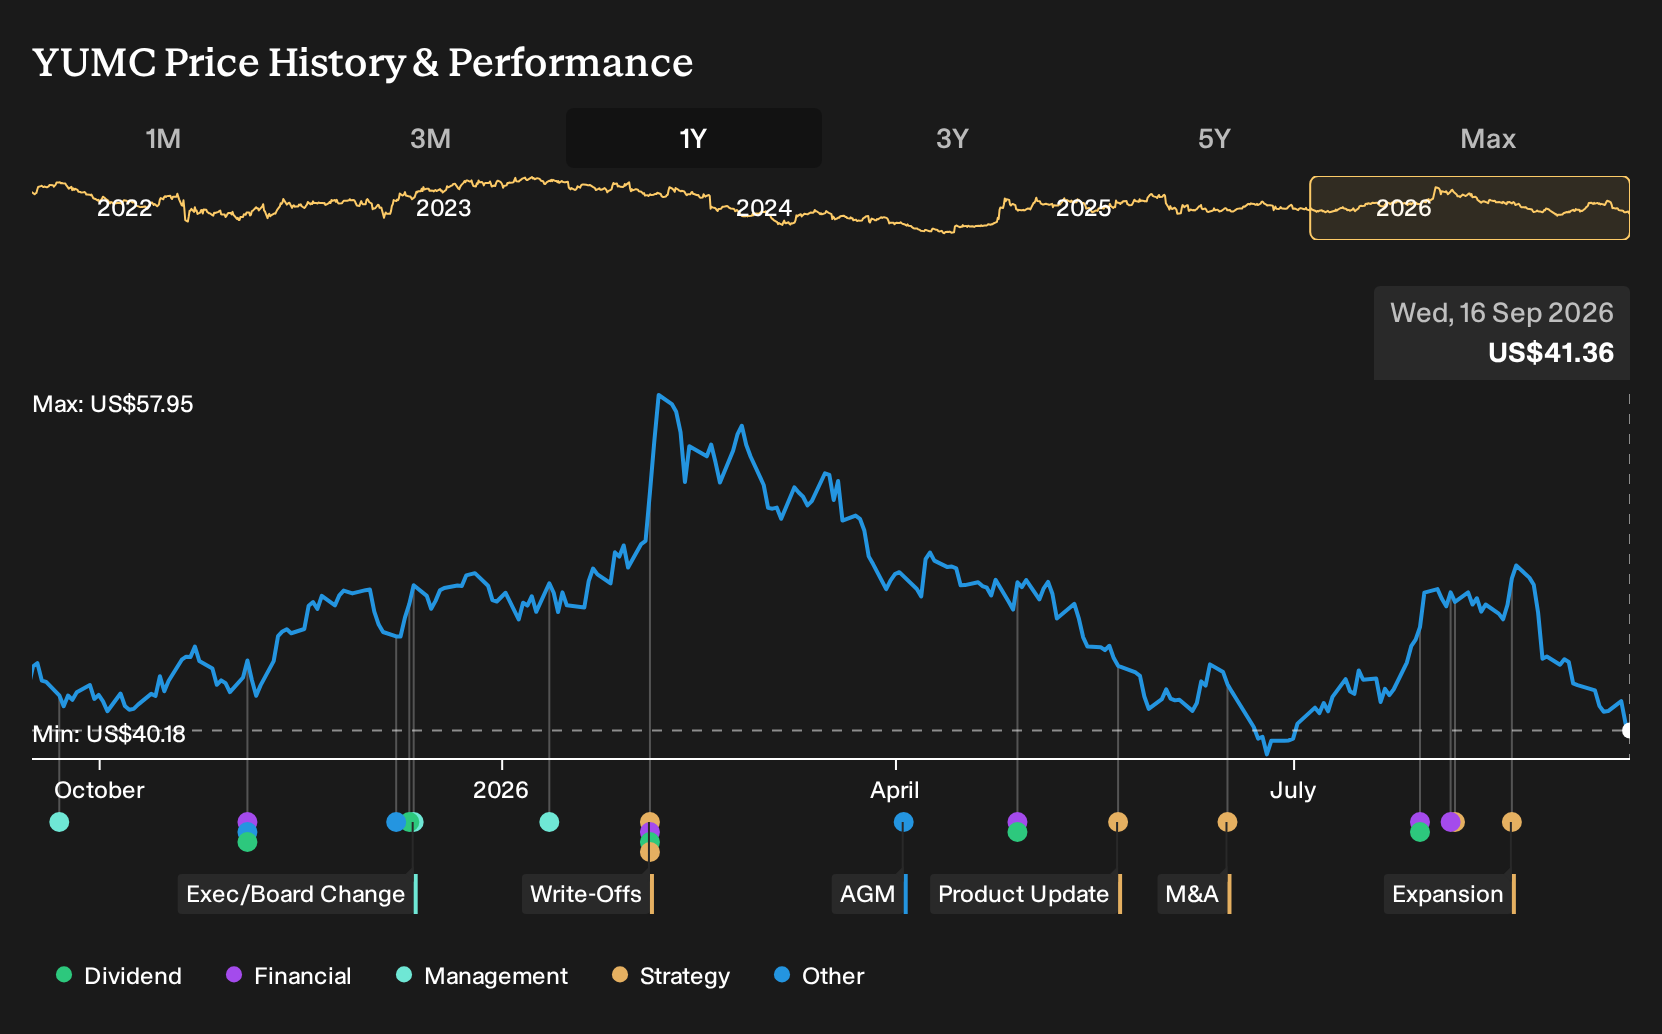
- Yum China Holdings recently faced heavy selling that pushed the stock into oversold territory, even as analysts lifted earnings estimates based on the company’s operating footprint and brand portfolio in China.
- The combination of oversold trading conditions and improving earnings expectations suggests that investors may be reassessing Yum China’s ability to manage costs, demand patterns, and its expansion program across the Chinese restaurant market.
- Investor attention now turns to how Yum China’s refreshed earnings outlook, following analyst upgrades, could influence the broader investment narrative for the business.
Compare Yum China Holdings' oversold setup and refreshed earnings outlook with a curated group of quality opportunities using the 33 high quality undervalued stocks screener.
Yum China Holdings Investment Narrative Recap
To own Yum China Holdings, you need to be comfortable with a story focused on disciplined restaurant expansion in China, growing digital ordering, and tight cost control as delivery and labor weigh on margins. In the short term, the main catalyst is execution on new store formats and growth in lower tier cities. The recent selloff and oversold setup do not change that operational to do list.
The biggest near term risk still lies in competition and discounting on delivery platforms, especially because delivery already represents a large share of sales and rider costs are rising. A mix shift toward smaller ticket items and lower tier markets can strain average checks. That risk is unchanged by the latest earnings upgrades.
With no fresh company announcements tied directly to this move, the most relevant context is how Yum China Holdings has been leaning into its digital ecosystem and new formats such as KCOFFEE and Pizza Hut WOW. These projects matter because they touch both sides of the P&L. They influence traffic and pricing, and they also affect store level efficiency.
For you as an investor, a key question is whether management can keep payback periods on new restaurants “healthy” while delivery costs, labor and commodities remain sensitive. If execution on digital ordering, supply chain improvements and automation holds together, it supports the upgraded earnings outlook analysts are working with. If it slips, the oversold setup alone does not offer much protection.
Yum China Holdings' current analyst narrative points to revenues of US$14.7b and earnings of US$1.3b by 2029, based on a 6.6% yearly revenue growth rate and an earnings increase of about US$354m from current earnings of US$946.0m.
Uncover why Yum China Holdings' fair value indicates a 48% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between about US$51 and US$69 per share, so private investors are already split on where Yum China Holdings should trade. You now have competing views to weigh against risks around delivery costs and competition, as well as potential catalysts from expansion and digital execution.
Explore 3 other Yum China Holdings fair value estimates, including one that suggests there could be as much as 67% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Yum China Holdings research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Yum China Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yum China Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Yum China Holdings?
If Yum China Holdings has sharpened your thinking about quality, risk and upside, it can be useful to benchmark it against other opportunities that share similar strengths or solve different problems in your portfolio. The Simply Wall St Screener helps you do that quickly by filtering stocks using fundamentals, not headlines.
- If you care most about stability, check out a 11 resilient stocks with low risk scores that may help you focus on businesses with more resilient profiles.
- For investors hunting for mispriced quality, scan through a 16 high quality undiscovered gems that could surface lesser known companies with solid numbers.
- When balance sheet strength is the priority, start with a list of solid balance sheet and fundamentals (22 results) that filters for firms with sturdier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com