
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Chemed (CHE)'s California Franchise Acquisition Means For Shareholders
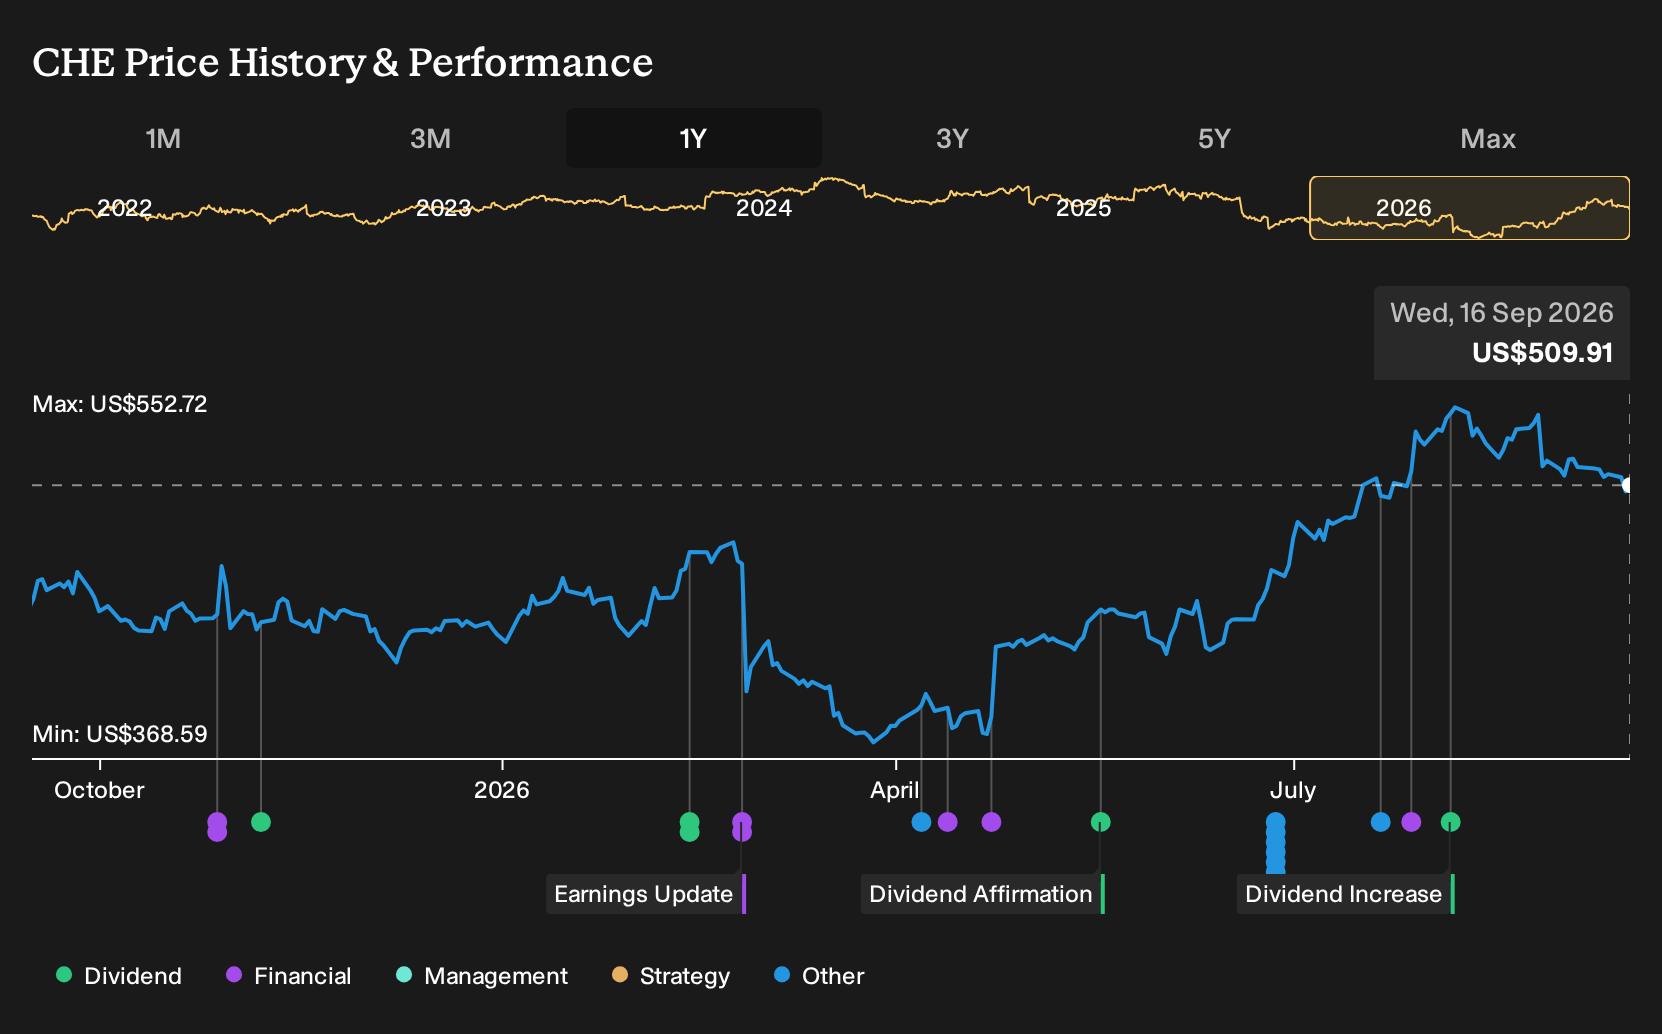
- Chemed, through its wholly owned unit Roto-Rooter Services Company, acquired the largest independent Roto-Rooter franchise serving about 11 million people across key California territories including Northern San Diego, Palm Springs, and Sacramento.
- The deal meaningfully widens Roto-Rooter’s direct control over branded operations, which is important for Chemed’s cost discipline, pricing decisions, and future acquisition playbook in plumbing and drain cleaning.
- This development invites a closer look at how Chemed's investment narrative is influenced by Roto-Rooter’s expanded California footprint and the associated operational integration work.
Scan how Chemed’s Roto-Rooter move compares with other service operators pushing for scale and pricing power by running the 16 high quality undiscovered gems before the next round of deals hits the tape.
Chemed Investment Narrative Recap
To own Chemed, you need to be comfortable with a two-engine model. VITAS is tied closely to Medicare and hospice policy, while Roto-Rooter leans on consumer and commercial plumbing demand. The California franchise purchase strengthens the service arm’s reach, but it does not change the key short term swing factors, which remain hospice reimbursement trends and execution on Medicare cap management.
The biggest operational risk still sits with reimbursement pressure and mix shifts at VITAS, coupled with cost control and demand variability at Roto-Rooter. The recent franchise acquisition can help scale and efficiency over time, but it also adds integration work, which could weigh on margins if labor, insurance, or local competition pressures persist.
The upcoming Chemed presentation at the Jefferies Healthcare Services and Technology Conference on 15 September 2026 is the most relevant near term event. It gives management a platform to update investors on how the California Roto-Rooter acquisition fits with broader cost and pricing discipline, and how cash from that segment supports hospice investment.
For catalysts, focus on whether leadership gives clearer timelines around VITAS cap exposure, Florida Certificate of Need ramp, and any early read on integration of the new territories. Investors can also listen for detail on labor efficiency, insurance costs, and customer acquisition at Roto-Rooter, since those factors directly touch both the upside story and the main operational risks.
Chemed's current analyst narrative points to forecast revenue of US$3.2b and projected earnings of US$401.9m by 2029. That outlook implies annual revenue growth of 6.8% and an earnings increase of about US$126.9m from current earnings of US$275.0m.
Uncover how Chemed's fair value points to an 8% potential upside to its current price that could narrow quickly as expectations catch up.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Roto-Rooter’s margin potential instead of hospice reimbursement risk. Before this California deal, the bullish camp was already modeling about US$3.2b of revenue and US$425.1m of earnings by 2029. As a result, you should expect those forecasts to be revisited as opinions shift and new information lands at the Jefferies conference.
Explore 2 other Chemed fair value estimates, including one that suggests as much as 36% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Chemed research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Chemed. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chemed's overall financial health at a glance.
Looking For More Investment Ideas Beyond Chemed?
If Chemed is just one candidate on your watchlist, use the Simply Wall St Screener to scan for other businesses that fit the kind of risk and return profile you prefer, without having to build a model from scratch.
- If capital preservation is near the top of your checklist, start with a set of 11 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- If you care most about quality at a reasonable price, broaden your search with a curated pool of 33 high quality undervalued stocks that combine fundamentals with attractive valuations.
- If steady income matters to you, line up potential payers using our group of 6 dividend fortresses that offer higher yield with a focus on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com