
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Government Lending Push Will Impact United Bankshares Stock
- United Bankshares recently hired Phil Poliquin as senior vice president and managing director of Government Contracting to build a dedicated GovCon lending team focused on government contracting and defense clients.
- The new leadership role signals that United Bankshares is committing resources to a specialized, potentially higher complexity client base, which can influence credit mix, underwriting focus, and long term earnings profile.
- We will now look at how United Bankshares' investment narrative could be affected by the new dedicated government contracting leadership hire.
Scan how United Bankshares' move into government contracting compares with other income focused financials by reviewing our curated list of 6 dividend fortresses.
What Is United Bankshares' Investment Narrative?
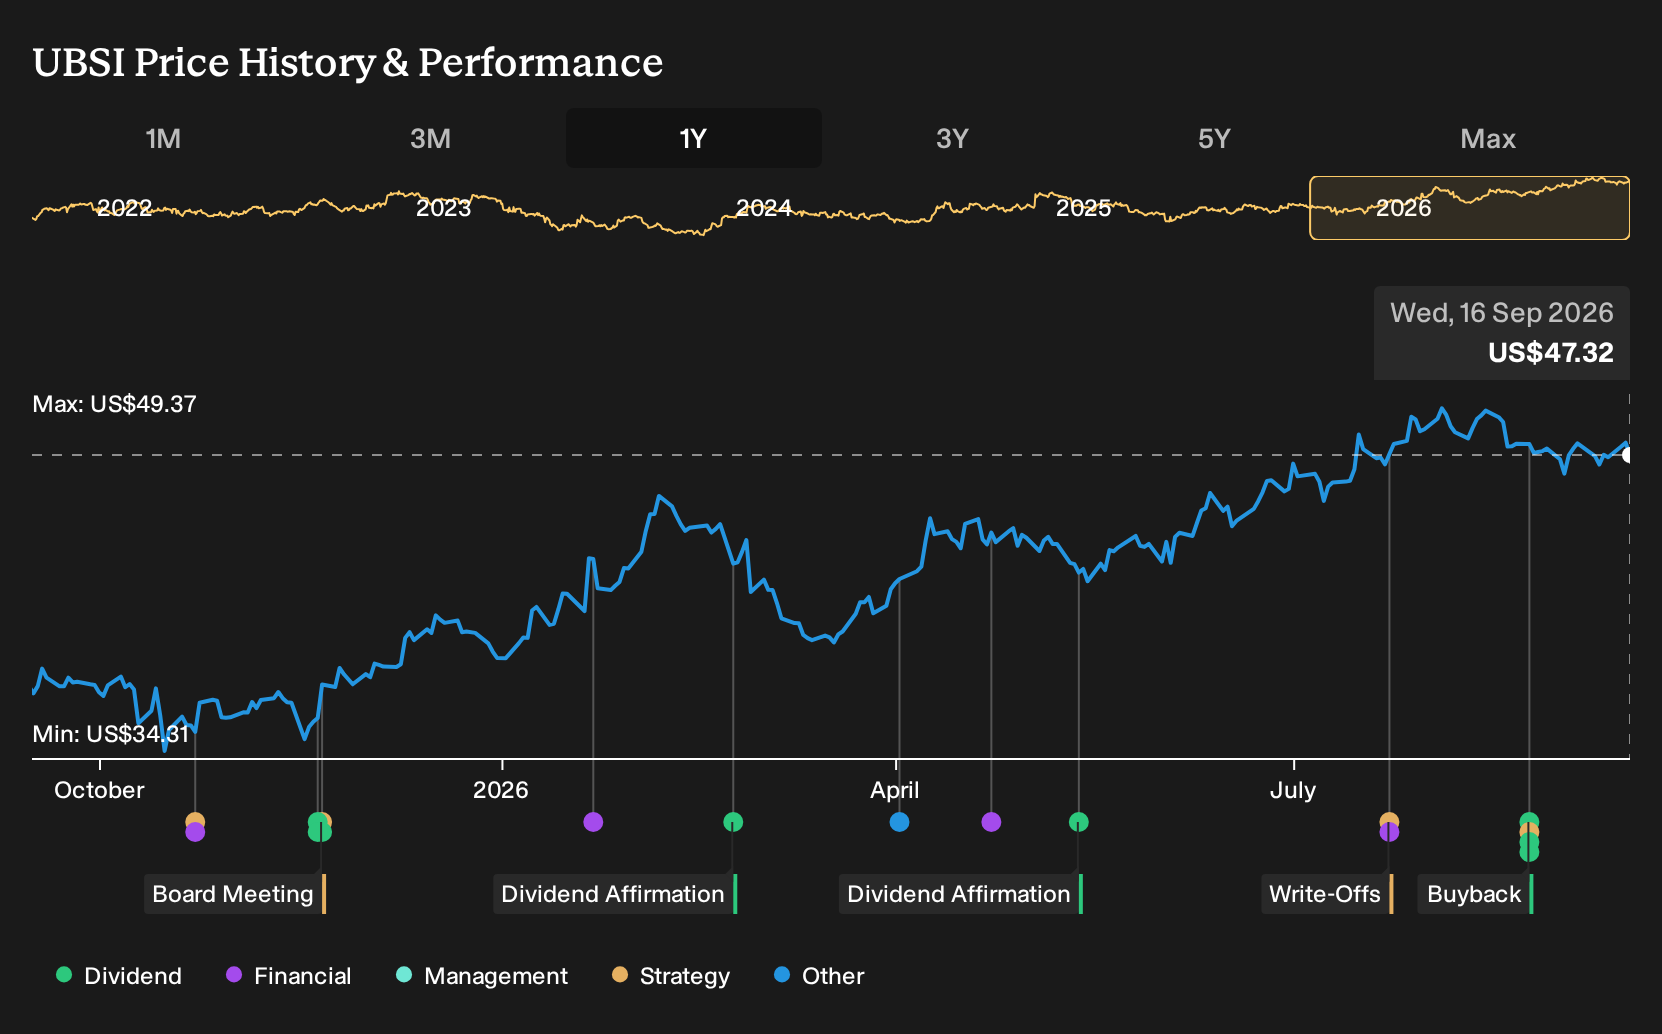
The core story with United Bankshares is pretty simple. You either believe this is a steady regional bank that can keep compounding through disciplined lending, conservative capital use, and a reliable dividend, or you do not. Earnings grew 30.6% over the past year and net profit margins are at 41.1%, supported by community banking revenue of roughly US$1.3b. The dividend yield sits around 3.2% with a payout ratio near 41%, which leaves room for reinvestment. The new government contracting hire fits that narrative as a targeted way to deepen a specific, higher complexity niche rather than a wholesale pivot.
In the short term, the main swing factors still look like loan growth, credit quality, deposit costs and what that does to returns on equity that are currently 9.3%. The GovCon build out could gradually change the loan mix and fee streams, but it is unlikely to overhaul near term earnings on its own. UBSI trades on a 12.5x P/E, a touch above an 11.2x fair P/E estimate but below a 14.1x peer average. The key question is whether the business can keep justifying that with modest forecast profit and revenue growth. The dividend appeal is clear for income focused investors, yet the real test will be how management balances that with funding any future expansion in more specialized areas like government lending.
That said, the comfort of a 3% yield and a solid year of earnings growth looks different once you weigh the fact that ...
There's only one way to know the right time to buy, sell or hold United Bankshares. Head to Simply Wall St's company report for the latest analysis of United Bankshares's Fair Value.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between US$50.33 and US$65.84 per share, which already shows how far opinions on United Bankshares can stretch. Those estimates were set before the new GovCon hire, so treat them as a pre catalyst snapshot and explore several contrasting community viewpoints for context.
Explore another United Bankshares fair value estimate, including one that suggests it could be worth just $50.33.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your United Bankshares research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for United Bankshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Bankshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Bankshares?
Once you have formed a view on United Bankshares, it can help to cross check that thinking against other opportunities with similar income or quality profiles using the Simply Wall St Screener.
- If you want income and resilience to work together, start by reviewing a 6 dividend fortresses that focus on higher yields with an emphasis on durability.
- For readers who care most about paying a fair price for quality, scan a 33 high quality undervalued stocks that combine solid fundamentals with valuations that may leave some room for upside.
- If capital preservation is your first filter, consider a 11 resilient stocks with low risk scores that score well on balance sheet strength and overall risk checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com