
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
License Application Withdrawal Could Be A Game Changer For Chubu Electric Power Company (TSE:9502)
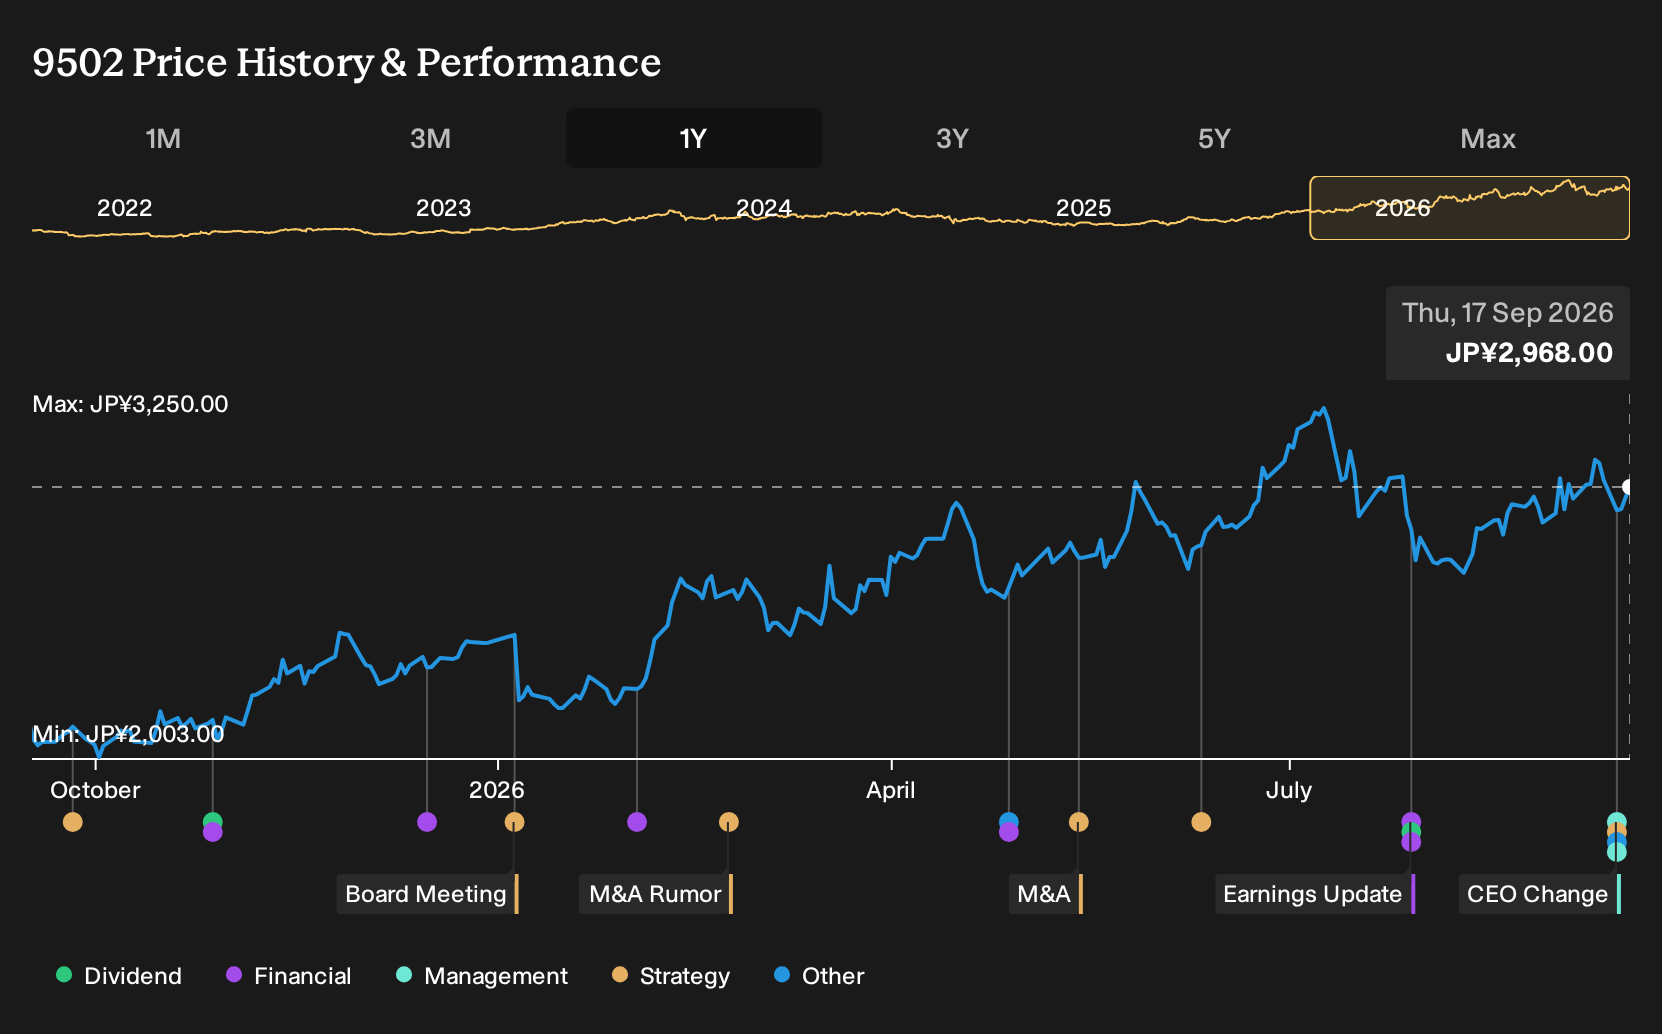
- Chubu Electric Power Company held an extraordinary board meeting on 14 September 2026 and, after an independent investigation raised serious doubts over documentation and regulatory handling at the Hamaoka Nuclear Power Station, resolved to withdraw its license amendment applications for Units 3 and 4.
- The withdrawal leaves Chubu Electric Power Company without active applications under the new nuclear regulatory standards for Hamaoka. This raises fresh questions about long term generation mix, regulatory workload, and potential cost implications tied to revisiting safety case preparation and compliance processes.
- The focus now turns to how Chubu Electric Power Company's investment narrative absorbs the Hamaoka application withdrawal and its implications for regulatory reliability.
What Is Chubu Electric Power Company's Investment Narrative?
To own Chubu Electric Power Company, you need to be comfortable with a heavy, regulated infrastructure business where execution around fuel costs, asset reliability and capital spending matters more than headline growth. Earnings are forecast to grow 7.39% a year even as revenue is expected to edge down 0.2% annually. This puts the focus firmly on efficiency and mix rather than volume. The share price has climbed 49.5% over the past year and trades on a P/E of 12.5x, slightly below the wider JP market and below the Asian electric utilities average. This implies investors already ascribe some confidence in that earnings profile.
The Hamaoka license withdrawal and the simultaneous elevation of Minoru Yasui to President and CEO crystallise the near term debate. Operationally, the key questions now sit around replacement generation, regulatory workload and how much fresh safety and compliance work will weigh on cash flow, given that debt is not well covered by operating cash and the 2.39% dividend is not backed by free cash flow. If you believe Chubu Electric Power Company can keep improving profit quality while managing that balance sheet and nuclear reset, the current value story may still hold.
Even so, there is a quieter balance sheet detail that could matter a lot if ...
There's only one way to know the right time to buy, sell or hold Chubu Electric Power Company. Head to Simply Wall St's company report for the latest analysis of Chubu Electric Power Company's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Chubu Electric Power Company research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Chubu Electric Power Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chubu Electric Power Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Chubu Electric Power Company?
If you want to pressure test your view on Chubu Electric Power Company, compare it with other opportunities that share some of the same financial or risk characteristics. The Simply Wall St Screener can help you quickly filter for different profiles so you are not relying on a single stock to carry your whole thesis.
- If capital preservation matters most to you right now, you can focus on companies that pair resilience with measured risk through our 12 resilient stocks with low risk scores.
- For readers who care about balance sheet strength as much as the income statement, a good starting point is list of solid balance sheet and fundamentals (20 results), which highlights companies that may handle shocks better than most.
- If you are hunting for less crowded opportunities, consider widening your watchlist to include 74 high quality undiscovered gems that combine quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com