
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should New Product Launches Require Action From MSA Safety (MSA) Investors?
- MSA Safety recently rolled out a series of new safety products across firefighting, industrial head protection and aviation fall protection, including Bristol X1 fire suits, GALLET F1 helmets, the V-Gard H2 Full Brim Safety Helmet and the A1X WinGrip vacuum anchor.
- This cluster of launches highlights how MSA Safety is leaning on product development and managed services to deepen relationships with fire brigades, industrial customers and aircraft maintenance providers.
- We will now assess how MSA Safety's investment narrative could be influenced by the new A1X WinGrip aviation fall protection system.
MSA Safety Investment Narrative Recap
For you to back MSA Safety, you need to believe that demand for higher spec, connected and regulated safety equipment keeps supporting its mix of premium products and services. The near term story revolves around whether new launches in fire service, gas detection and fall protection can offset cost pressures from FX, inflation and tariffs that still threaten margins.
The biggest swing factor remains execution on product refresh and connected platforms. The key risk is softer fire service and industrial PPE demand or delayed government funding that leaves new offerings underutilised. The latest product announcements look helpful for the story, but not transformative on their own.
The A1X WinGrip aviation fall protection system is the clearest link to the recent rollout story. It broadens MSA Safety’s reach into aircraft maintenance work, especially where portability, non invasive anchoring and safety around fuel vapours matter. It also ties directly into the company’s push in fall protection, one of its identified growth areas.
From a catalyst perspective, A1X gives the business another way to lean into rising compliance needs in aviation while keeping capital intensity relatively contained. The operational risk is straightforward. If airline and MRO customers are slow to adopt new procedures or stick with legacy setups, the incremental contribution from A1X could lag the expectations now embedded in the broader product narrative.
MSA Safety's current analyst narrative points to revenues of $2.2b and earnings of $409.0 million by 2029, based on assumed yearly top line growth of 5.5% and a move in earnings from $290.5 million today to that 2029 consensus figure. This implies an increase of about $118.5 million over the period.
Discover why MSA Safety's fair value indicates a 14% potential upside to its current price that may not last much longer.
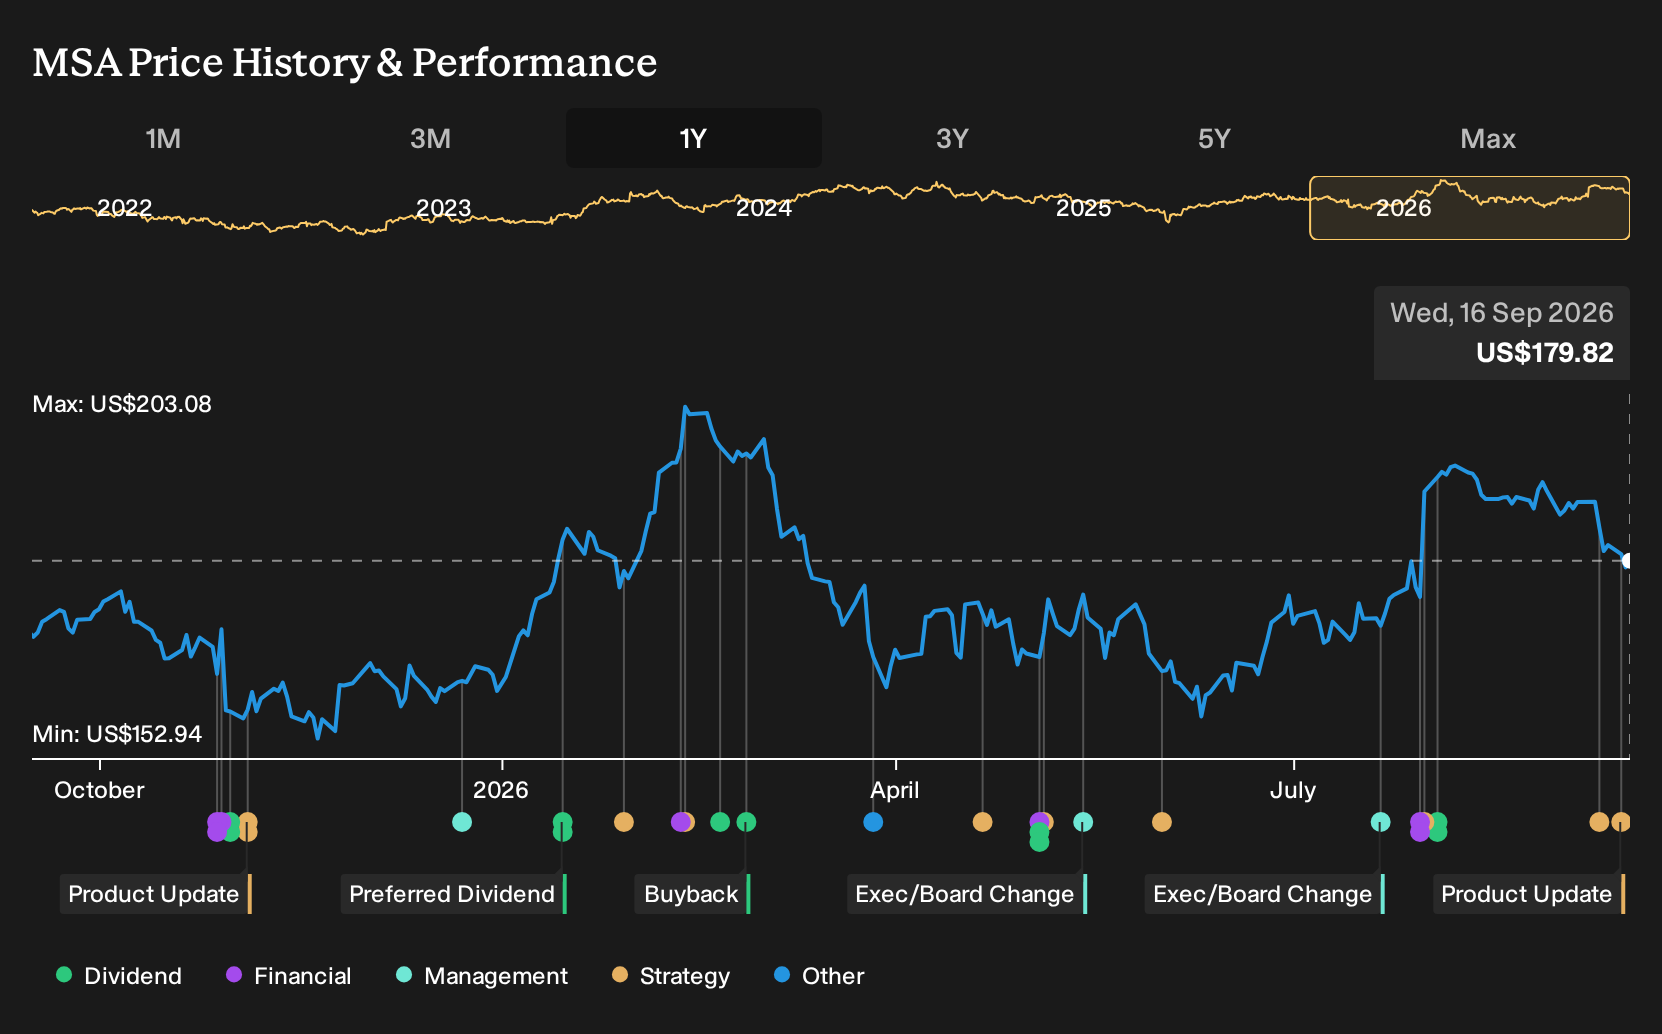
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span a wide band, from about $205.71 up to $324.52, which shows how far opinions on MSA Safety can spread. On one side are fresh product launches and managed services momentum, and on the other are ongoing margin pressure and funding uncertainty. Explore those tensions across multiple community viewpoints before deciding how this story fits your portfolio.
Explore another MSA Safety fair value estimate, including one that suggests as much as 80% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your MSA Safety research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MSA Safety. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MSA Safety's overall financial health at a glance.
Looking For More Investment Ideas Beyond MSA Safety?
Once you have a view on MSA Safety, it can help to compare that thesis with other opportunities that share similar qualities or offer very different risk and reward profiles. The Simply Wall St Screener lets you move from a single stock story to a broader watchlist, filtered around the traits that matter most to you.
- If capital preservation sits high on your list, consider resilient businesses screened for stronger balance sheets and fundamentals through our list of solid balance sheet and fundamentals (22 results).
- For investors hunting for mispriced opportunities, target companies that combine quality metrics with attractive pricing using the 33 high quality undervalued stocks.
- If income is your focus, filter for established payers with higher yields by checking the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com