
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Newell Brands (NWL) Atlanta Design Center Opening
- Newell Brands recently opened a nearly 37,000 square foot Design Center across two Atlanta sites and launched a Crock-Pot collaboration with Valspar pairing new slow cooker colorways with coordinated paint palettes.
- The Atlanta Design Center concentrates AI-enabled design, prototyping, and consumer UX labs, signaling a deeper push into product development and brand differentiation across Newell Brands' portfolio.
- We will examine how Newell Brands' investment narrative is influenced by concentrating design capabilities in Atlanta alongside the Crock-Pot collaboration.
Newell Brands Investment Narrative Recap
For a shareholder in Newell Brands, the core belief is that product design, brand building, and cost work can eventually translate a portfolio of familiar household labels into healthier margins and steadier cash flow. The Atlanta Design Center fits that story. It concentrates design, UX, and AI tools where decisions are made, which may help future product pipelines, even if the financial impact is gradual.
In the near term, the key swing factor is still basic execution on sales and profitability while managing high leverage and an uncovered dividend. Weak categories, tariff exposure, and pressure on lower income consumers remain the biggest threats. The new facility does not change those risks quickly, but it does show the business is still investing behind its brands.
The Crock-Pot collaboration with Valspar is the clearest operational link to this design push. It takes a workhorse appliance and tries to make it part of a coordinated kitchen look, connecting countertop products with paint choices. That is in line with Newell Brands focusing on consumer experience and perceived quality rather than competing purely on price.
As a potential catalyst, this type of partnership tests whether better aesthetics and closer alignment with home décor can support volumes and pricing in Home and Commercial Solutions. The risk is that softer discretionary demand or stronger private label competition limits the benefit, leaving fixed costs and debt as the main financial constraints even while design led launches continue.
Analysts are effectively sketching a reset scenario for Newell Brands. They are working with revenue growing about 1.6% a year and earnings today at a loss of $281.0 million shifting to a forecast profit of $527.4 million by 2029. That implies an earnings swing of about $808 million and would line up with consensus expectations for roughly $7.5 billion in revenue and $527.4 million in earnings in 2029.
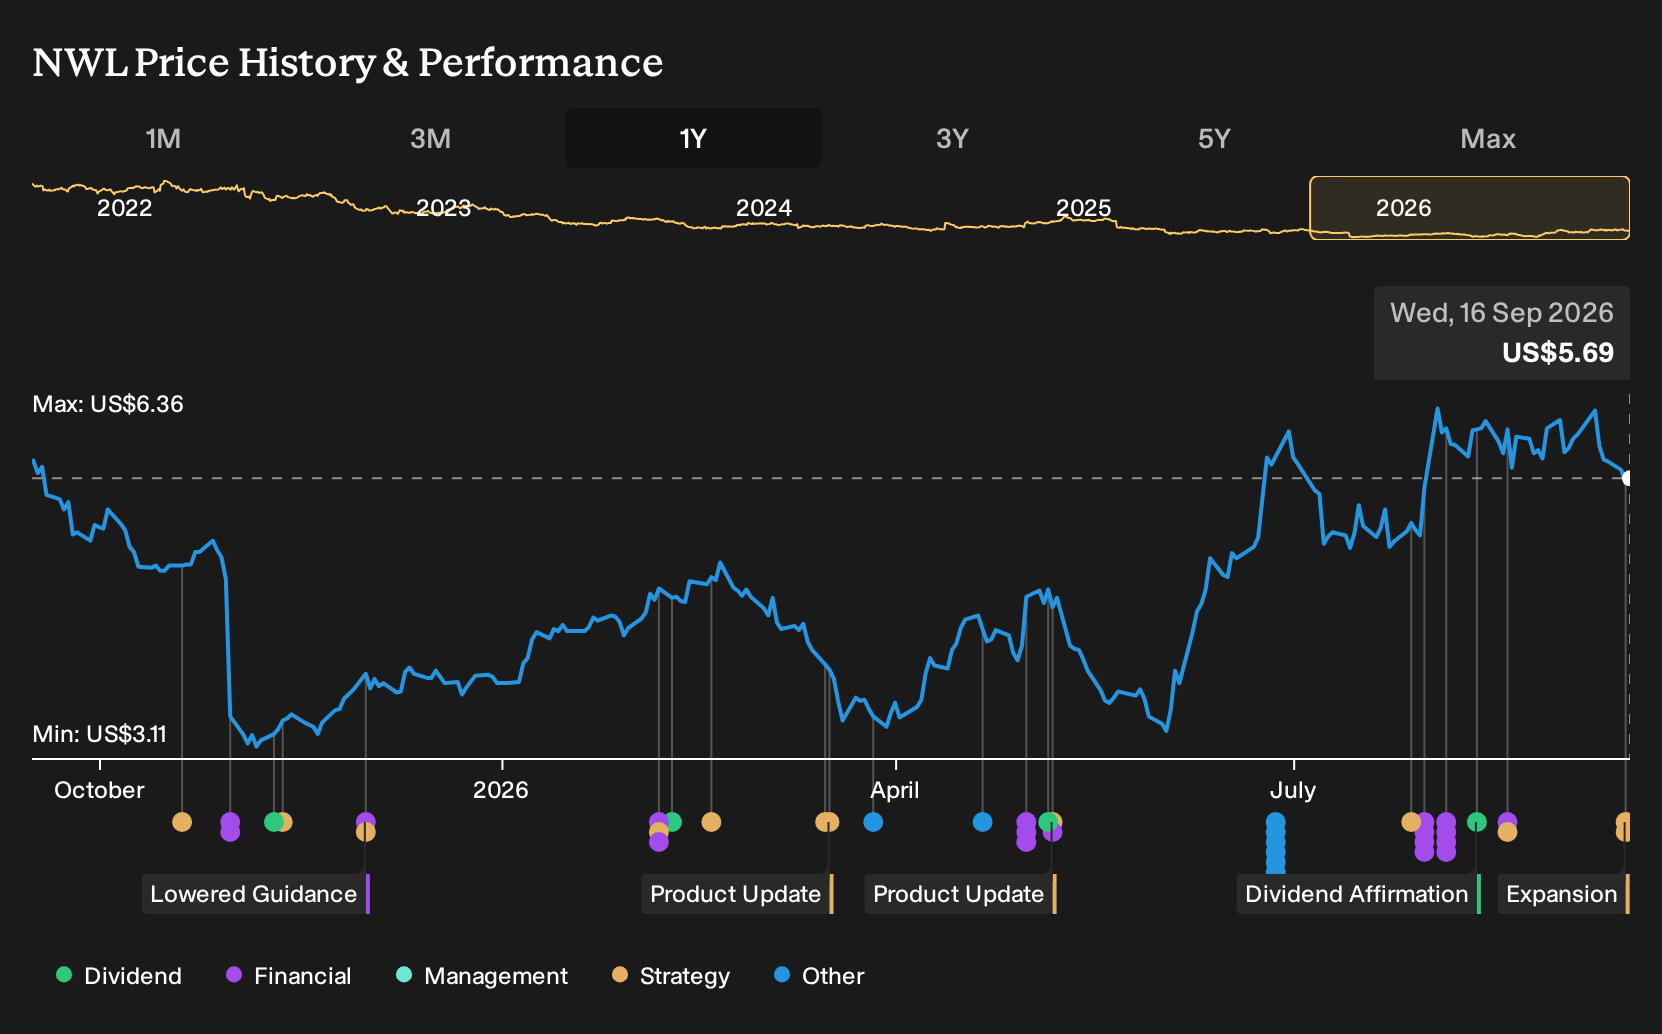
Discover why Newell Brands' fair value appears to be broadly consistent with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts focus on the manufacturing edge rather than design. They argue Newell Brands could use its U.S. and Mexico capacity to grab share, which is why they were modeling revenue at about $7.9b and earnings near $637.7 million by 2029. Those views predate today’s design news, so opinions may evolve and diverge further.
Explore 3 other Newell Brands fair value estimates, including one that suggests potential upside of as much as 280% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Newell Brands research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Newell Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Newell Brands' overall financial health at a glance.
Looking for more Newell Brands style ideas?
If the Newell Brands story has sharpened your thinking about design, brands, and balance sheets, it can help to line it up against other companies with similar traits. The Simply Wall St Screener lets you quickly filter for different qualities so you can build a watchlist that actually fits your investing style.
- If capital preservation matters most to you, start with a basket of steadier candidates by reviewing 11 resilient stocks with low risk scores that have been filtered for resilience and lower risk profiles.
- If you want income on top of potential price gains, check out a focused group of higher yielding opportunities with the 6 dividend fortresses that currently offer 5%+ yields.
- If balance sheet strength is non negotiable for you, shortlist financially robust businesses through the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com