
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Global Payments (GPN) Could Be 15% Undervalued After Worldpay Integration Focus
Global Payments (GPN) remains in focus after recent analyst commentary highlighted the impact of its Worldpay integration and digital payment trends, raising fresh questions about how investors should think about the stock today.
Recent trading in Global Payments has been choppy, with the share price down 2.8% over the past day and 4.3% over the past month, even after a strong 29.3% 90 day share price return that lifted year to date gains to 14.5%. This contrasts with a far weaker 3 year total shareholder return of 27.2% and 5 year total shareholder return of 43.6%.
Contrast Global Payments' mixed share price swings with other payment and fintech players by scanning our hand-picked 33 high quality undervalued stocks that currently screen well on both quality and valuation.Given that Global Payments has just delivered a strong 90 day rebound yet still carries weaker multi year returns, do you commit fresh capital now or wait for a clearer valuation reset before stepping in?
Most Popular Narrative: 15% Undervalued
Global Payments last closed at $86.49, which sits below the most followed narrative fair value estimate of $101.71 and frames the debate around whether recent weakness offers compensation for the risks in the story.
The Worldpay acquisition and operational transformation program are creating scale benefits, cost efficiencies, and significant cross-selling opportunities (for example, selling Genius into Worldpay's merchant base); these are expected to boost earnings growth and margin expansion after integration.
See why 43 investors see Global Payments as 15% undervalued.
Result: Fair Value of $101.71 (UNDERVALUED)
Still, that underpricing story can unravel quickly if Worldpay integration setbacks hit earnings quality, or if rising competition and regulation squeeze Global Payments' future fee economics.
Find out about the key risks to this Global Payments narrative.
Another View on Global Payments Valuation
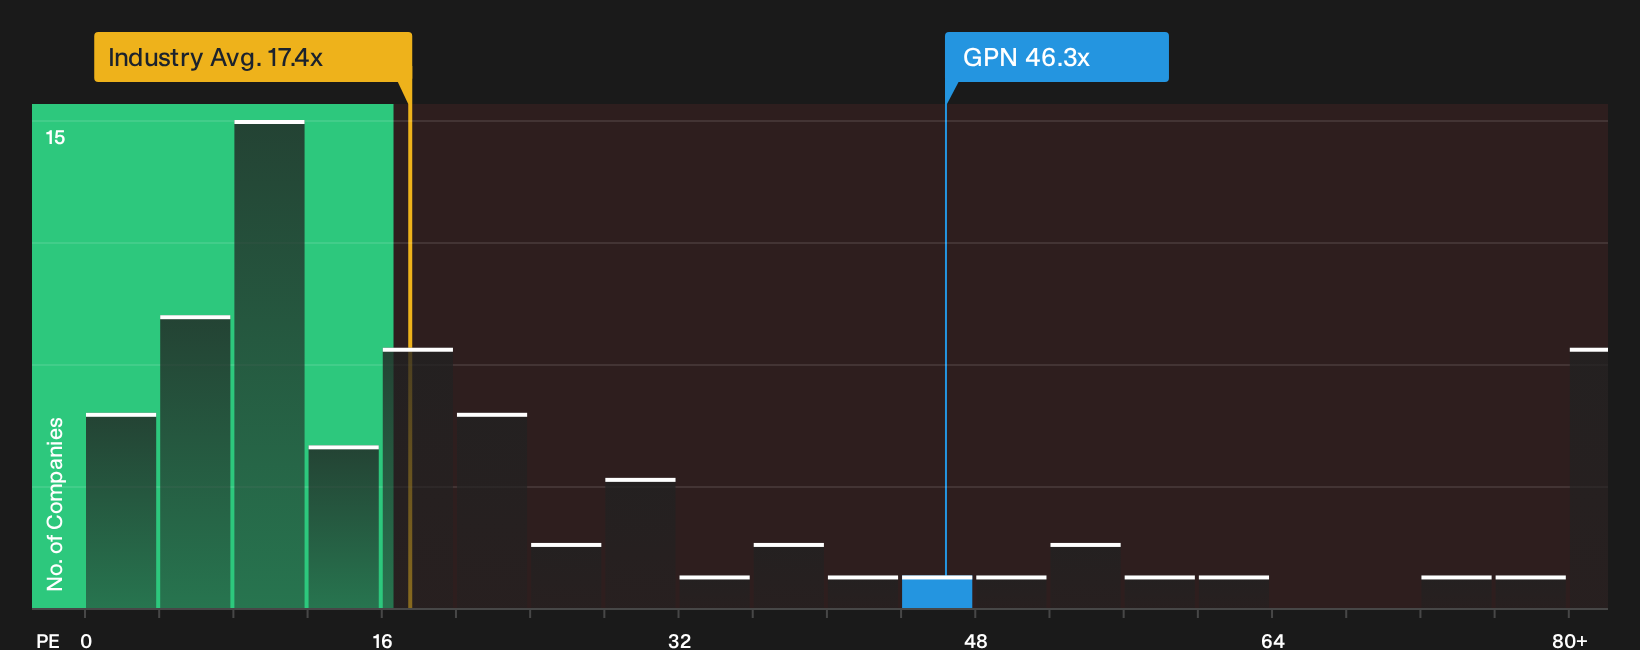
That fair value of $101.71 leans heavily on earnings forecasts and narrative assumptions. A different lens comes from looking at how Global Payments is priced today on a simple P/E basis. The stock trades at 46.3x compared with 17.4x for the US Diversified Financial industry and 13.4x for closer peers. The fair ratio points to 36.5x. So the market is already paying a premium over both sector and peer averages, and even above the level our fair ratio suggests the P/E could move toward. Is that premium a reasonable price for the Worldpay story, or is it asking you to pay up before execution risk is fully behind the business?
See what the numbers say about this price in more detail in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed signals around Global Payments skew more positive or negative right now? Act while the data is fresh and stress test the full set of trade offs through 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Global Payments?
If Global Payments has you thinking harder about risk and reward, consider going beyond a single ticker. A broader watchlist could help sharpen your next decision.
- Target resilient compounding and broaden your opportunity set by scanning a carefully filtered 11 resilient stocks with low risk scores that already meet strict risk checks.
- Spot potentially overlooked growth stories early by reviewing our focused 16 high quality undiscovered gems before they attract wider attention.
- Strengthen your defensive side by using the curated list of solid balance sheet and fundamentals (22 results) to find businesses with sturdier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com