
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Raised 2026 Revenue Guidance At Flotek Industries Stock Has Changed Its Investment Story
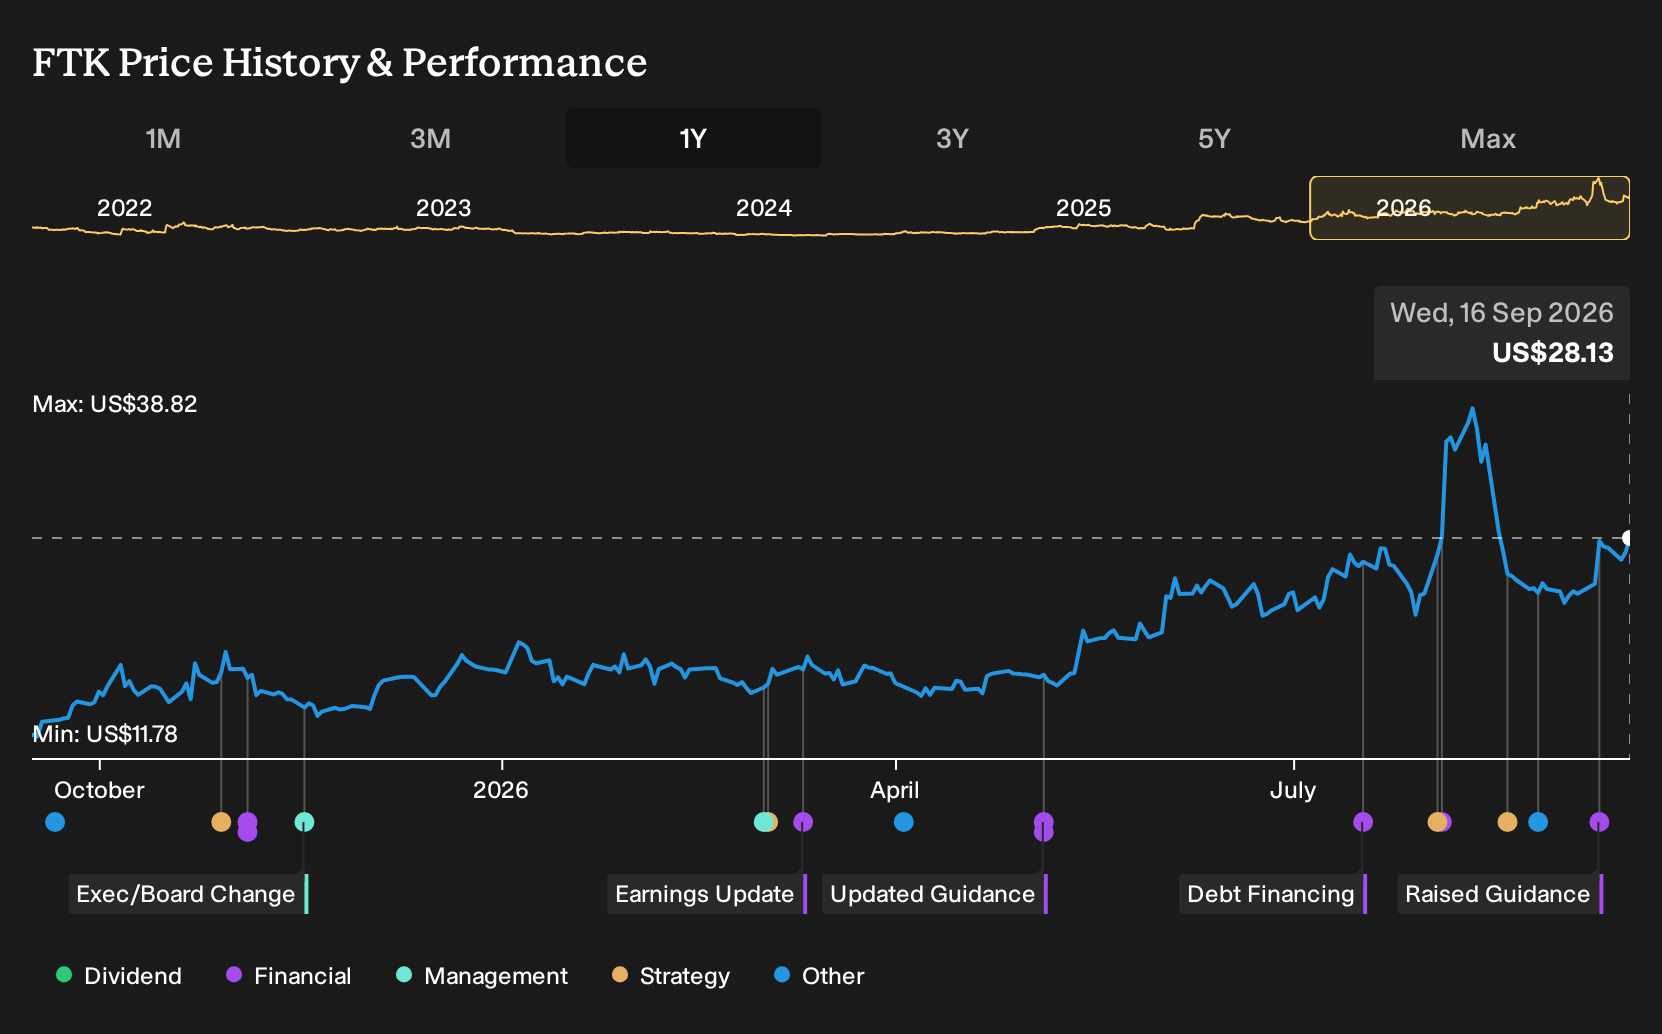
- Flotek Industries raised its 2026 total revenue guidance to a range of $360 million to $370 million, up from a prior outlook of $340 million to $350 million, citing a stronger current view for international chemistry sales in the back half of the year.
- The wider revenue band signals that management sees more robust demand for its chemistry offerings abroad, which matters for an investment case that leans heavily on recurring, higher margin solutions and a broader customer base beyond a few large contracts.
- We will look at how Flotek Industries' investment narrative shifts as higher 2026 revenue guidance leans on global chemistry demand momentum.
Flotek Industries Investment Narrative Recap
To own Flotek Industries, you need to believe the chemistry and data analytics mix can keep turning contract visibility into steadier cash generation, even as energy markets evolve. The raised 2026 revenue outlook leans on international chemistry demand, which supports the near term catalyst of proving that these offerings can scale outside a few flagship customers.
The biggest near term risk still sits with customer concentration and execution on newer platforms like PWRtek and real time monitoring. Higher 2026 guidance does not remove that. It instead provides more line of sight that current contracts and pilots are converting into activity, especially in overseas chemistry, while end market and commodity risks remain.
The most relevant piece of context here is the existing growth and profitability profile investors are already watching. Flotek Industries produced revenue of about $293 million and net income of roughly $38 million, with earnings growth over the past year very strong and margins currently around 13%, which is higher than the prior year level.
Analysts expect earnings to grow at 5.6% per year and revenue at 9.8% per year, with data analytics and energy infrastructure often viewed as key drivers. The new 2026 revenue guidance ties directly into that narrative. It puts more focus on how well Flotek can convert higher chemistry demand and its patented analytics solutions into recurring, high margin contracts while managing customer and funding risks.
Flotek Industries' narrative projects US$362.3 million revenue and US$29.1 million earnings by 2029. This lines up with analyst assumptions of 7.3% yearly revenue growth and an earnings decrease of US$8.9 million from US$38.0 million today.
Uncover how Flotek Industries' fair value indicates a 36% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view leans heavily on international chemistry as the real swing factor for Flotek Industries. The most optimistic analysts were already penciling in roughly 10.5% yearly revenue growth to about US$395.3 million and earnings near US$37.5 million by 2029. You should expect those pre news assumptions to evolve as fresh guidance filters through and different viewpoints sharpen.
Explore 3 other Flotek Industries fair value estimates, including one that suggests potential upside of up to 49% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Flotek Industries research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Flotek Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flotek Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Flotek Industries?
If Flotek Industries has sharpened your focus on contract quality, balance sheets, and recurring revenue, it makes sense to widen the search using screeners that apply the same discipline to a broader set of companies.
- For investors who want potential mispricings backed by stronger fundamentals, start with a curated group of 33 high quality undervalued stocks that may warrant deeper research.
- If capital preservation and stability matter most to you, focus on businesses with sturdier finances by reviewing the list of solid balance sheet and fundamentals (22 results).
- When your priority is smoother portfolio swings and steadier risk profiles, narrow your watchlist using the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com