
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How White Label ETF Expansion At BNP Paribas (ENXTPA:BNP) Has Changed Its Investment Story
- BNP Paribas has appointed former BlackRock ETF capital markets head Van Nugteren, who joined the French group in June 2026, to lead its expanding white label ETF business, while also issuing an interest payment notification for its BNPS13 instrument on the JSE.
- The hire of a specialist in ETF capital markets signals that BNP Paribas is putting more execution heft behind outsourced ETF launches for third party managers, aiming to deepen fee based, capital light activity.
- We will now look at how BNP Paribas's new white label ETF leadership might reshape the existing investment narrative around fee income.
Scan BNP Paribas alongside other fee focused financials to see how it stacks up against 619 high quality undiscovered gems quietly building capital light income streams.
BNP Paribas Investment Narrative Recap
To own BNP Paribas, you need to be comfortable with a large Eurozone lender that is trying to tilt more toward fee based, capital light activities while still carrying the weight of a complex, high cost commercial banking engine. The short term story hinges on execution in wealth, asset management and digital, while keeping returns on equity from slipping further.
The appointment to lead the white label ETF push fits cleanly into that effort. It deepens the toolkit to grow fee income and diversify away from balance sheet heavy lending. The bigger immediate risk still sits in traditional Eurozone banking, from margin pressure, higher regulation and the quality of the loan book and funding mix.
The interest rate payment notice on the BNPS13 instrument is the most relevant companion announcement. It shows BNP Paribas continuing to service wholesale funding in South Africa on schedule, with a 9.1% rate on that tranche and settlement handled through JSE systems. For a bank with 62% of liabilities in higher risk funding, that operational detail matters.
Debt market discipline can either support or constrain the catalysts investors care about. A clean record on interest payments helps management keep flexibility for activities such as integrating AXA IM and HSBC WM Germany, expanding digital platforms and scaling the white label ETF effort. Any loss of market confidence in funding would work in the opposite direction and could weigh on both growth projects and capital returns.
BNP Paribas' current analyst narrative points to €60.9b in revenue and €16.4b in earnings by 2029, based on projected 5.9% yearly top line growth and an earnings increase of €3.6b from €12.8b today.
Uncover how BNP Paribas' fair value indicates a 14% potential upside to its current price that may not last much longer.
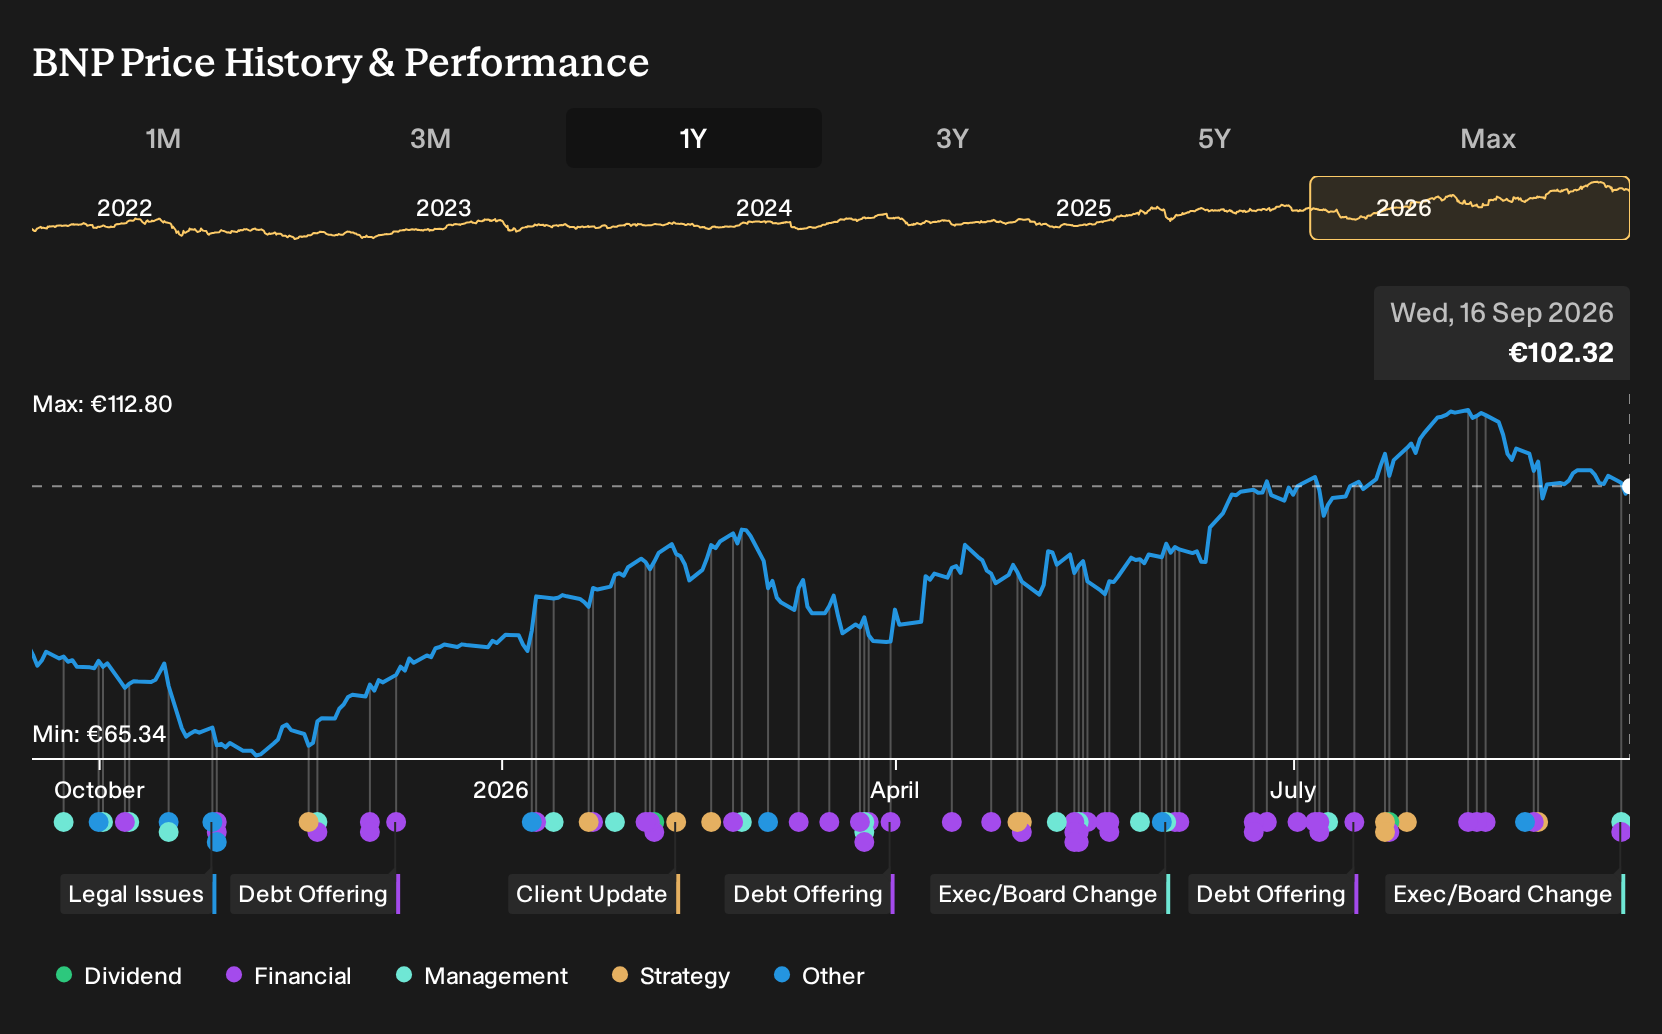
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight €106 to €117 band, which still leaves room for very different conclusions about BNP Paribas today. Some community members focus on the white label ETF hire and roadshows as potential fee catalysts. Others worry more about Eurozone banking costs and regulatory capital pressure. Explore those contrasting views before deciding where you sit.
Explore another BNP Paribas fair value estimate, including one that suggests it could be worth just €106.35.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BNP Paribas research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for BNP Paribas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BNP Paribas' overall financial health at a glance.
Looking for more investment ideas beyond BNP Paribas?
Once you have a view on BNP Paribas, you can broaden your watchlist with other companies that match the type of risk, income profile, or balance sheet strength you prefer. The Simply Wall St Screener can help you quickly find candidates that line up with your own framework instead of just following headlines.
- If you want quality paired with a potential valuation gap, start with a 189 high quality undervalued stocks that already combine strong fundamentals with pricing that may not fully reflect them.
- For investors who care most about resilience, filter for companies on the 104 resilient stocks with low risk scores that score well on financial health and business stability metrics.
- If you are looking for under the radar opportunities, scan the 619 high quality undiscovered gems where fundamentals look solid but attention from the wider market still appears limited.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com