
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why PG&E (PCG) Is Getting Fresh Attention Now
Recent analyst coverage has pushed PG&E (PCG) into focus as a perceived value play in the electric utility sector, with the stock drawing attention for its earnings outlook and valuation metrics.
PG&E’s share price at about $13.35 reflects a mixed recent run, with the 1-month share price return down 23.71% and the year-to-date share price return down 17.95%. However, the 5-year total shareholder return is still up 37.62%, signaling that long-term holders have fared better even as near term momentum has faded and fresh value-focused coverage refocuses attention on the stock’s risk and reward trade off.
Spot undervalued utilities gaining fresh analyst interest by scanning our hand picked 33 high quality undervalued stocks alongside PG&E.PG&E now trades well below recent analyst targets after a sharp slide, so the key question is straightforward: Has most of the easy value already been captured, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 36% Undervalued
PG&E’s widely followed valuation story pegs fair value at about $20.78 per share, well above the recent $13.35 close. That gap rests heavily on how future grid spending and wildfire protections play out.
Expanding opportunities for capital investment in grid modernization, wildfire mitigation, and resilience, fueled by both regulatory mandates and the need to serve new electrification and decarbonization requirements, position PG&E to grow its rate base and regulated earnings steadily over the next decade.
See why 25 investors see PG&E as 36% undervalued.
Result: Fair Value of $20.78 (UNDERVALUED)
Still, PG&E’s wildfire liability exposure and the possibility of less supportive California regulation could quickly upend the current undervalued narrative.
Find out about the key risks to this PG&E narrative.
Another View: PG&E Looks Expensive On Cash Flows
While the popular PG&E story leans on a fair value of about $20.78, the SWS DCF model pulls in the opposite direction. On that cash flow view, the estimated value sits near $9.60 per share, which implies the current $13.35 price already bakes in a lot of optimism. Which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
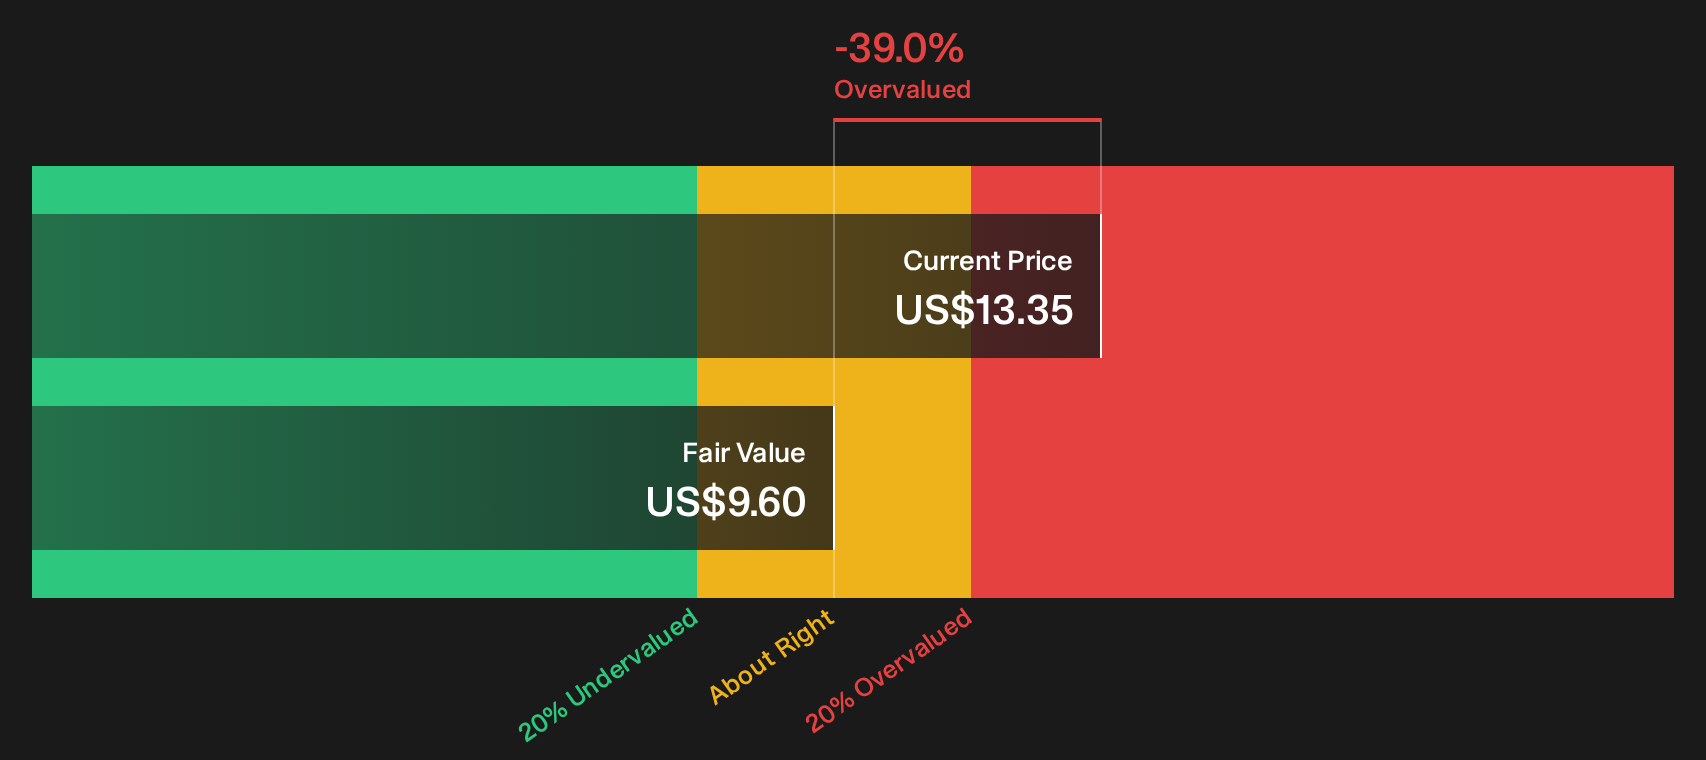
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PG&E for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about whether PG&E’s story skews more toward risk or reward after all this? Move quickly on your own homework by weighing the 4 key rewards and 3 important warning signs.
Want more ideas beyond PG&E?
If PG&E has you thinking harder about risk, reward, and price, do not stop with just one ticker when there are focused stock ideas waiting.
- Target resilient defense for your portfolio by checking companies on the 11 resilient stocks with low risk scores that aim to keep downside contained.
- Hunt for potential mispricing by reviewing the 16 high quality undiscovered gems where strong fundamentals may not yet have wide attention.
- Boost your income watchlist by scanning the 6 dividend fortresses that spotlight higher yield opportunities with staying power in mind.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com