
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Terex (TEX) Could Be 26% Undervalued On Laguna Conference Appearance
Terex (TEX) is set to present at Morgan Stanley's 14th Annual Laguna Conference on 15 September 2026 in Laguna Beach, an event investors often watch for management commentary and capital allocation clues.
Terex shares have pulled back recently, with the 30-day share price return down 12.65% and the 90-day move lower by 11.97%, even though the year-to-date share price return is 6.89% and the 1-year total shareholder return sits at 13.14%.
Scan beyond Terex and see how other industrials are reacting to this pullback by running them through our curated list of list of solid balance sheet and fundamentals (22 results).
Terex now trades at a sizeable discount to both analyst targets and some intrinsic value estimates after that pullback. Is this simply caution well placed, or has pricing drifted too far from fundamentals, as the valuation work shows next?
Most Popular Narrative: 26% Undervalued
Terex closed at $58.82, while the most followed narrative pegs fair value closer to $79.46. The market is pricing in a wide gap that this view attributes to execution and longer term demand drivers rather than short term volatility.
The sustained increase in global infrastructure and manufacturing investment, supported by recent policy incentives such as enhanced bonus depreciation and significant federal construction allocations, is driving multi-year demand for Terex's construction, utility, and materials processing equipment, positioning the company for steady revenue growth as both U.S. and international markets upgrade infrastructure and manufacturing capacity.
See why 12 investors see Terex as 26% undervalued.
Result: Fair Value of $79.46 (UNDERVALUED)
Still, pressure from high interest rates on equipment purchases and ongoing tariff related cost inflation could easily weaken parts of the Terex investment case.
Find out about the key risks to this Terex narrative.
Another View On Terex’s Valuation
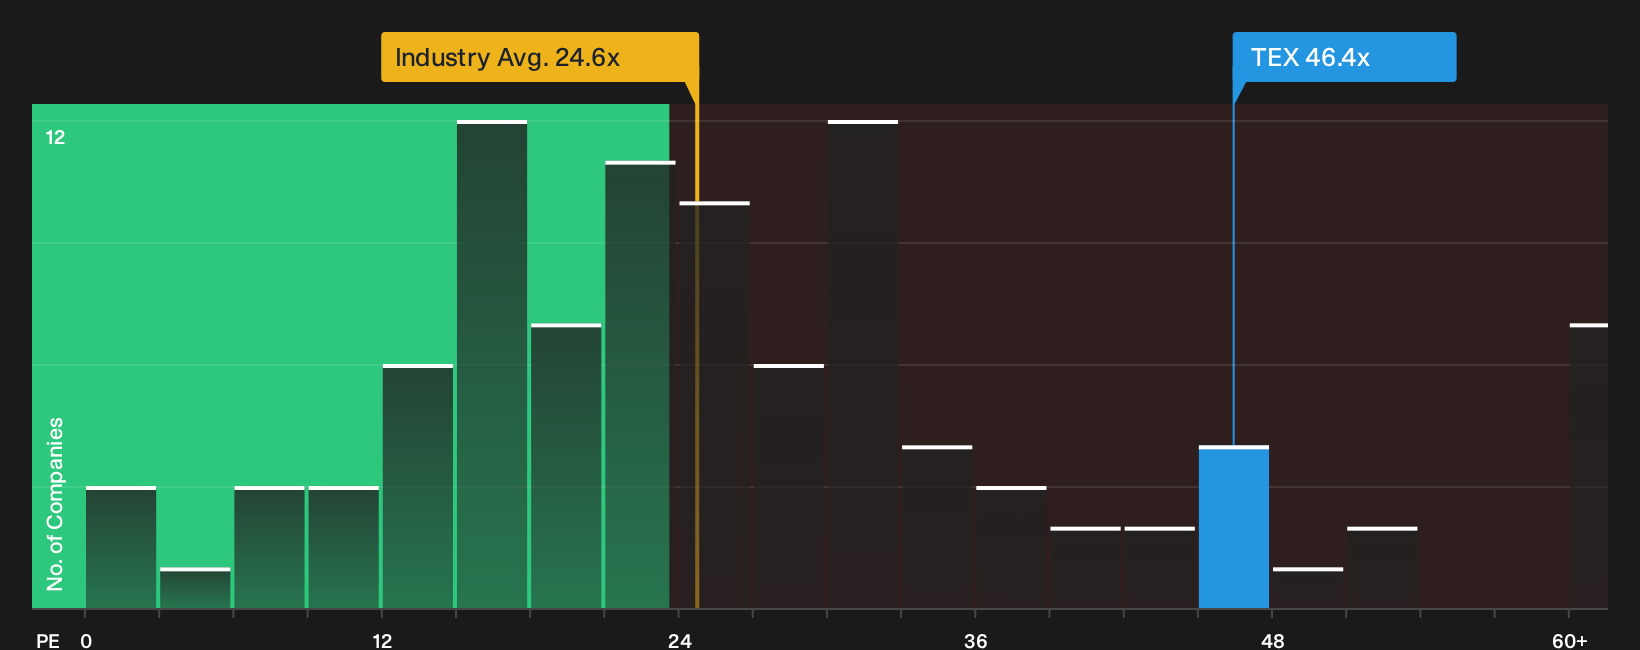
The first lens paints Terex as 26% undervalued, yet the earnings multiple tells a different story. The stock trades on a P/E of 46.4x versus 24.3x for the US Machinery group and a fair ratio of 62.4x, which hints at richer pricing and a very different risk profile for buyers.
Putting both lenses together raises a simple question: Is the bigger opportunity in the discount to intrinsic value, or in the possibility that the market leans back toward sector level multiples before it ever does?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
See a mix of caution and optimism around Terex and feel unsure which side to lean toward. Act now by weighing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Terex?
If Terex has you thinking harder about valuation and risk, do not stop here. Broaden your watchlist with a few focused idea lists built around clear filters.
- Target potential mispricings by scanning a curated set of 33 high quality undervalued stocks that combine quality fundamentals with marked discounts to their estimated worth.
- Prioritize resilience by reviewing a 11 resilient stocks with low risk scores that screens for stronger balance sheets and more stable risk profiles.
- Get ahead of the crowd by researching a 16 high quality undiscovered gems that highlights financially solid businesses receiving relatively little attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com