
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Green Thumb Industries (CNSX:GTII) RISE Store Expansion
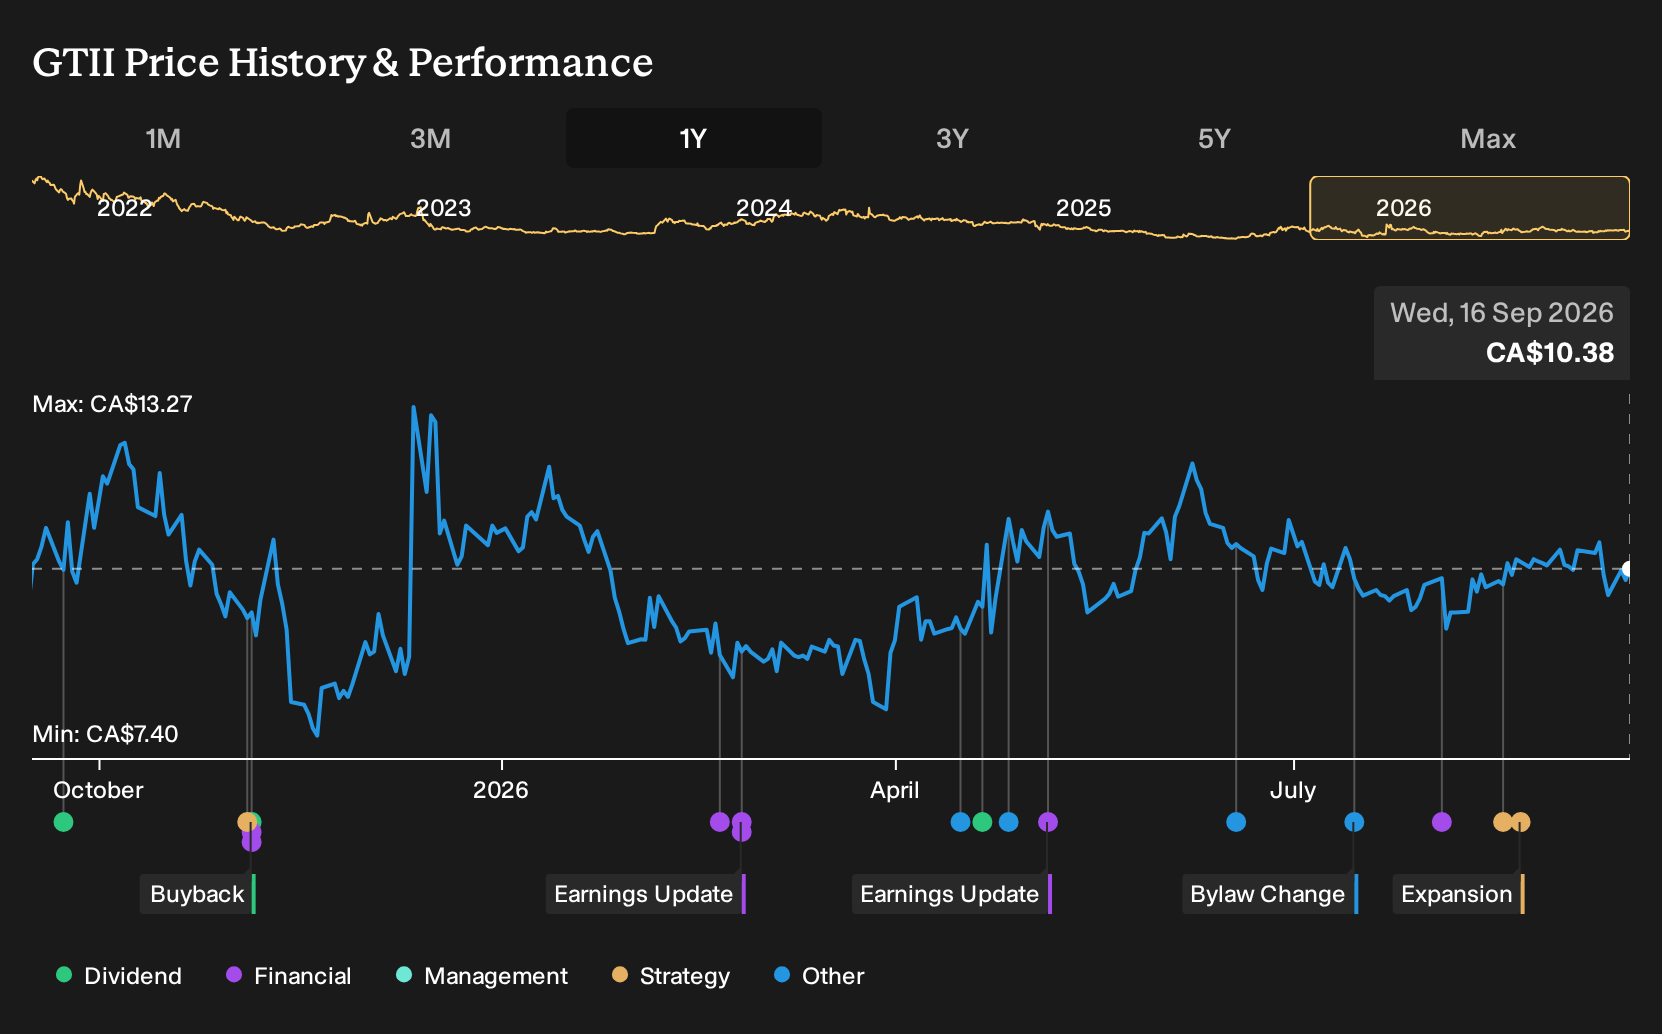
- Green Thumb Industries expanded its RISE Dispensaries network and sharpened its cannabis consumer products focus, which investors viewed positively because of the operating execution required to scale retail and branded goods together.
- The reaction highlighted how brick and mortar expansion tied to a clear consumer product thesis can matter more for Green Thumb Industries than short term trading moves or external sentiment shifts.
- We will look at how Green Thumb Industries' investment narrative evolves as RISE Dispensaries expansion becomes a more central execution theme.
Scan how other cannabis operators with expanding retail footprints are lining up by reviewing our hand picked 9 high quality undiscovered gems alongside Green Thumb Industries' latest moves.
Green Thumb Industries Investment Narrative Recap
To own Green Thumb Industries, you need to buy into a simple idea. The real prize is building a large, efficient U.S. cannabis platform where branded products move consistently across a scaled RISE Dispensaries network and third party shelves, even while pricing across the sector stays under pressure.
The latest rally around retail expansion does not really change the near term story. Execution on new stores and CPG sell through remains the key near term catalyst, while the biggest risk is still heavy capital spending and potential overbuild if same store trends soften or regulatory progress slows.
The most relevant development is Green Thumb Industries leaning harder into RISE Dispensaries as a growth channel. Every new location tightens the loop between cultivation, brands, and direct customer traffic, which matters when analysts expect earnings to decline on average over the next three years.
This build out can support the existing catalyst list, from new adult use states to broader CPG distribution, because it gives the business more controlled points of sale. It also raises the stakes on execution risk, since higher fixed costs and competitive price compression could weigh on margins if store productivity lags expectations.
Green Thumb Industries' current consensus storyline points to revenue of $1.4b and earnings of $22.9 million by 2029, off a base of $121.2 million in earnings today and revenue that analysts expect to grow at 4.9% per year. This implies an earnings decline of about $98 million over that stretch rather than growth.
Uncover why Green Thumb Industries' fair value indicates a 96% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Green Thumb Industries leans hard into federal legalization as the swing factor. Bullish analysts were already modeling revenue of about $1.5b and earnings of $58.7 million by 2029, far above the consensus $1.4b and $22.9 million. More optimistic voices may revisit their story after this expansion news.
Explore 5 other Green Thumb Industries fair value estimates, including one that suggests as much as 147% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Green Thumb Industries research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Green Thumb Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Green Thumb Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Green Thumb Industries?
Once you have a handle on Green Thumb Industries, it can help to widen the lens and compare it with other opportunities that fit clear, rules based criteria using the Simply Wall St Screener.
- If you want potential upside with strict quality filters, scan a curated set of 9 high quality undiscovered gems that share strong fundamentals and cleaner balance sheets.
- For those who care most about resilience, focus on capital preservation first by checking companies in our 1 resilient stocks with low risk scores with lower risk scores and sturdier financial profiles.
- If steady cash flows matter most to you, zero in on dependable income payers by reviewing a range of 2 dividend fortresses that combine higher yields with business durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com