
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Asana (ASAN) Q2 Results Put Its Valuation Back In Focus
Asana (ASAN) just paired fresh second quarter results with new guidance for fiscal 2027, giving you clearer numbers on revenue, losses, and expected operating margins to assess the current share price.
Recent trading suggests investors are reassessing Asana. The 90-day share price return of 39.45% and 7-day move of 16.97% point to building momentum, even though the year-to-date share price return has fallen 25.54% and the 1-year total shareholder return has declined 29.77% from a much weaker multiyear base.
Spot fresh momentum in Asana, and then widen your watchlist by comparing it with a hand picked group of 33 high quality undervalued stocks that also pair revenue growth with disciplined cost control.The rebound in Asana after a long stretch of weak multi year returns puts fresh pressure on the numbers to justify the move. Do the current valuation metrics still skew the risk reward toward buyers?
Most Popular Narrative: 4% Overvalued
Asana's most followed narrative pegs fair value at $9.27 using an 8.85% discount rate, which sits slightly below the recent $9.65 close and frames the current rally as a modest stretch above that model.
Asana's integration of AI into structured workflow automation (AI Studio, smart workflows, and upcoming AI Teammates) is unlocking new, highly valued enterprise use cases that increase platform stickiness, boost customer expansion and drive higher ARPU, supporting accelerated mid
to long-term revenue growth.
See why 13 investors see Asana as 4% overvalued.
Result: Fair Value of $9.27 (OVERVALUED)
Still, rising competition from larger platforms and pressure on net retention from big enterprise renewals could quickly challenge the current Asana fair value story.
Find out about the key risks to this Asana narrative.
Another View On Asana’s Valuation
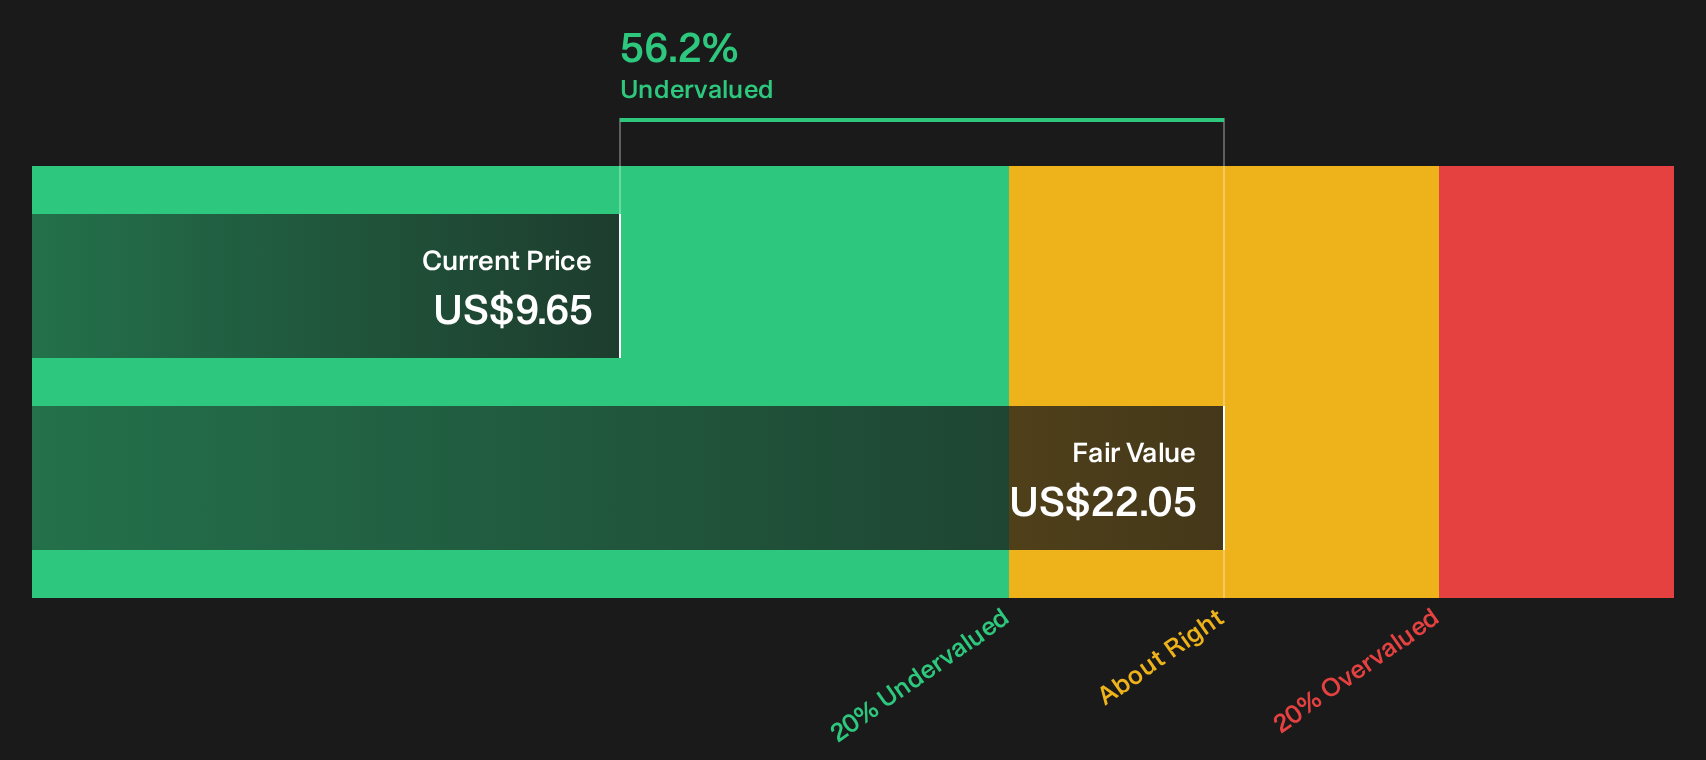
While the most popular narrative frames Asana as slightly overvalued around a fair value of $9.27, a different lens presents a stronger value case. Our DCF model indicates a future cash flow value of $22.05, which is substantially higher than the recent $9.65 share price. For investors, the key question is whether to focus on a modest premium to narrative fair value or a sizable discount based on cash flow estimates.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Asana's value story are clear, so move quickly, review the full risk and reward breakdown, and weigh the 3 key rewards and 2 important warning signs
Ready for more investment ideas beyond Asana?
If Asana has caught your eye, broaden your opportunity set now with a few targeted stock ideas pulled straight from the Simply Wall St Screener.
- Target steadier compounding by reviewing companies built around resilient cash flows and consistent profitability using the 11 resilient stocks with low risk scores.
- Hunt for potential mispricing by scanning a curated pool of quality businesses trading below their estimated worth through the 33 high quality undervalued stocks.
- Stack income and fundamentals together by checking companies that combine stronger balance sheets with attractive payout profiles via the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com