
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Discovering Asia's Undiscovered Gems This September 2026
In recent weeks, Asian markets have been navigating a complex landscape marked by geopolitical tensions and fluctuating oil prices, which have influenced investor sentiment and economic indicators. Despite these challenges, small-cap stocks in the region continue to attract attention for their potential to outperform in volatile environments due to their agility and niche market positions. Identifying promising stocks within this context requires a focus on companies with strong fundamentals and resilience against broader market uncertainties.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Cybozu | 0.16% | 17.06% | 54.02% | ★★★★★★ |
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Jangho Group (SHSE:601886)
Simply Wall St Value Rating: ★★★★★★
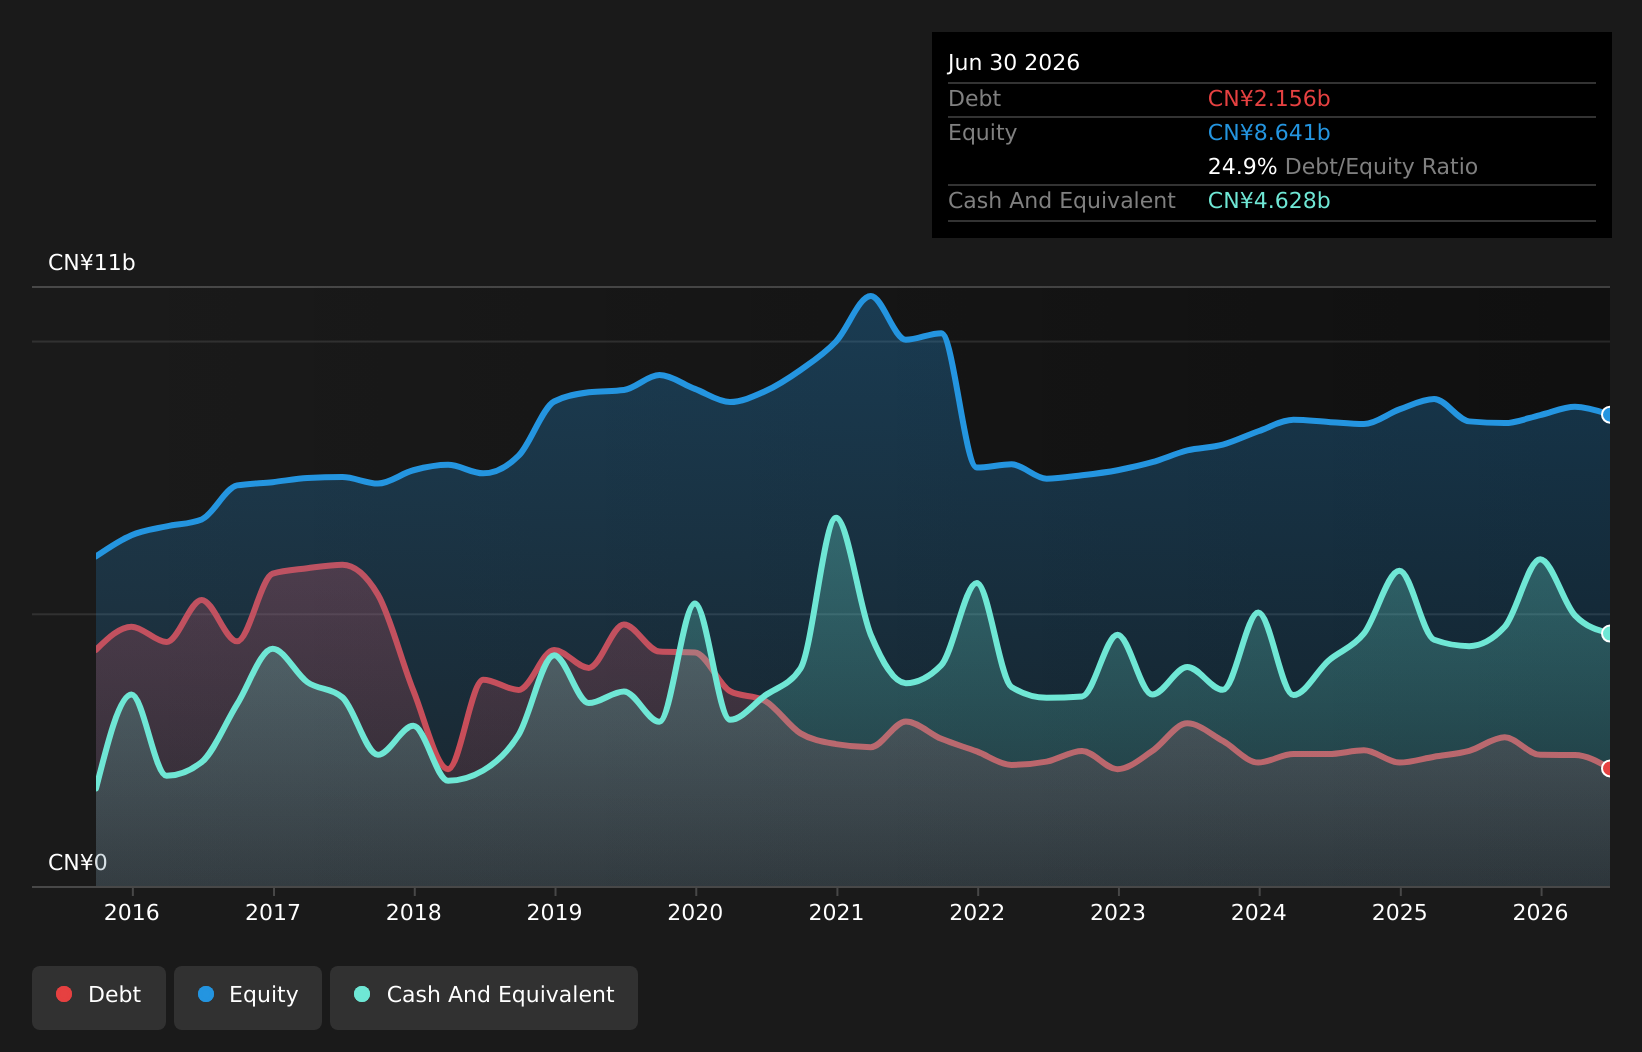
Overview: Jangho Group Co., Ltd. operates in the building decoration and medical health sectors both within China and globally, with a market cap of approximately CN¥14.88 billion.
Operations: Jangho Group generates revenue from its building decoration and medical health businesses across China and internationally. The company has a market capitalization of approximately CN¥14.88 billion.
Jangho Group, a smaller player in the construction sector, showcases promising growth with earnings rising by 12.4% over the past year, outpacing the industry average of -16.3%. Its net income for H1 2026 reached CN¥440.53 million, up from CN¥327.94 million a year earlier, reflecting solid operational performance. Trading at about 42% below its estimated fair value indicates potential undervaluation compared to peers. The company has more cash than total debt and its interest payments are well covered by EBIT at 29 times coverage, highlighting robust financial health despite a significant one-off loss of CN¥273.3 million impacting recent results.
- Delve into the full analysis health report here for a deeper understanding of Jangho Group.
Gain insights into Jangho Group's historical performance by reviewing our past performance report.
ARE Holdings (TSE:5857)
Simply Wall St Value Rating: ★★★★☆☆
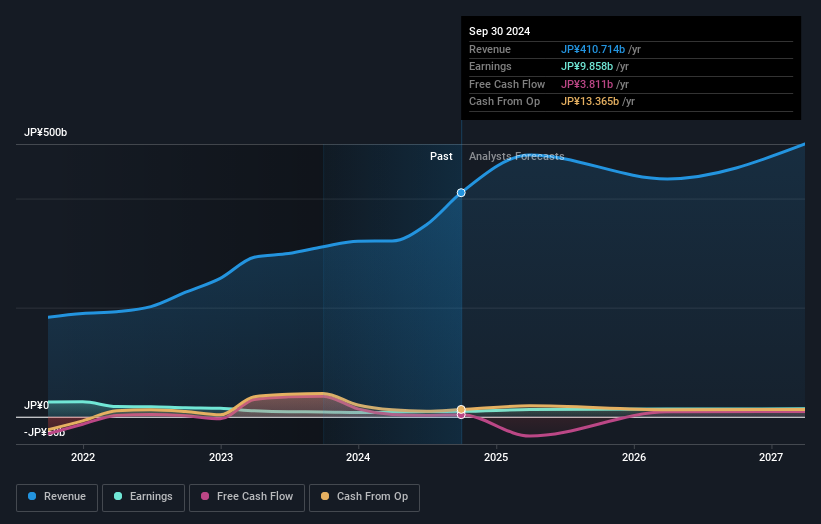
Overview: ARE Holdings, Inc. is involved in the refining, manufacturing, and trading of precious metals and rare metals across Japan, Asia, and North America with a market capitalization of ¥314.56 billion.
Operations: The primary revenue stream for ARE Holdings comes from its Precious Metals Business, generating ¥629.91 billion. The company's market capitalization stands at ¥314.56 billion.
ARE Holdings has been on a roll, with earnings surging by 99.3% over the past year, significantly outpacing the Metals and Mining industry’s 26.1% growth rate. Trading at 46.1% below its fair value estimate, it presents an attractive opportunity compared to peers. However, the net debt to equity ratio stands at a high 105.1%, though it has improved from previous levels of 121.1%. Despite this leverage, interest payments are well covered with EBIT covering them 32 times over. Recent announcements highlight strong financial performance with first-quarter sales reaching JPY 197 billion and net income climbing to JPY 8 billion from JPY 3 billion last year.
- Click to explore a detailed breakdown of our findings in ARE Holdings' health report.
Examine ARE Holdings' past performance report to understand how it has performed in the past.
Nikkiso (TSE:6376)
Simply Wall St Value Rating: ★★★★★☆
Overview: Nikkiso Co., Ltd. operates globally in the industrial, aerospace, and medical sectors with a market cap of ¥222.20 billion.
Operations: The company's revenue is primarily derived from its industrial sector at ¥153.20 billion and medical sector at ¥80.65 billion.
Nikkiso, a promising player in the machinery sector, has seen its earnings surge by 144.9% over the past year, outpacing the industry average of 25.5%. The company is trading at 52% below its estimated fair value, presenting an attractive opportunity relative to peers. Despite recent share price volatility, Nikkiso's debt-to-equity ratio has improved significantly from 131.2% to 48.9% over five years and maintains a satisfactory net debt-to-equity ratio of 27.1%. With revised forecasts projecting revenue of ¥247.7 billion and operating profit of ¥19.7 billion for fiscal year-end December 2026, Nikkiso appears poised for continued growth amidst robust financial health and increased dividends per share from ¥22 to ¥30 this year.
- Dive into the specifics of Nikkiso here with our thorough health report.
Assess Nikkiso's past performance with our detailed historical performance reports.

Taking Advantage
- Dive into all 118 of the Asian Undiscovered Gems With Strong Fundamentals we have identified here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com