
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Half Year Earnings Just Shift Neurones (ENXTPA:NRO) Investment Narrative?
- Neurones reported half year 2026 sales of €454.8 million and net income of €25.9 million, compared with €424.3 million and €22.7 million a year earlier, and reaffirmed full year guidance for revenue exceeding €900 million with operating income around 9%.
- The combination of higher first half revenue and profit alongside confirmed guidance signals that Neurones currently sees its execution, cost base and client demand tracking closely with prior expectations.
- The focus now turns to what this reaffirmed full year outlook means for Neurones' broader investment narrative and earnings quality.
Scan how Neurones' reaffirmed guidance compares with peers by lining it up against list of solid balance sheet and fundamentals (194 results) that are also pushing for steady execution and disciplined profitability.
What Is Neurones' Investment Narrative?
To own Neurones, you need to believe in a fairly simple story. This is an IT services and consulting group that lives and dies by headcount productivity, day rates, and the ability to keep clients renewing multi year transformation and infrastructure work. The half year update matters here because sales of €454.8 million and net income of €25.9 million, paired with guidance for revenue above €900 million and operating income around 9%, suggest management currently sees demand, pricing and delivery costs sitting roughly where they expected.
In the short term, the key swing factors are still project pipelines in core sectors like banking, energy and the public sector, plus staffing costs in a relatively people heavy model. The reaffirmed outlook points to no obvious shock to utilisation or pricing right now. This is notable given the share price is down 11.9% year to date and earnings growth has been running in the high single digits. Capital needs remain modest for this sort of service business, so the story around Neurones is really about whether that steady execution, combined with a 3.78% dividend and a P/E that screens slightly below an estimated fair multiple, can offset slower forecast growth than the wider French market.
Even so, there is a specific operational pressure point that could unsettle that seemingly comfortable setup if ...
There's only one way to know the right time to buy, sell or hold Neurones. Head to Simply Wall St's company report for the latest analysis of Neurones's Fair Value.
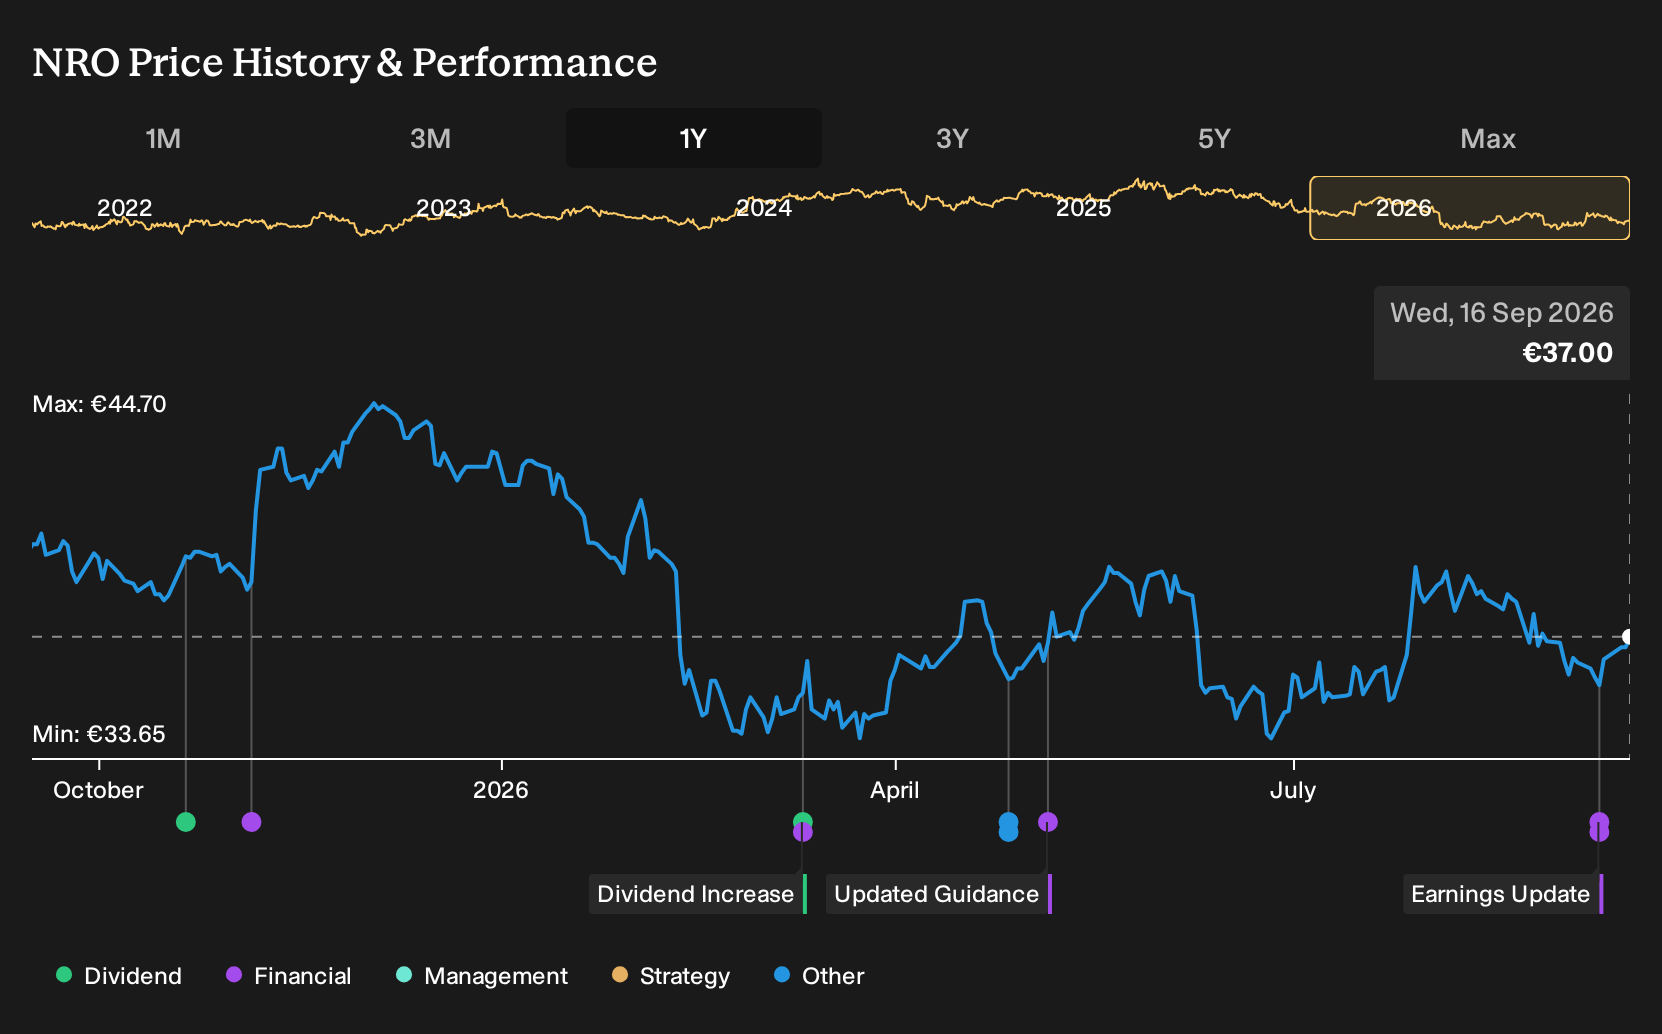
Exploring Other Perspectives
Community fair values for Neurones from the two Simply Wall St Community submissions cluster in a tight band between €41.33 and €45, yet they already show how wide opinions can run once assumptions change. Those views pre date the September 2026 earnings and guidance, so treat them as one input among several and compare them with your own expectations for future contracts, utilisation and pricing power.
Explore another Neurones fair value estimate, including one that suggests it could be worth just €41.33.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Neurones research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Neurones. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Neurones' overall financial health at a glance.
Looking For More Investment Ideas Beyond Neurones?
If Neurones is already on your radar, it can help to set it alongside other opportunities that fit clear, disciplined criteria. The Simply Wall St Screener lets you compare it with a wider set of businesses that match the kind of balance sheet strength, income profile or valuation style you prefer.
- If capital preservation sits high on your list, start with a filter focused on resilience through a 104 resilient stocks with low risk scores that may hold up better when conditions get tougher.
- Income focused investors can zero in on companies offering meaningful cash returns by scanning 161 dividend fortresses that might complement or contrast with Neurones' own payouts.
- For those hunting for fresher opportunities beyond the usual watchlists, use the screener to surface 619 high quality undiscovered gems that still show solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com