
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Grenergy Renovables (BME:GRE) A Bargain Following Strong 2026 Results?
Grenergy Renovables (BME:GRE) just posted second quarter and first half 2026 results that show a sharp step up in both sales and net income compared with a year earlier.
Despite the strong second quarter, Grenergy Renovables’ share price has been choppy, with a 30 day share price return down 3.33% and a 90 day move down 18.03%, even after a 6.13% jump on the latest earnings release.
Over a longer stretch the picture looks very different, with a 1 year total shareholder return of 32.35% and a 3 year total shareholder return of 260%. This suggests that the recent loss of momentum follows a powerful multi year run.
Spot opportunities beyond Grenergy Renovables by scanning a hand picked 189 high quality undervalued stocks that match strong fundamentals with potential for renewed momentum.For Grenergy Renovables, that sharp earnings jump sits against a share price that has cooled over recent months. Are you seeing business progress that sentiment has not fully reflected yet, or a reset in expectations as results catch up to the share price performance?
Most Popular Narrative: 31% Undervalued
On the latest numbers, the most followed narrative sees Grenergy Renovables trading at a wide discount to its implied fair value of €131.15, using an 8.84% discount rate and a €90.00 last close.
Proven model of rotating noncore and mature assets at a premium to invested capital while retaining high growth hybrid and storage platforms provides a repeatable source of capital gains and self funded CapEx. This can compress net debt to EBITDA over time and drive faster growth in net income than in top line revenue.
See why 1 investors see Grenergy Renovables as 31% undervalued.
Result: Fair Value of €131.15 (UNDERVALUED)
Still, the Grenergy Renovables story can change quickly if asset sales slow, or if large CapEx projects like Oasis of Atacama and Greenbox face costly delays.
Find out about the key risks to this Grenergy Renovables narrative.
Another View: Grenergy Renovables Looks Pricey On Earnings
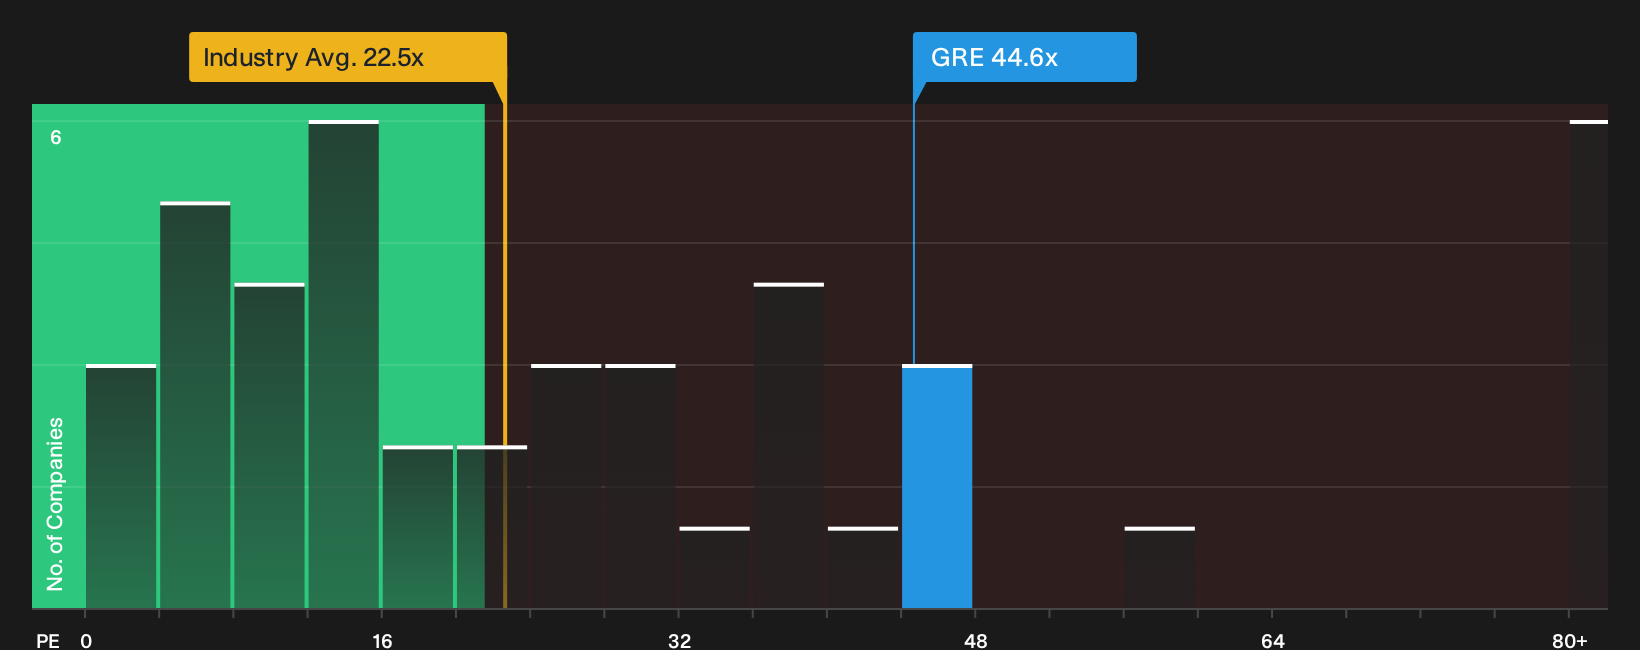
The first narrative around Grenergy Renovables leans on fair value of €131.15, yet the current P/E of 44.6x tells a different story. That ratio sits well above the European renewable energy group on 22.5x and even the fair ratio estimate of 33.6x.
In practice, that means the shares already carry a rich earnings multiple compared with peers and with where the fair ratio suggests the market could drift over time. If sentiment cools or growth assumptions ease, the valuation could move closer to those lower anchors.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Grenergy Renovables can be confusing. Move quickly, look at the full picture, and weigh both sides of the story by checking the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Grenergy Renovables?
Do not stop with one stock when the opportunity set is much wider. A few minutes with a targeted screener can surface candidates your watchlist is currently missing.
- Spot potential recovery stories early by scanning a hand picked 189 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them yet.
- Build a more resilient core by using a focused 104 resilient stocks with low risk scores that highlights companies with lower risk scores and steadier financial profiles.
- Get ahead of the crowd by reviewing a curated 619 high quality undiscovered gems that filters for quality businesses the broader market may not be paying attention to.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com