
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Aker BP Stock Could Change Following Gas Discovery
- Aker BP reported a past gas discovery at the Alpehumle prospect in the Norwegian North Sea, with early resource estimates of 1 to 15 million barrels of oil equivalent and commercial potential still under review by the licence partners.
- The broad 1 to 15 million barrel resource range and the missing hydrocarbon water contact highlight both opportunity and subsurface uncertainty for Aker BP's long term production plan.
- This article now explores how Aker BP's investment narrative interacts with the new Alpehumle gas find and its uncertain commercial scale.
Scan how Aker BP's Alpehumle find compares with other energy plays by lining up hand picked prospects from our 38 power grid technology and infrastructure stocks.
Aker BP Investment Narrative Recap
Aker BP appeals to shareholders who buy into a long project pipeline on the Norwegian Continental Shelf and a focus on digital and low emission operations. The key near term swing factor is still execution on large developments such as Yggdrasil and the performance of core hubs like Johan Sverdrup. The Alpehumle gas discovery looks incremental rather than transformative for this near term story.
The biggest operational risk remains cost overruns, delays or weaker cash generation from major projects, especially with high debt and a dividend that is not fully covered by earnings or free cash flow. Alpehumle mainly adds one more moving part on exploration, not a new central risk.
With no fresh company announcements beyond Alpehumle, the find mostly plugs into the existing exploration and near field strategy that Aker BP has talked about around its hubs. Management has already framed its long term plan around a 2b barrel opportunity set and sustaining production above 500,000 barrels per day beyond 2030.
In that context, a 1 to 15 million barrel equivalent gas accumulation is a small but potentially helpful piece if it ties back efficiently to existing infrastructure. The operational question for investors is whether the partners can progress this kind of modest discovery without straining capital, while still funding large projects, servicing debt and supporting a dividend that analysts flag as thinly covered.
Aker BP's narrative projects $13.4b revenue and $1.8b earnings by 2029. This projection is based on 4.1% yearly revenue growth and a roughly $0.4b increase in earnings from $1.4b today.
Uncover why Aker BP's fair value indicates a 12% potential downside to its current price, which leaves little room for error.
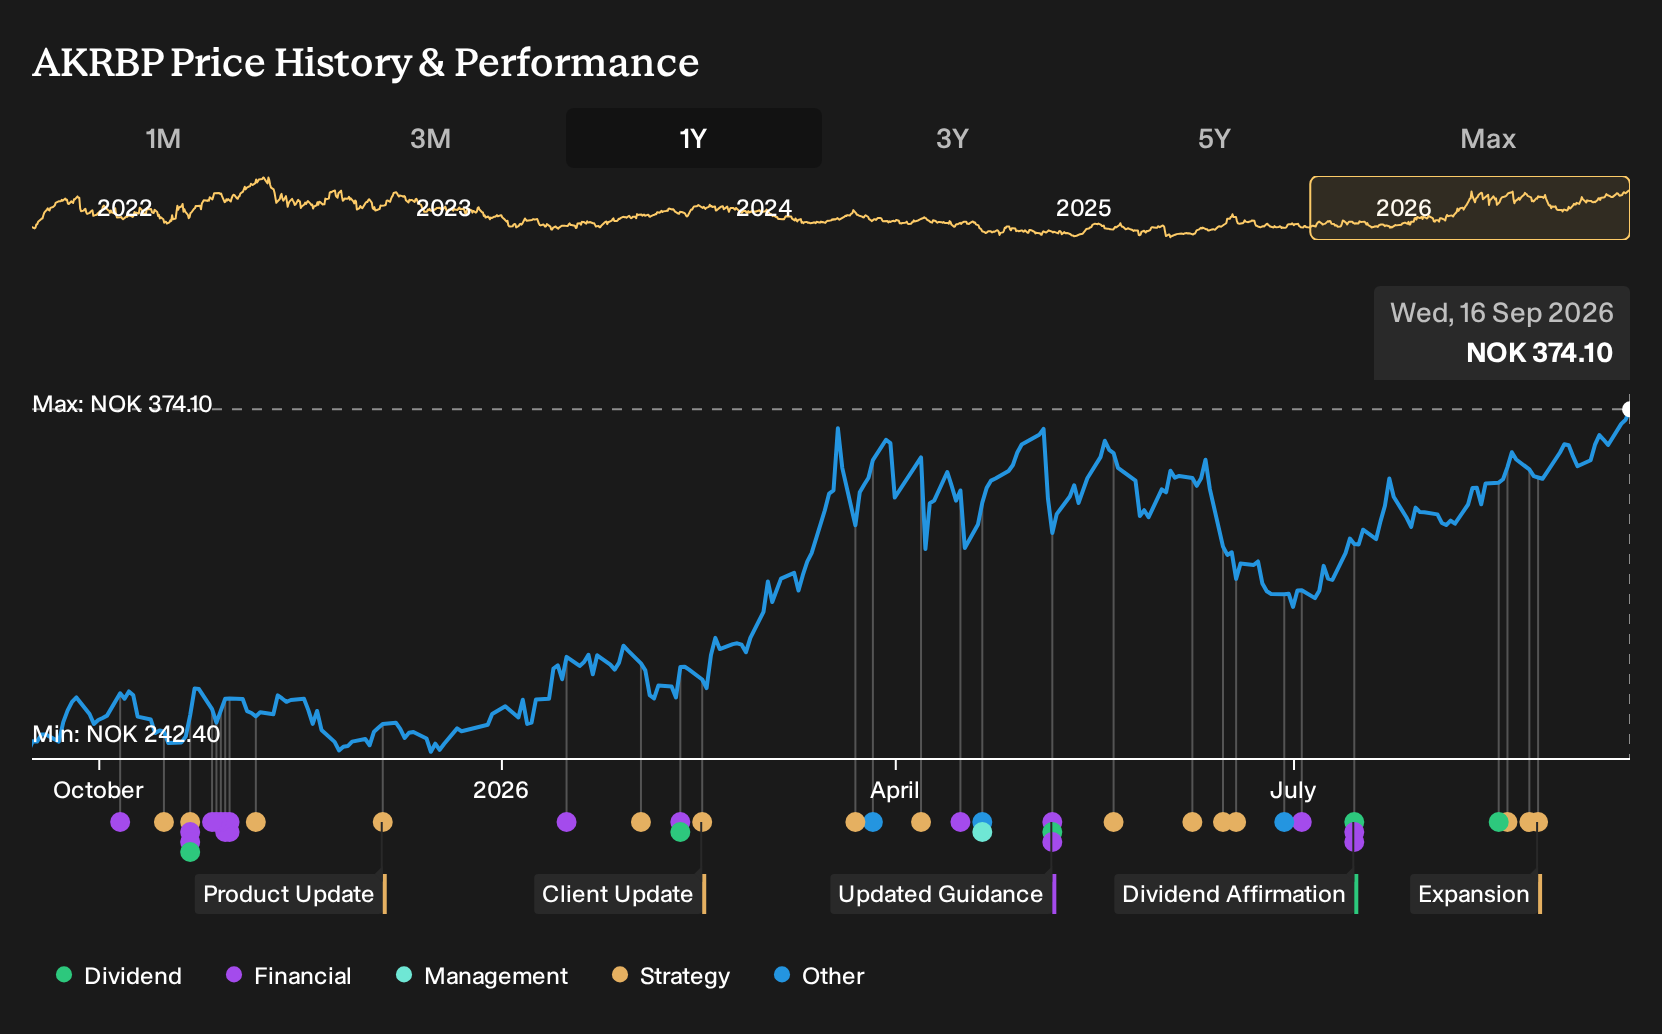
Exploring Other Perspectives
The alternate narrative focuses on demand risk for Aker BP. The most bearish analysts were only assuming roughly 2.0% annual revenue growth to about $12.6b and earnings of $1.5b by 2029 before this Alpehumle news. That is a much colder view. Use it as a reminder that opinions vary widely and may shift as new data arrives.
Explore 5 other Aker BP fair value estimates, including one that suggests as much as 36% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Aker BP research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Aker BP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aker BP's overall financial health at a glance.
Looking for more Aker BP sized investment ideas?
If the Alpehumle story has you thinking about how Aker BP fits into your broader portfolio, it can help to line it up against other businesses with different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential mispricing plus quality, scan a curated set of 189 high quality undervalued stocks that combine fundamentals with attractive valuations.
- If capital preservation comes first for you, focus on resilience by reviewing a 104 resilient stocks with low risk scores that screen well on balance sheet strength and volatility measures.
- Those hunting for ideas off the beaten path can widen their opportunity set through a 619 high quality undiscovered gems that still show strong underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com