
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Astera Labs Stock Gets New AI Memory Products For Cloud Servers
- Astera Labs announced three new Leo memory connectivity solutions, including the Leo X-Series and Leo 2 E & P-Series, aimed at AI accelerators and cloud servers by addressing KV cache access, CXL 3.2 expansion, and rack-scale memory pooling.
- The product family leans into DDR4 reuse, pooled CXL memory, and COSMOS-backed telemetry to increase useful capacity and extend the lifetime of existing DRAM across AI and general cloud workloads.
- The focus now shifts to how Astera Labs' expanded Leo Smart Memory Controller lineup, especially fabric-attached KV cache, could reshape its investment narrative.
Astera Labs Investment Narrative Recap
To own Astera Labs, you need to believe its role in AI and cloud connectivity can stay essential as hyperscalers scale out GPUs, memory tiers, and open fabrics. In the near term, the story leans on ramping Scorpio switches and Leo controllers into larger rack deployments. The main short-term catalyst is execution on those ramps with key cloud customers.
The biggest risk is that hyperscaler AI capex, standards choices, or in-house silicon reduce the need for Astera Labs products, especially given customer concentration and a rich P/E multiple. The Leo news looks directionally helpful for the operating story but does not fundamentally change that risk-reward balance right now.
The most relevant update here is the launch of the Leo X Series fabric-attached Smart Memory Controller alongside the refreshed Leo 2 E and P Series. This extends Astera Labs deeper into GPU-side memory and rack-level CXL pooling, tying directly into the same customers that are evaluating Scorpio X Series switches and broader AI fabrics.
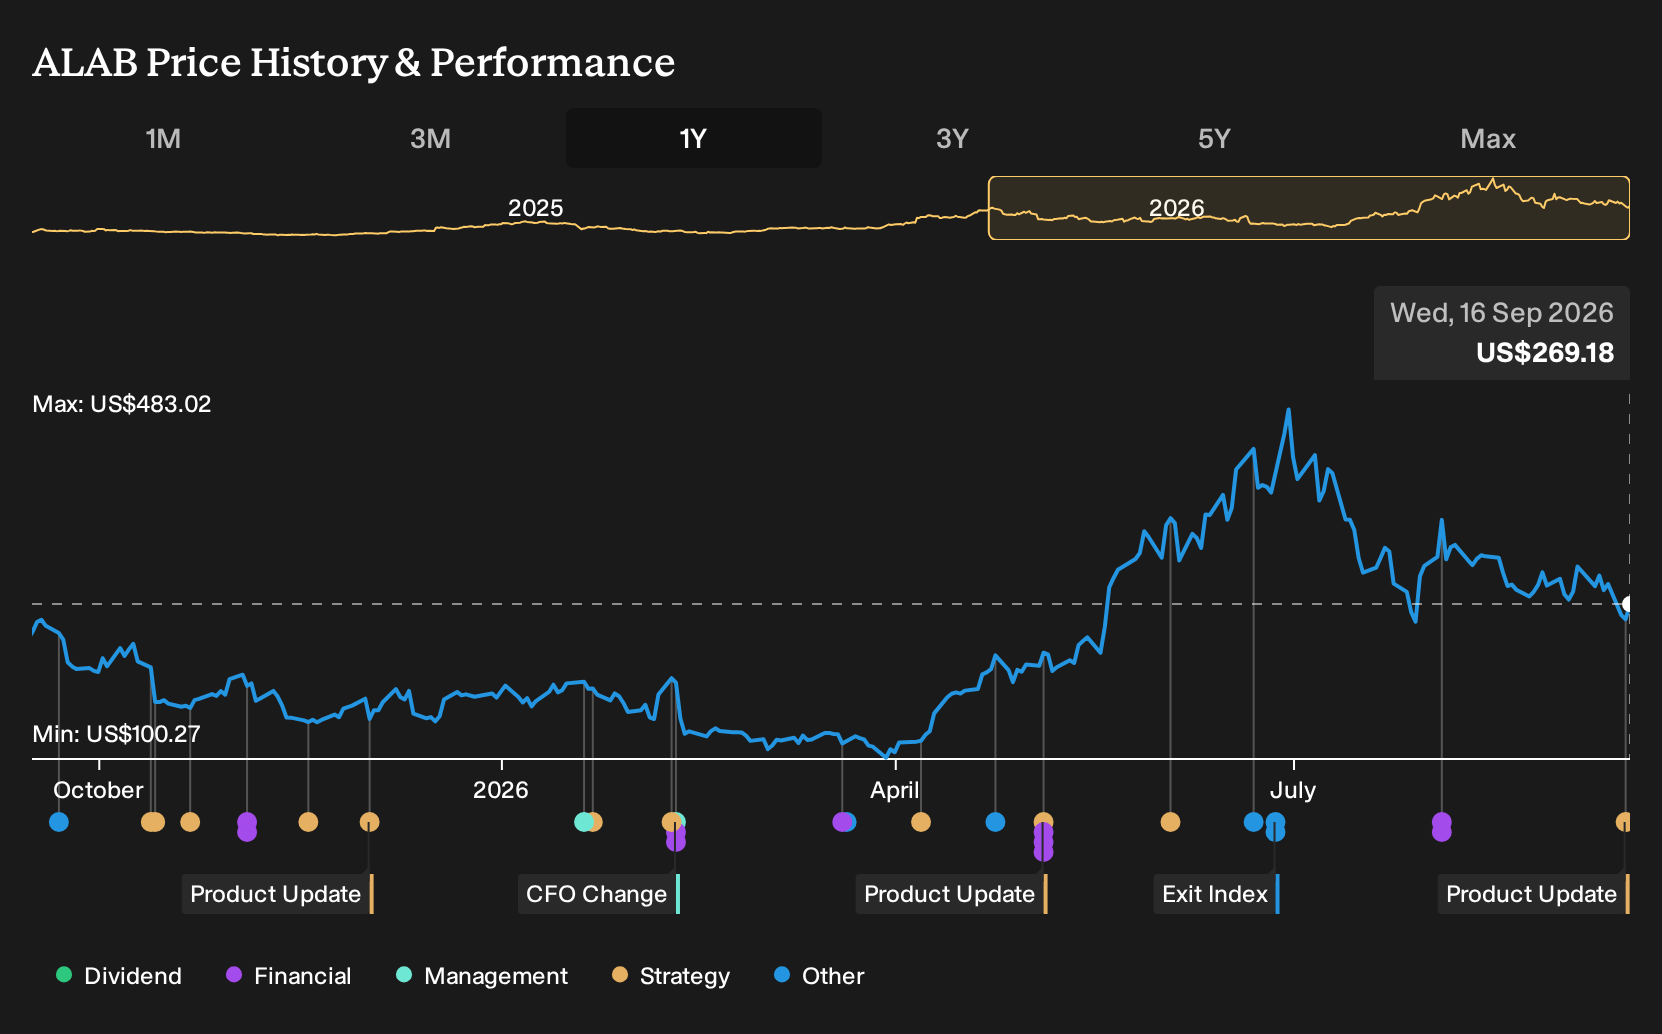
For you, the key question is whether Astera Labs can convert this broader Leo portfolio into higher attach rates per accelerator cluster before rivals and in-house solutions close the gap. Execution risk remains, especially with a concentrated buyer base and volatile share price, but successful Leo adoption would support the existing catalysts around AI rack deployments.
Astera Labs' current analyst narrative points to revenues of US$3.8b and earnings of US$1.1b by 2029, based on assumed revenue growth of 46.3% per year and an earnings increase of about US$730m from US$369.5m today.
Discover how Astera Labs' fair value indicates a 46% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative angle to watch is the more cautious take on Astera Labs’ earnings power. The lowest analysts were modelling only about US$3.3b of revenue and US$707.7m of earnings by 2029, well below the US$3.8b and US$1.1b consensus figures. Those forecasts and the new Leo launch have not met yet, so views may shift.
Explore 9 other Astera Labs fair value estimates, including one that indicates there could be as much as 17% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Astera Labs research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Astera Labs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astera Labs' overall financial health at a glance.
Looking For More Investment Ideas Beyond Astera Labs?
If the Astera Labs story has you thinking about how AI infrastructure fits in your portfolio, it can help to line it up against other opportunities that share similar qualities or offer a different risk profile. The Simply Wall St Screener is built for exactly that kind of comparison so you can move from one ticker to a shortlist of candidates that fit your style.
- For investors hunting for quality at a reasonable price, shortlist companies using the 33 high quality undervalued stocks that combine strong fundamentals with potentially attractive pricing.
- If capital preservation and steadier profiles matter more to you, filter for businesses with robust metrics and fewer red flags through the 11 resilient stocks with low risk scores to see which ones match your comfort level.
- When you want ideas that are not yet crowded but still underpinned by solid numbers, scan the 16 high quality undiscovered gems and find candidates that the wider market may not be focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com