
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 U.S. Import Dependent Stocks With Upside If Tariffs Ease
Tariff policy is back under the spotlight, and this time a court ruling on Section 301 duties could reshape the cost base for large import‑heavy businesses. That kind of legal reset can create winners and leave others standing still, which is why traders are watching closely. This article walks through three stocks exposed to that tariff story and explains how the same headline can signal opportunity or caution for your portfolio.
The three stocks below are just a starting sample, and the full screen surfaced 30 more large import dependent manufacturers and retailers with equally compelling stories that are not covered here. To identify and analyze the highest conviction tariff plays in this space, head straight into the U.S. Large-Cap Import-Dependent Manufacturers and Retailers screener.
Tennant (TNC)
Tennant fits directly into the tariff story running through this screener, because it builds floor cleaning machines that depend on imported components. Its main interest for investors, however, is how that global supply chain supports a growing automation-led services model.
Tennant designs and sells equipment used in maintaining nonresidential surfaces, generating about US$1.2b from this segment, and carries a market value near US$1.2b. That tight focus links its fortunes directly to input costs, including any shifts in tariff policy.
"Accelerated adoption of autonomous mobile robots (AMRs) and equipment-as-a-service programs is expanding Tennant's recurring revenue base, supported by robust customer demand amid labor shortages and higher labor costs, which the company expects to influence both revenue and margins."
The real swing factor for Tennant now is how one unseen pressure on its cost base resolves and filters through to profitability.
If that pressure resolves in Tennant's favor, read the full narrative for Tennant to see how tariffs, automation and recurring services could be quietly reshaping its profile.
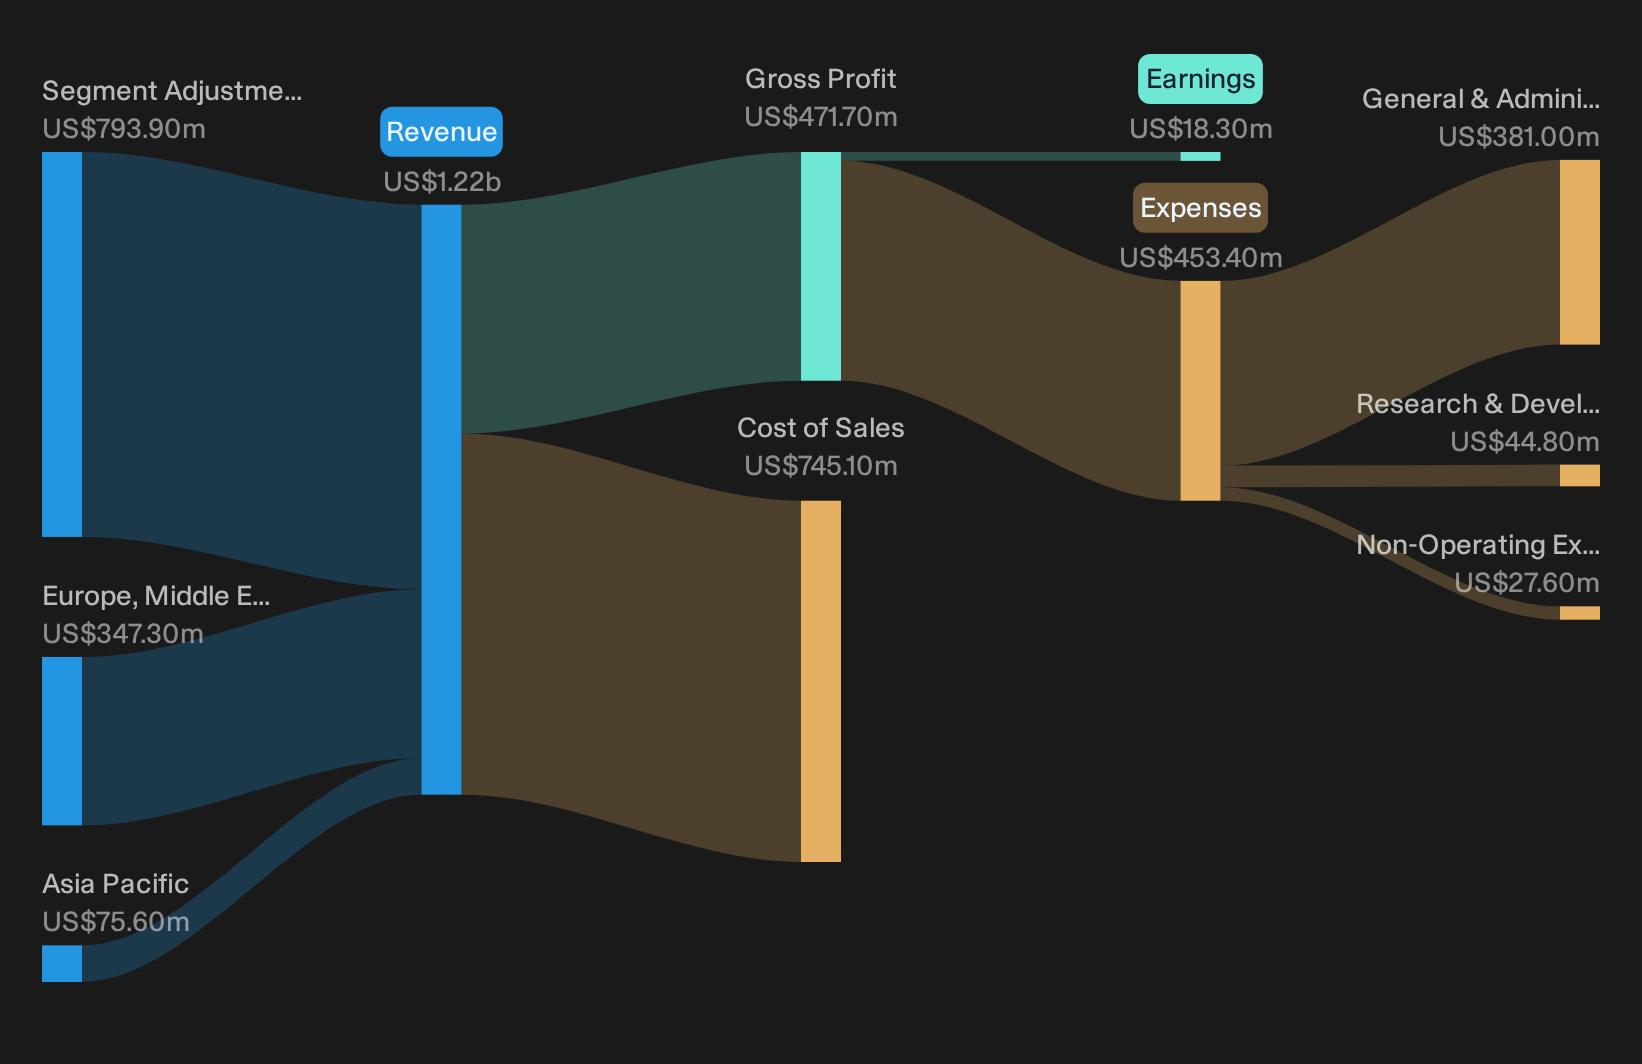
Hyster-Yale (HY)
Hyster-Yale fits clearly within the import-heavy manufacturing theme, since its lift trucks and attachments depend on components sourced worldwide. As a result, any broad tariff reset could meaningfully change how its automation and clean energy pivot appears in future results.
Hyster-Yale, Inc. supplies lift trucks, parts, fleet services, and energy solutions worldwide, with most of its US$3.5b revenue coming from the Americas lift truck division at about US$2.6b, plus roughly US$548 million from EMEA, US$164 million from JAPIC, and US$327 million from Bolzoni, supported by a market value near US$599 million.
"Hyster-Yale is accelerating realignment and investment in automation, advanced warehouse technology, and clean energy solutions (through Nuvera and modular vehicle designs). This is positioning the company to participate in industry-wide digital supply chain and sustainability trends, with the potential to influence future revenue and margin performance."
What happens to Hyster-Yale's margins if a single pressure point in its tariff-exposed supply chain shifts direction?
If that margin swing is what you care about, read the full narrative for Hyster-Yale to see how tariffs, automation and energy bets could be quietly decoupling headline risk from long term earnings power.

Generac Holdings (GNRC)
Generac Holdings plugs directly into the import dependent theme because its generators and energy hardware rely on overseas components, yet the real interest today is how that supply chain meets a surge in power demand from AI driven data centers.
"Accelerating demand for backup power solutions in data centers driven by AI adoption and global digitalization has resulted in a structural supply deficit for large commercial generators; Generac's rapid entry and greater than $150 million backlog position it to capture significant revenue growth and operating leverage over the next several years."
What happens to Generac Holdings' earnings power if one major pressure point in its imported parts bill quietly shifts direction.
Generac Holdings develops and sells backup power and smart home energy gear worldwide, fitting the import heavy manufacturing theme, with about US$3.6b of sales from the United States and US$870 million from international buyers, and a market value near US$10.3b.
That tariff release valve on imported parts is exactly where the story could get interesting, so read the full narrative for Generac Holdings for how Generac Holdings' AI power push might be underappreciated.

Curious About High Conviction Alternatives
Fresh ideas move first. While the market waits, some themes quietly build breakout momentum under the radar for now. Do not get caught reacting late; consider positioning earlier instead.
- Spot early breakouts in quality companies before momentum fades by running a focused search through the 33 high quality undervalued stocks.
- Track cash-generating AI leaders that are already past the hype stage and still building business strength through the curated 75 profitable AI stocks that aren't just burning cash.
- Target resilient cash flow compounds that prioritize stability while others chase headlines by scanning the carefully filtered 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com