
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Yum! Brands (YUM)'s Pizza Hut Sale Means For Shareholders
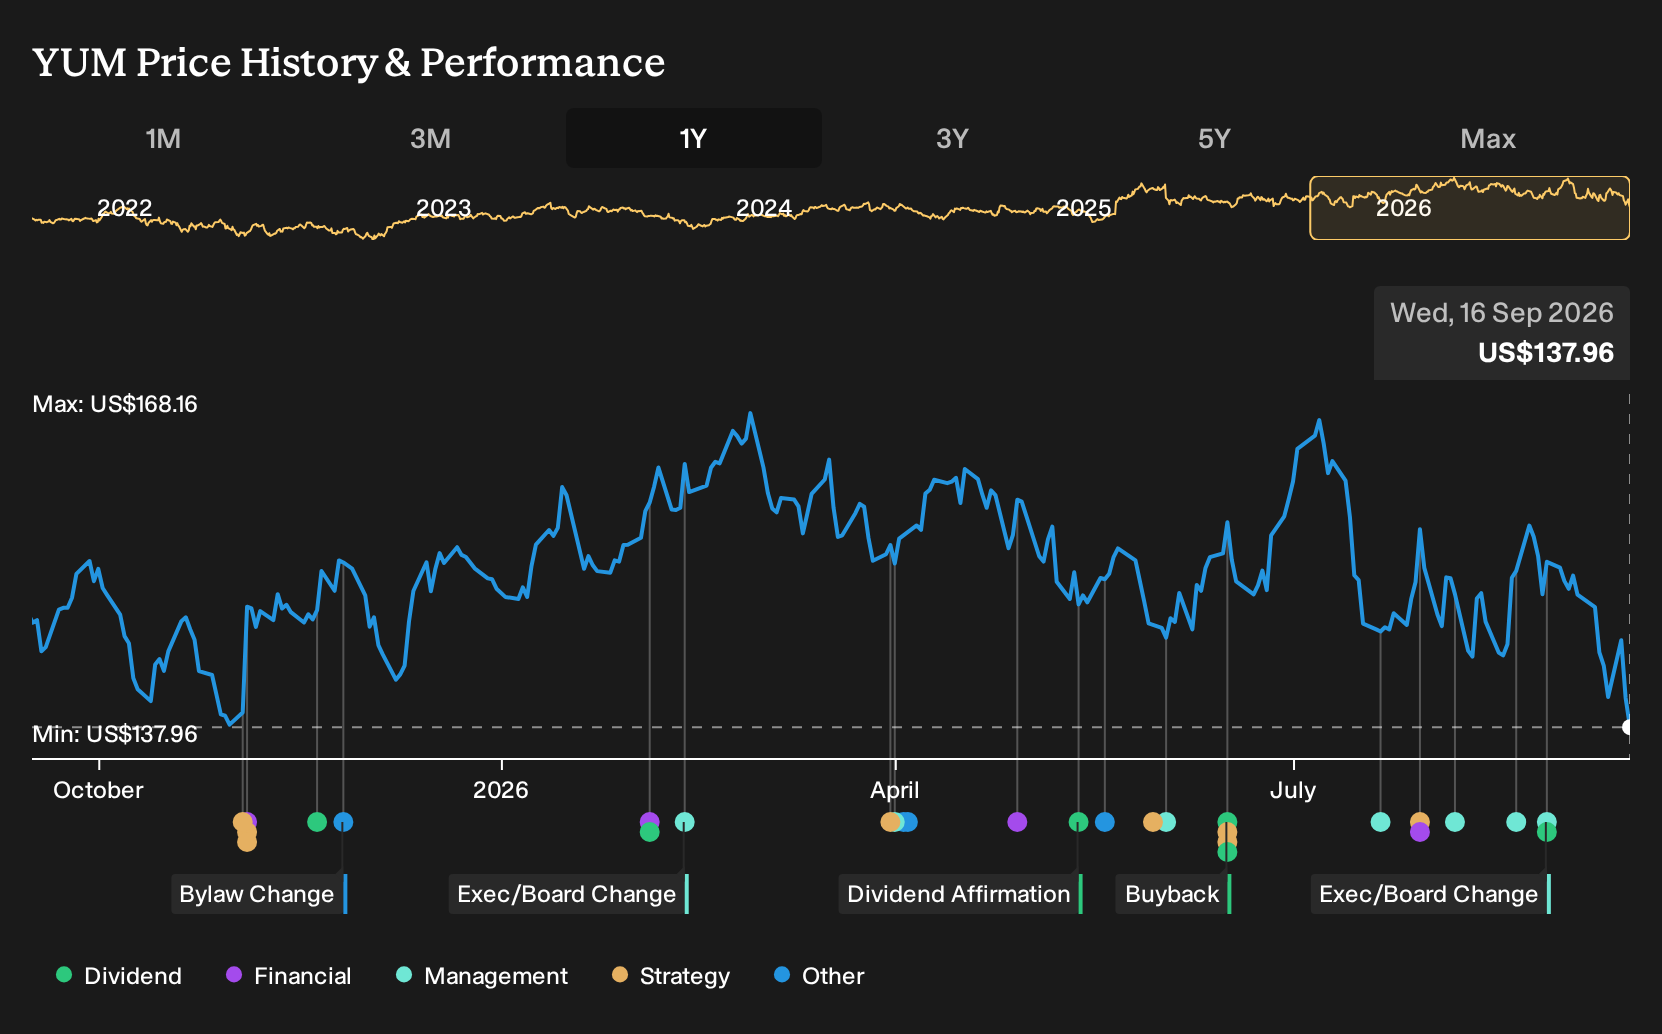
- Yum! Brands recently reshaped its portfolio by selling its Pizza Hut business outside Mainland China, transferring China Pizza Hut operations to Yum China Holdings, and concentrating resources on Taco Bell, KFC, and Habit Burger & Grill, supported by a larger shared headquarters and technology infrastructure.
- This pivot toward a tighter set of franchises, backed by the Byte technology rollout and a deeper supplier partnership with Welbilt, highlights management’s focus on operational efficiency, brand execution, and potential future brand additions instead of maintaining a broader but less focused restaurant mix.
- We will now assess how Yum! Brands’ decision to sell Pizza Hut and refocus on Taco Bell and KFC could reshape its investment narrative.
See how Yum! Brands' portfolio reshuffle compares with other potential compounders by checking out a curated set of 16 high quality undiscovered gems in similar consumer-facing sectors.
Yum! Brands Investment Narrative Recap
For Yum! Brands, you essentially have to believe the tighter focus on Taco Bell, KFC and Habit Burger can offset industry headwinds and past pressure on the earnings outlook. The near term swing factor is execution on digital ordering, new headquarters scale and franchise health. The Pizza Hut exit simplifies the story but does not remove demand risk or cost inflation.
The biggest risk remains a mix of softer consumer spending in key markets and Yum!'s leveraged balance sheet, including debt that is not well covered by operating cash flow and negative shareholders' equity. Recent downward earnings revisions and a Zacks Rank #5 label frame sentiment, but the real test is whether franchisees convert tech and menu initiatives into steady same store sales.
The clearest recent marker to watch is Yum! Brands’ September 9 appearance at the Barclays Global Consumer Staples Conference in Boston. That forum gives management a chance to lay out how the Pizza Hut sale, the Byte technology rollout and the combined Taco Bell and Habit Burger headquarters translate into near term priorities for capital allocation and store level returns.
For catalysts, investors will likely listen for details on digital order penetration, planned international KFC and Taco Bell expansion and any quantification of cost efficiencies from the Welbilt partnership and new Irvine hub. With Yum!'s earnings forecast to decline over the next three years, clear commentary on cash generation, leverage, and franchisee economics may matter at least as much as long term unit growth targets.
Yum! Brands’ current analyst narrative points to revenues of $10.4b and earnings of $2.2b by 2029, based on a 6.9% yearly revenue growth rate and a move from $1.7b in earnings today, which implies an earnings increase of about $0.5b from current levels.
Uncover why Yum! Brands' fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community presents four fair value estimates for Yum! Brands that range from about US$172.89 to US$206.13 per share, with opinions clustered across ten tight buckets. That spread sits alongside the upcoming Barclays conference appearance and the Byte rollout, which could reset expectations. Investor views clearly differ, so explore several competing takes before forming your own.
Explore 3 other Yum! Brands fair value estimates, including one that suggests as much as 49% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Yum! Brands research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Yum! Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yum! Brands' overall financial health at a glance.
Looking For More Ideas Beyond Yum! Brands?
Once you have a view on Yum! Brands, it helps to widen the lens and compare it with other businesses that fit clear themes on quality, value, and resilience. The Simply Wall St Screener can surface those candidates quickly so you can spend more time judging the stories behind the numbers.
- If your focus is long term value, consider using our screen of 33 high quality undervalued stocks that combine strong fundamentals with pricing that may not fully reflect them yet.
- Income oriented investors can filter for steady payers by reviewing a curated set of 6 dividend fortresses that aim to balance yield with balance sheet strength.
- For a focus on capital preservation and a potentially smoother ride, you can work through a 11 resilient stocks with low risk scores that score well on financial health and risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com