
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Verisk Analytics (VRSK) Launches Fraud Discovery, Is The Stock Expensive?
Verisk Analytics (VRSK) has rolled out Verisk Fraud Discovery, a modular platform that brings together fraud intelligence, analytics and digital media forensics to give insurers new tools to tackle increasingly complex fraud schemes.
Recent product launches such as Verisk Fraud Discovery and the U.S. Data Center Exposure Database arrive at a time when Verisk Analytics’ share price, now at US$181.75, has seen short term momentum with a 90 day share price return of 4.57%. However, longer term total shareholder returns over 1, 3 and 5 years remain in decline, suggesting recent enthusiasm is only partly offsetting a tougher multiyear experience for investors.
Surf 16 high quality undiscovered gems where fraud analytics, data infrastructure and risk intelligence specialists like Verisk Analytics are shaping how insurers respond to complex claims patterns.Short term momentum has nudged Verisk Analytics higher, while longer term holders are still nursing weaker total returns. Does it make more sense to commit at US$181.75 today, or to wait for a different entry point as valuation comes into focus next?
Most Popular Narrative: 136.5% Overvalued
Verisk Analytics last closed at $181.75 while the most followed narrative on the stock, according to Esteban, pegs fair value at $76.85 using a 7.73% discount rate. That gap frames Verisk Analytics less as a growth story at any price and more as a regulated utility style asset where the entry point matters.
Verisk Analytics is a regulatory-grade data toll on the US property & casualty insurance industry, monetized through ~83% subscription revenue with ~92% client retention. VRSK's narrow-moat franchise produces FCF with an unusually high degree of predictability, durable enough to justify a 15× exit multiple at a 35% margin of safety. The 2022 to 2025 portfolio simplification (Energy, Argus, 3E, Marketing Solutions all divested) has produced a cleaner pure-play with structurally higher margins (Adj EBITDA 56.2% in 2025 vs. 53.5% in 2023) and a shrinking share count (~19% reduction since 2019). What the investor is paying for here is a regulatory annuity with an embedded MSD price-and-volume escalator, and walking away from any thesis premised on this becoming a HSD-to-DD revenue compounder.
See why 7 investors see Verisk Analytics as 136% overvalued.
Result: Fair Value of $76.85 (OVERVALUED)
Still, Verisk Analytics faces pressure if subscription clients reassess budgets or regulators alter how insurers use third party data, which could weaken that toll road narrative.
Find out about the key risks to this Verisk Analytics narrative.
Another View On Verisk Analytics’ Valuation
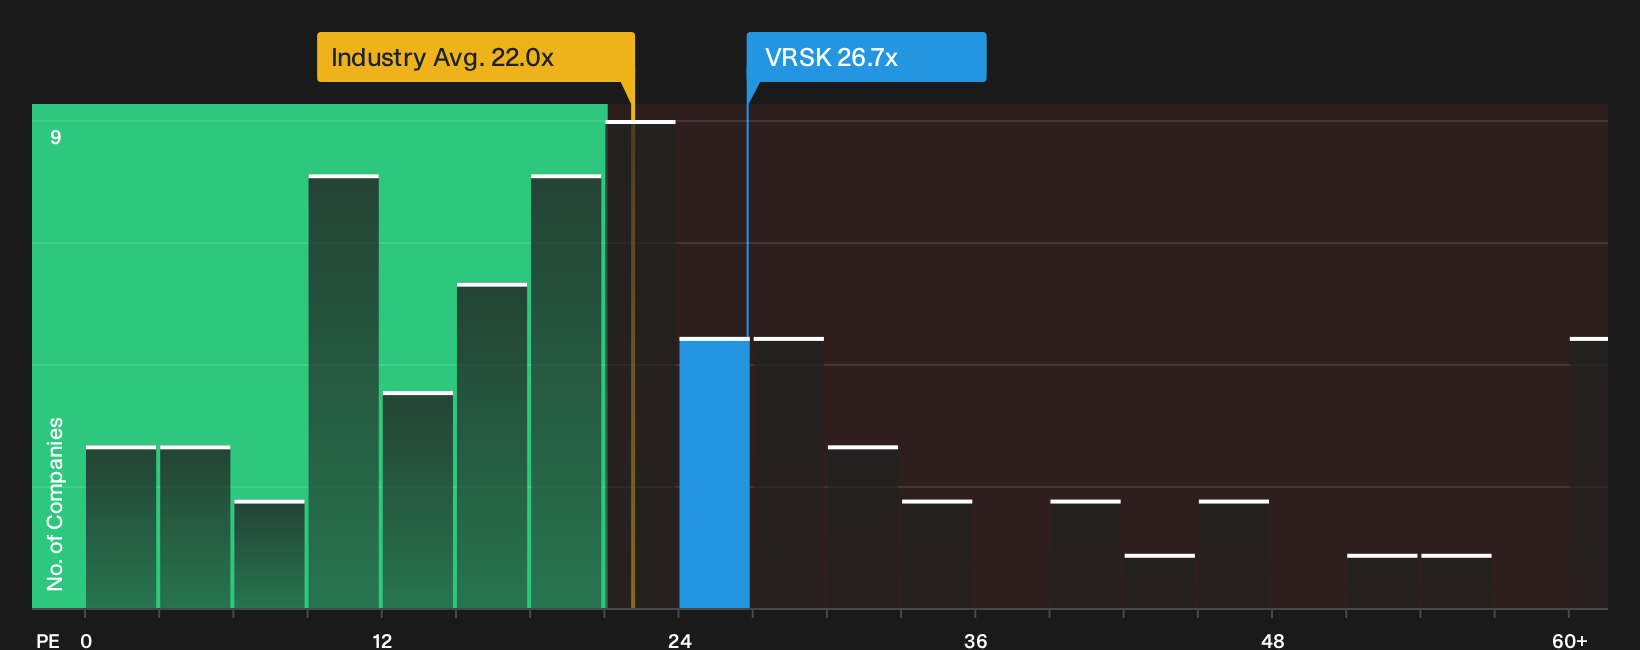
Esteban’s narrative flags Verisk Analytics as heavily overvalued at $181.75 versus a fair value of $76.85. Our preferred P/E check presents a different angle. The stock trades on 26.7x earnings, slightly below peers at 28x, yet above a fair ratio of 24.3x. That spread points to a modest valuation premium rather than an extreme disconnect. Which signal should carry more weight for you right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Verisk Analytics so far. If you want to move fast and build your own take on the debate, start with the full picture of 3 key rewards and 1 important warning sign.
Looking for more Verisk Analytics style ideas?
If Verisk Analytics has sharpened your focus on quality, do not stop here. Broader opportunity sits just beyond this ticker and you will want to see it.
- Target resilient cash flows by scanning companies that look undervalued on fundamentals using the Simply Wall St screener for 33 high quality undervalued stocks.
- Build a watchlist around income by zeroing in on businesses with sturdy payout profiles through the screener highlighting 6 dividend fortresses.
- Prioritise capital preservation first and hunt for steady performers with the screener tuned to 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com