
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Earnings Beat Change HNI (HNI) Narrative
- HNI recently reported a strong quarter, with revenue in line with analyst expectations and earnings per share above estimates following its 2023 Kimball International acquisition.
- The latest numbers highlight how the Kimball International integration has translated into the fastest revenue expansion in HNI's peer group, which points to meaningful execution progress on the deal rationale.
- We will now explore how HNI's earnings beat and post acquisition growth momentum could reshape the broader investment narrative for the business.
Scan how HNI's acquisition driven surge compares with other furniture and commercial interiors players by reviewing our hand picked list of solid balance sheet and fundamentals (22 results).
HNI Investment Narrative Recap
For HNI to make sense in a portfolio, you need to be comfortable with a furniture and building products group that is leaning heavily on execution rather than a booming end market. The recent earnings beat and fastest peer group revenue expansion support the idea that Kimball International synergies and Mexico efficiencies are starting to show through. The near term catalyst is continued proof that this integration can translate into cleaner margins and steadier earnings.
The biggest risk remains that much of the operation still leans on pricing and project timing in markets facing hybrid work and housing headwinds. Weak operating cash flow coverage of debt and a dividend that is not fully supported by earnings add another layer of pressure. This quarter’s strength is helpful for sentiment, but it does not remove those financing and demand questions.
In the absence of fresh company announcements tied directly to this quarter, the previously flagged efficiency program around KII synergy capture and the Mexico ramp is the most relevant context. Management has framed these projects as key levers for earnings, with analysts expecting them to contribute meaningfully to profit improvement over the next few years.
The latest set of results gives you a live test of that story. Revenue growth following the Kimball deal and an EPS beat suggest HNI is executing against those internal initiatives, even while headline net margins remain thin and were reported lower than a year ago. For you as an investor, the question is whether this operational progress looks durable enough to offset exposure to hybrid work trends, housing sensitivity and tariff risk in hospitality over your time horizon.
HNI's narrative projects forecast revenue of US$7.7b and earnings of US$595.5 million by 2029. This projection corresponds to annual revenue growth of 29.1% and an increase in earnings of about US$594.5 million from current earnings of US$1.0 million.
Uncover why HNI's fair value indicates a 49% potential upside to its current price that could narrow quickly.
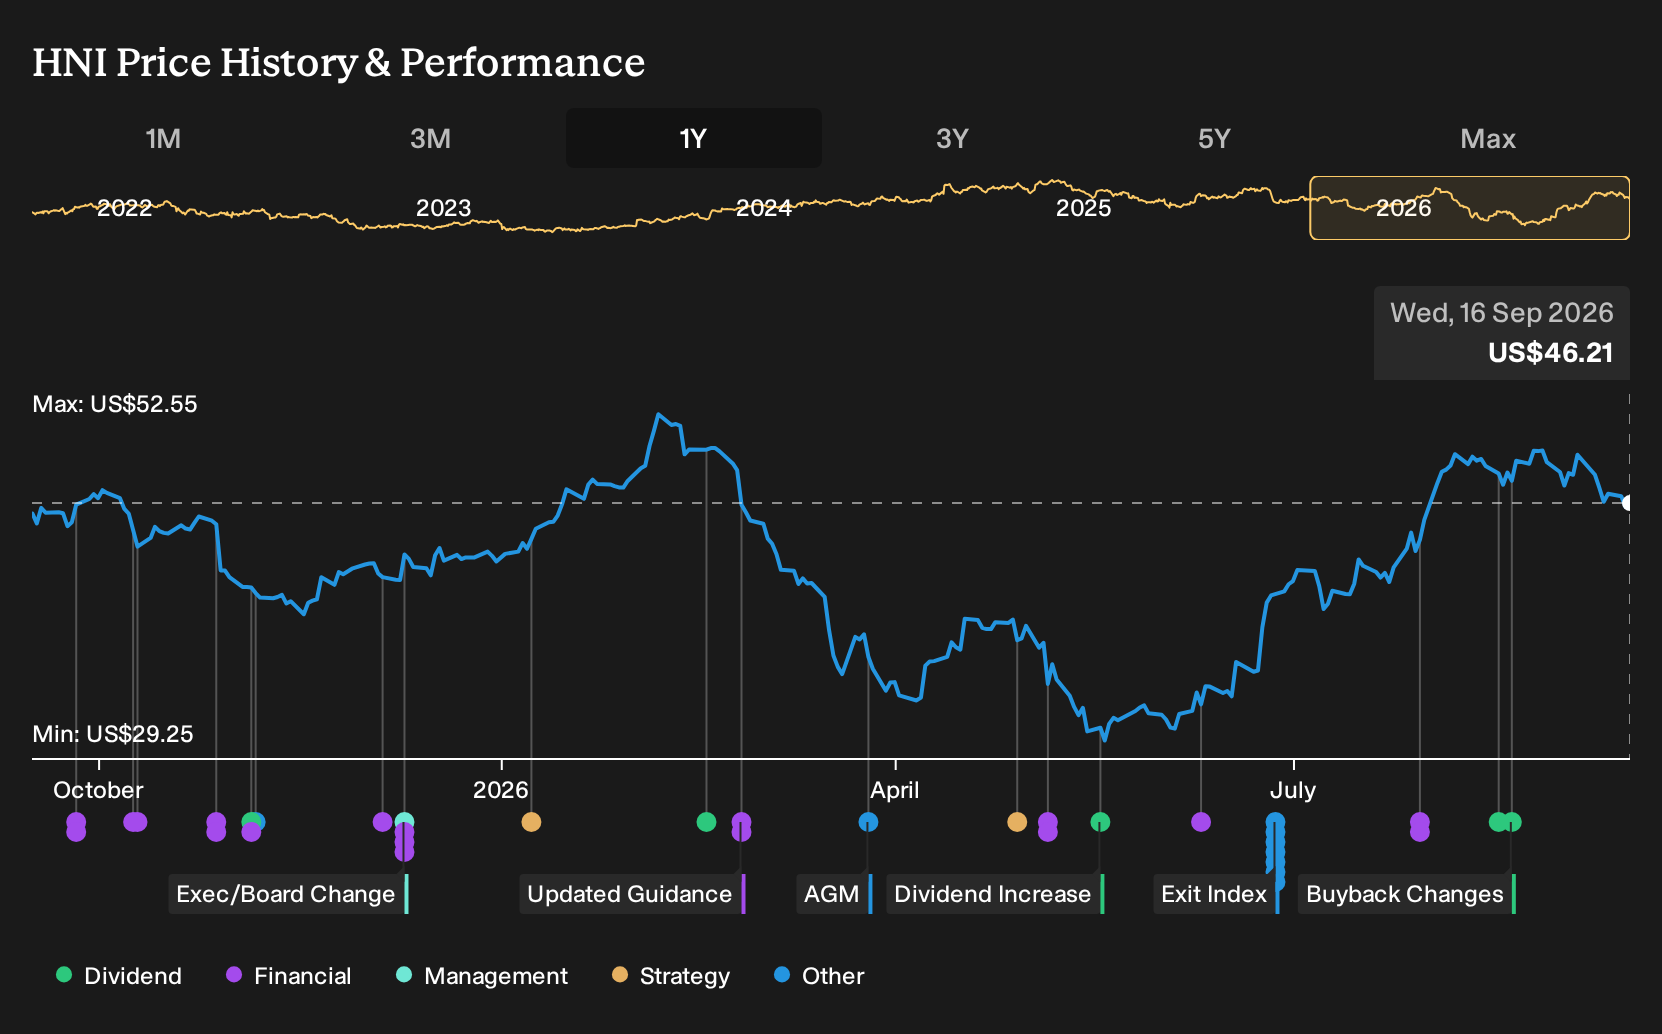
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span from US$69 to about US$488, so some HNI shareholders see modest upside while others pencil in very high potential. Those views sit alongside unresolved questions about hybrid work, housing pressure, and tariff exposure, so you should compare several perspectives before leaning on any single narrative.
Explore 2 other HNI fair value estimates, including one that suggests as much as 958% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your HNI research is our analysis highlighting 4 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for HNI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HNI's overall financial health at a glance.
Looking For More HNI Investment Ideas Beyond This Stock?
Once you have a handle on HNI, it can be useful to line it up against other opportunities using the Simply Wall St Screener. You can filter for different types of businesses, compare fundamentals quickly, and spot ideas that fit the risk and return profile you actually want.
- If you want resilient balance sheets and solid fundamentals to sit alongside HNI in your portfolio, check out our list of solid balance sheet and fundamentals (22 results) for companies that might better match your comfort with financial strength.
- For investors hunting for quality at a reasonable entry point rather than chasing hype, scan the 33 high quality undervalued stocks to see which stocks combine fundamentals and pricing that currently look more appealing.
- If income is a key part of your plan and you want potential complements to HNI on the yield side, take a look at the 6 dividend fortresses to find higher yielding companies with a focus on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com