
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Fidelity National Information Services (FIS) Trading At A Discount To Earnings?
Fidelity National Information Services has seen its share price fall sharply in recent years, which puts the focus squarely on what investors are paying for its earnings today. With the stock under pressure and the business pushing deeper into core banking technology, the live question is whether the current valuation is still in step with the profit engine behind it.
- Over the past 5 years the share price has declined 65.5%, which raises the issue of how much earnings power the market now believes Fidelity National Information Services can deliver.
- Record wins in core banking contracts, including a deal to support a newly formed U.S. bank valued at over US$100b, may support expectations for more durable earnings as clients upgrade and consolidate their technology platforms.
- The analysts covering Fidelity National Information Services have run their own numbers. See what analysts think Fidelity National Information Services's shares could be worth.
The issue now is whether Fidelity National Information Services' current share price is justified by the earnings that investors can reasonably expect from the business.
To compare Fidelity National Information Services with other potential ideas on your watchlist, a focused screen of 33 high quality undervalued stocks can be a useful next step in your research.
Is Fidelity National Information Services a Bargain on Earnings?
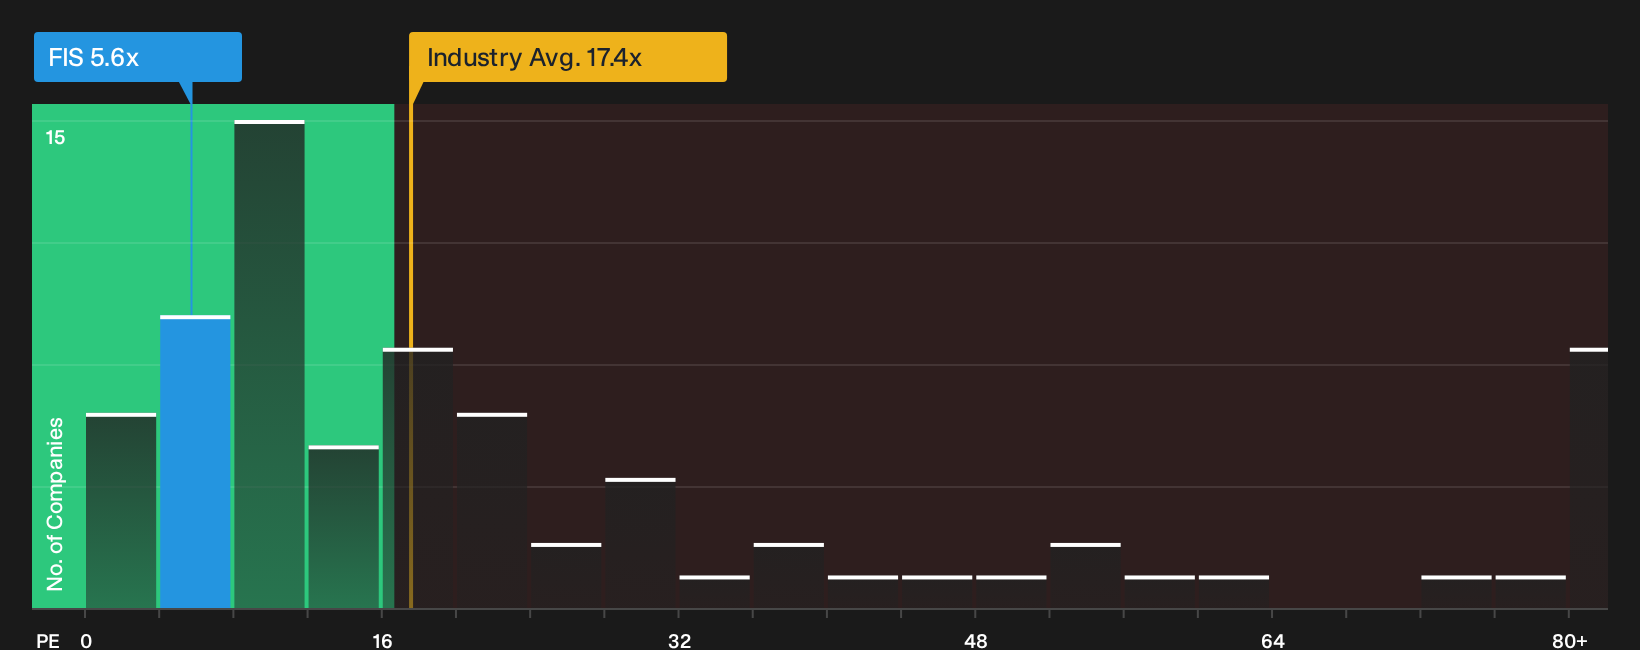
For a mature payments and banking-technology specialist like Fidelity National Information Services, the P/E ratio is a direct way to see what you are paying for each dollar of profit. The stock currently trades on about 5.6x earnings, which is far below the diversified financial industry average of roughly 17.4x and well under the peer group near 29.0x.
Because the P/E that might be expected for Fidelity National Information Services, based on its economics and risk profile, screens above the current figure, this model points to the shares as undervalued on this metric. Record wins in core banking, including the contract tied to a U.S. bank valued at over US$100b, arrive against a backdrop where the market is still pricing the earnings stream at a marked discount to sector norms. That combination suggests the P/E gap is worth investigating further as part of a broader assessment of the business. Explore the numbers behind Fidelity National Information Services's P/E valuation.
The Fidelity National Information Services Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Fidelity National Information Services leaves off. They spell out which growth, margin and earnings paths would need to play out for the stock to be worth meaningfully more or less than the current market price on the Community page. Each scenario links a fair value estimate to a specific mix of potential catalysts and risks so you can track over time which version of Fidelity National Information Services' future appears to be taking shape.
One of the top community narratives on Fidelity National Information Services: roughly fairly valued
"The business is leaning heavily into AI, data infrastructure and digital banking capabilities..."
Discover why this Narrative puts Fidelity National Information Services at roughly fairly valued.
One more factor to weigh before acting on Fidelity National Information Services' valuation
The numbers only tell part of the story, because the people setting priorities and their pay structure can shape how faithfully those profits are pursued or protected over time. See who runs Fidelity National Information Services and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com