
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ezaki Glico (TSE:2206) Could Be 46% Below Fair Value On Its Wellness Push
Viome Life Sciences and Ezaki Glico (TSE:2206) have launched mRNA HEALTH TRACKER®, billed as Japan’s first gut bacteria mRNA based personalized health service, tying the confectioner more directly to data driven wellness offerings.
Ezaki Glico’s tie up with Viome lands at a time when the 1 year total shareholder return is slightly down 1.2%, while the 3 year total shareholder return is up 30.1%. This suggests that longer term holders have seen stronger momentum than those focused on recent share price moves.
Capitalize on Ezaki Glico's push into data driven wellness by scanning a curated set of health focused consumer and nutrition plays in our 74 high quality undiscovered gems.Ezaki Glico now trades well below one valuation model yet above the average analyst target after a soft recent share price patch. Is that a bargain in the making or a warning worth heeding as you weigh the numbers next?
Preferred P/E of 48.4x for Ezaki Glico: Is it justified?
On one side of the ledger, Ezaki Glico is trading at ¥5,018 against an internal fair value estimate of ¥9,332.28 based on the SWS DCF model. On the other, the stock carries a P/E of 48.4x, which is described as expensive when stacked up against both peers and its own fair P/E benchmark.
The P/E ratio compares what investors are paying today for each unit of current earnings. For a consumer foods and health products group like Ezaki Glico, a higher P/E often reflects expectations that profits can grow faster than the broader market or that earnings are temporarily depressed and could rebound.
Forecasts point to earnings growing 23.68% per year, which is described as significantly faster than the JP market at 8.8%. That kind of earnings profile can help explain why the share price supports a 48.4x P/E, even with recent pressure on margins, a 1.7% net profit margin that is lower than last year's 2.4%, and a low 2.3% return on equity.
Relative to the JP Food industry P/E average of 17.3x, Ezaki Glico trades at a far richer multiple. It is also described as expensive versus an estimated fair P/E of 28.9x, which signals a level that the market could move toward if enthusiasm around future profits cools or if earnings do not track the forecasted pace.
Explore the SWS fair ratio for Ezaki Glico.
Result: Price-to-earnings of 48.4x (OVERVALUED)
Still, any slip in execution on health focused products, or a sharper pullback from that 48.4x P/E, could quickly challenge the Ezaki Glico story.
Find out about the key risks to this Ezaki Glico narrative.
Another View on Ezaki Glico's Value
The SWS DCF model presents a different perspective on Ezaki Glico. At ¥5,018, the share price is well below an estimated fair value of ¥9,332.28, which suggests the stock may be trading at a discount rather than at stretched levels.
If the cash flow assumptions behind that gap are valid, the issue is not only that the P/E might appear high today, but also that investors could underappreciate what the underlying business may be worth over a longer time frame. The key question is which signal carries more weight when the two diverge.
Look into how the SWS DCF model arrives at its fair value.
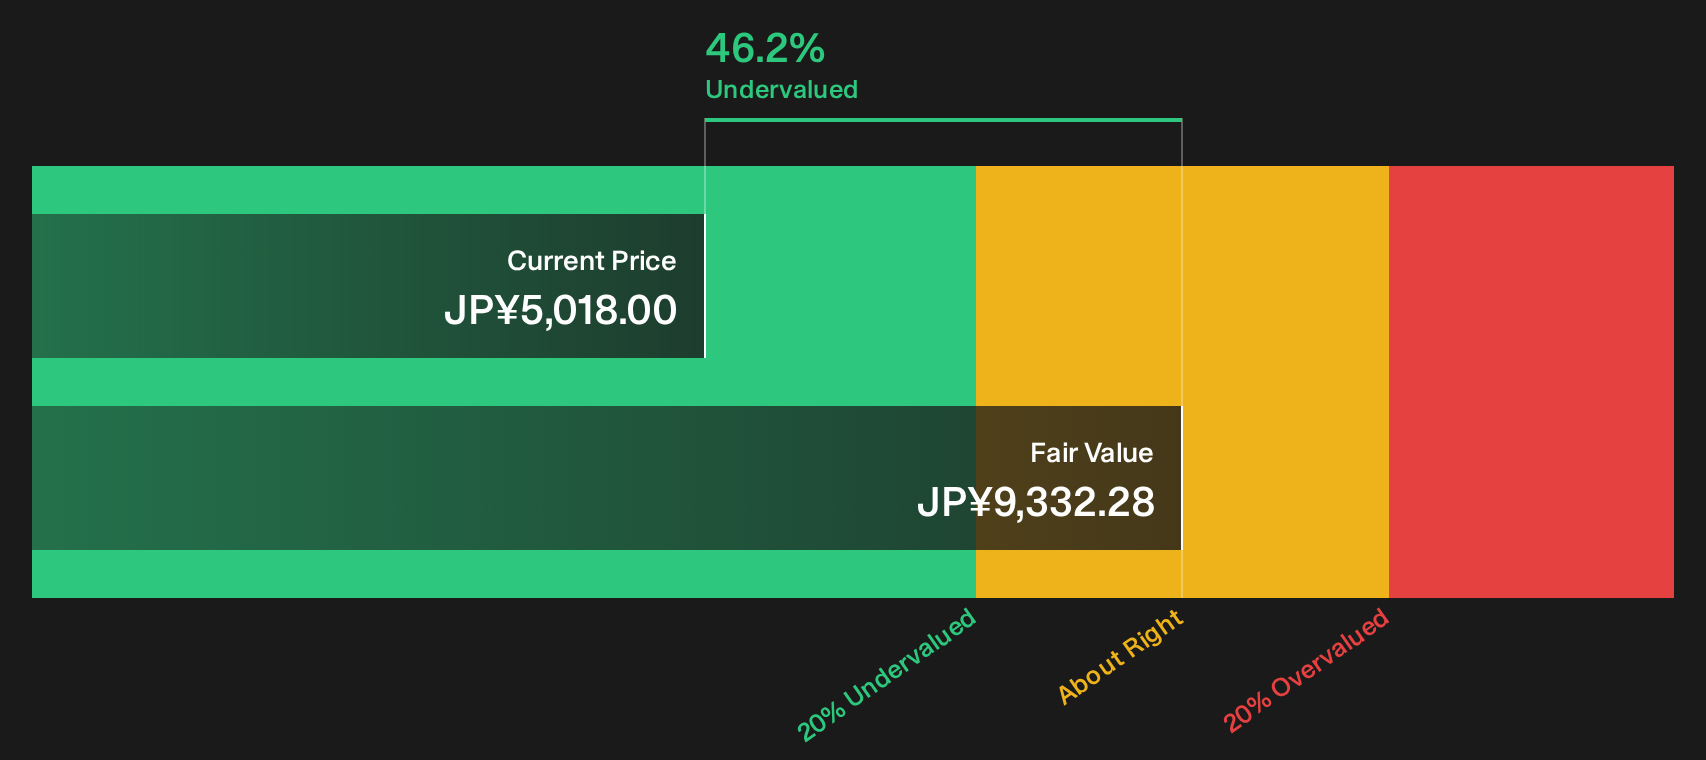
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ezaki Glico for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by Ezaki Glico's rich P/E and discounted DCF story? Act while sentiment is mixed, weigh the full picture, then decide where you stand with 2 key rewards and 3 important warning signs.
Looking for more Ezaki Glico style ideas?
Do not stop with Ezaki Glico. Broaden your watchlist now, compare different opportunities side by side, and avoid leaving potential ideas on the table.
- Target potential mispricings by scanning companies that our tools flag as attractively valued through the 18 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses with higher yields and sturdier payouts using the 16 dividend fortresses.
- Reduce portfolio stress by concentrating on companies that pair solid finances with lower overall risk scores via the 12 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com