
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Gulf Deepwater MOU Will Impact Woodside Shares
- Woodside Energy Group recently signed a non-binding MOU with PEMEX to assess future deepwater hydrocarbon opportunities in the Gulf of Mexico and share technical expertise across exploration and production.
- The agreement links Woodside’s role as operator of the Trion Oil Project, a planned ultra-deepwater development with a forecast US$7.2b capital spend, to broader collaboration with Mexico’s state producer on complex offshore work.
- We will assess how Woodside’s investment narrative is influenced by the PEMEX MOU, particularly its deepwater exposure and execution demands.
Scan beyond Woodside Energy Group and track other offshore and energy producers facing similar project and governance pressures with the curated list of 3 resilient stocks with low risk scores.
Woodside Energy Group Investment Narrative Recap
To own Woodside Energy Group, you need to be comfortable with a large, long life hydrocarbon portfolio where value is tied to big LNG and deepwater projects clearing execution hurdles on time and on budget. The PEMEX MOU leans into that thesis, but in itself does not fundamentally change the near term outlook or cash generation profile.
The key near term swing factor remains delivery risk across Scarborough, Pluto Train 2 and Trion, at a time when analyst forecasts already bake in only modest revenue growth and slightly weaker margins. The biggest current risk sits around earnings drifting, while dividends are flagged as not well covered by free cash flow.
The PEMEX MOU is the announcement that matters most here because it sits directly beside Trion, which already carries a planned US$7.2b capital spend and is 64% complete. Any extra deepwater options in the Gulf of Mexico would lean on the same project management capacity investors are watching at Trion and across Woodside Energy Group’s LNG build out.
Viewed through catalysts, this cooperation reads as Woodside trying to turn Trion experience into a repeatable deepwater template while sharing technical knowledge with PEMEX. The potential upside is more optionality in the Gulf of Mexico. The trade off is greater exposure to complex offshore work at a time when analysts already flag flat to slightly weaker earnings expectations over the next few years.
Woodside Energy Group is currently viewed in the context of analyst assumptions that revenue will grow by 4.1% a year, taking the top line to $14.6b and earnings to $2.8b by 2029, compared with earnings today of $2.7b. This implies an increase of about $0.1b in profit over that period.
Uncover why Woodside Energy Group's fair value indicates results that are broadly in line with its current price.
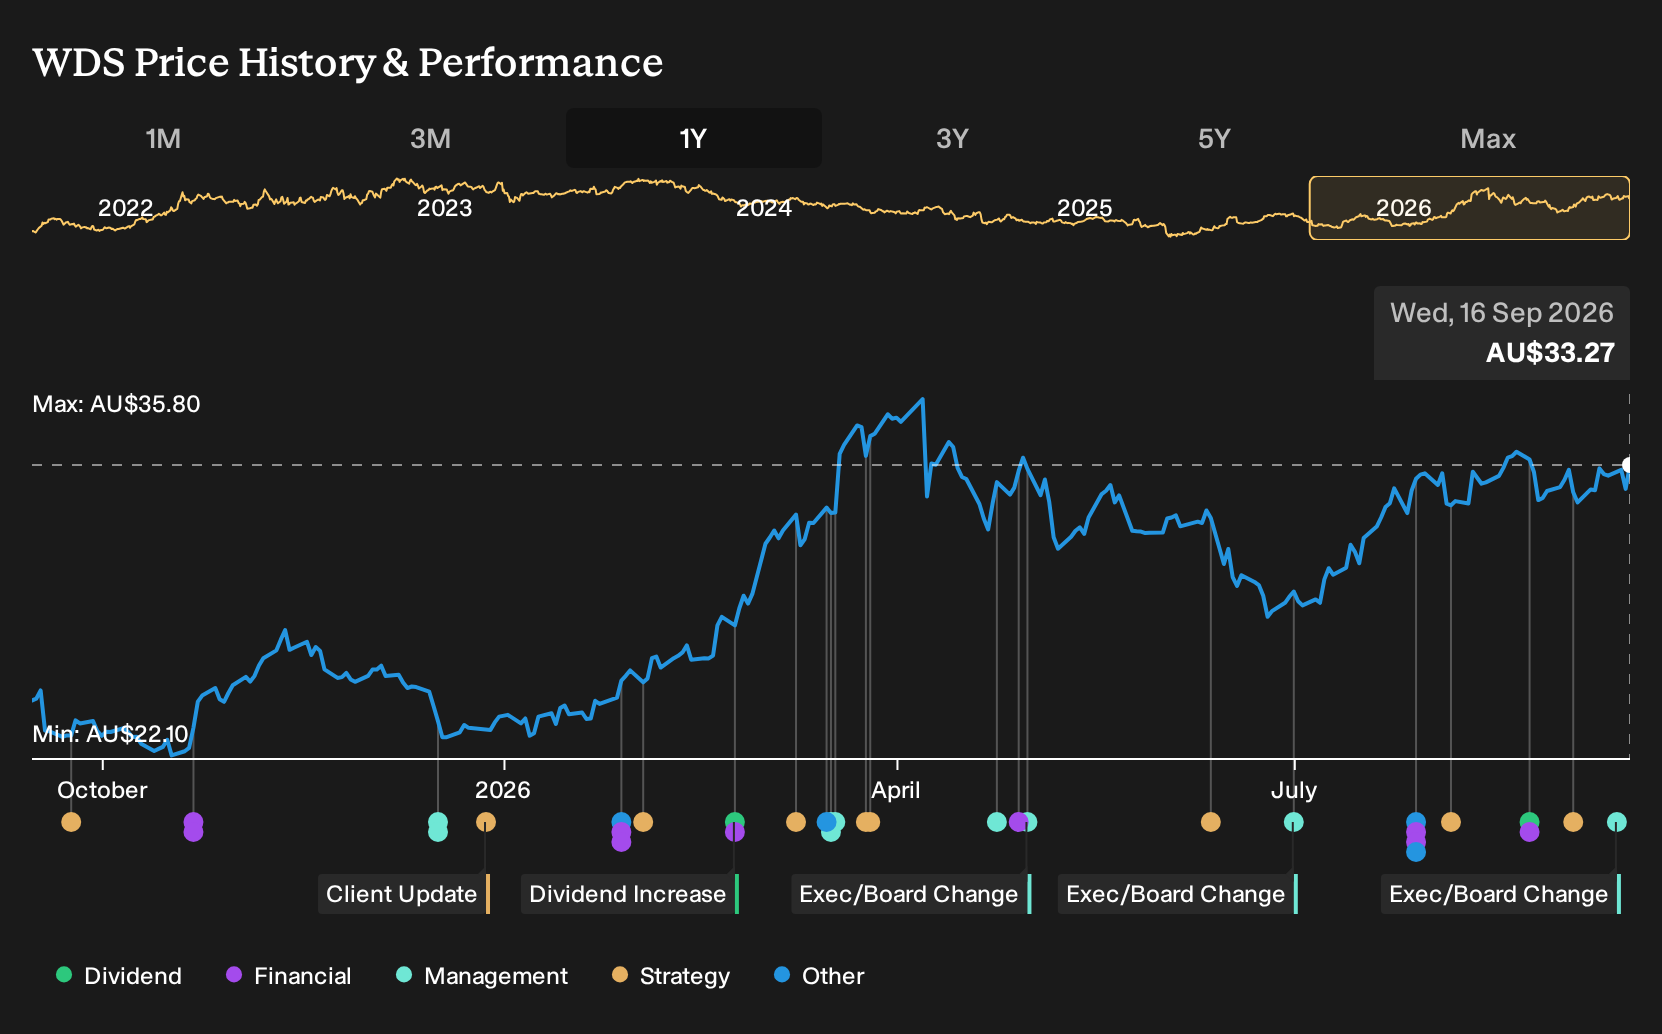
Exploring Other Perspectives
One alternative angle focuses less on project execution and more on demand risk. The most pessimistic analysts already assumed slower revenue growth of about 1.4% a year and earnings easing to roughly $2.2b by 2029 before this Woodside Energy MOU and board change. You can treat those figures as a stress test and explore how views might shift as events unfold.
Explore 5 other Woodside Energy Group fair value estimates, including one that suggests as much as 26% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Woodside Energy Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Woodside Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Woodside Energy Group's overall financial health at a glance.
Looking for more investment ideas beyond Woodside Energy Group?
If the Woodside Energy Group story has sharpened your focus on risk, cash flow and project execution, it can help to compare it with other businesses that clear different hurdles. The Simply Wall St Screener lets you quickly filter for traits that match how you like to invest instead of scrolling through endless tickers.
- Prioritise stability and balance sheet strength, and see which companies currently pass that test with the list of solid balance sheet and fundamentals (12 results).
- If you prefer to hunt for quality at a discounted price, use the 15 high quality undiscovered gems to spot under-followed businesses with robust fundamentals.
- If you want to keep risk scores front of mind while you research, compare Woodside Energy Group with a curated 3 resilient stocks with low risk scores to round out your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com