
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Mixed Q2 Results Change The Bull Case For Noble Stock (NE)?
- Noble Corporation recently reported mixed Q2 results, with revenue exceeding expectations while EPS and EBITDA came in below forecasts due to rig suspensions in Brazil.
- The update highlighted successful debt refinancing. Management indicated that this is expected to improve future cash costs, against a backdrop of firm demand for high specification offshore drillships.
- This article now explores how Noble's investment narrative is affected by the mixed Q2 earnings, particularly the impact of Brazil related operational disruptions.
Compare Noble's latest offshore update with other potential rig and energy beneficiaries by scanning our hand-picked 16 high quality undiscovered gems that are poised to benefit from similar spending trends.
Noble Investment Narrative Recap
To own Noble, you need to be comfortable with a contractor that is heavily tied to offshore project cycles and dayrates for high spec drillships. The Brazil rig suspensions are a reminder that even in firm demand conditions, operational hiccups can dent near term earnings and margins. The key short term catalyst remains getting sidelined rigs back to work on schedule.
The biggest immediate risk is that downtime stretches or similar disruptions appear in other regions, adding more white space in the calendar and pressuring EBITDA. The latest update does not appear to change the broader multi year offshore project pipeline, but it does keep execution risk front and center for now.
The recent debt refinancing sits closest to this Q2 story. Management has now pushed out maturities and indicated that lower interest expense should improve future cash costs. That structure gives Noble more flexibility to ride through temporary rig suspensions and uneven backlog conversion without leaning on more expensive funding.
For you as a shareholder, the refinancing matters because it interacts directly with the main catalysts. If offshore demand remains stable and the Brazil issues are resolved, a cleaner balance sheet could help more of any dayrate strength flow into free cash generation. If the market remains soft or idle time increases, the interest savings create a little more breathing room while Noble works through the cycle.
How Noble's Q2 Setback Interacts With Long Term Forecasts
Noble now sits in an unusual spot. The near term story is dominated by Brazil driven downtime, while the analyst models are built around a much cleaner operational picture a few years from now. That gap between current noise and projected steadier conditions is where your risk and opportunity trade off really lives.
Consensus assumptions sketch out a sizeable shift for the business over the next few years. Analysts are working with revenue growth of 8.5% per year and a move in profit margins from 5.2% today to 20.2% by 2029. On those numbers, Noble is modeled to produce earnings of US$743.2 million and earnings per share of US$3.43 around 2029, compared with US$149.6 million in earnings today.
The earnings step up implied in those figures is large in absolute terms. The increase from US$149.6 million to US$743.2 million means earnings would need to rise by about US$593.6 million. Put differently, that would be close to a 5x uplift in profit over the period, assuming the consensus path plays out rather than the more bullish or bearish scenarios in the range.
On the revenue side, the analyst framework ties those earnings to a top line of about US$3.7b in 2029. That outcome depends on the 8.5% annual growth path and on the margin expansion assumptions holding together despite the operational friction seen in Brazil and the potential for further idle time in other regions.
Noble's narrative projects US$3.7b revenue and US$743.2 million earnings by 2029. This requires 8.5% yearly revenue growth and an earnings increase of about US$593.6 million from current earnings of US$149.6 million.
Valuation work in the latest consensus also leans heavily on the idea that Noble becomes less expensive on an earnings multiple basis as profits scale. The stock is currently referenced at a P/E of 43.8x, while analysts are using a 13.1x P/E on those projected 2029 earnings of US$743.2 million. That future multiple sits below the 25.3x P/E quoted for the wider US Energy Services group in the same report.
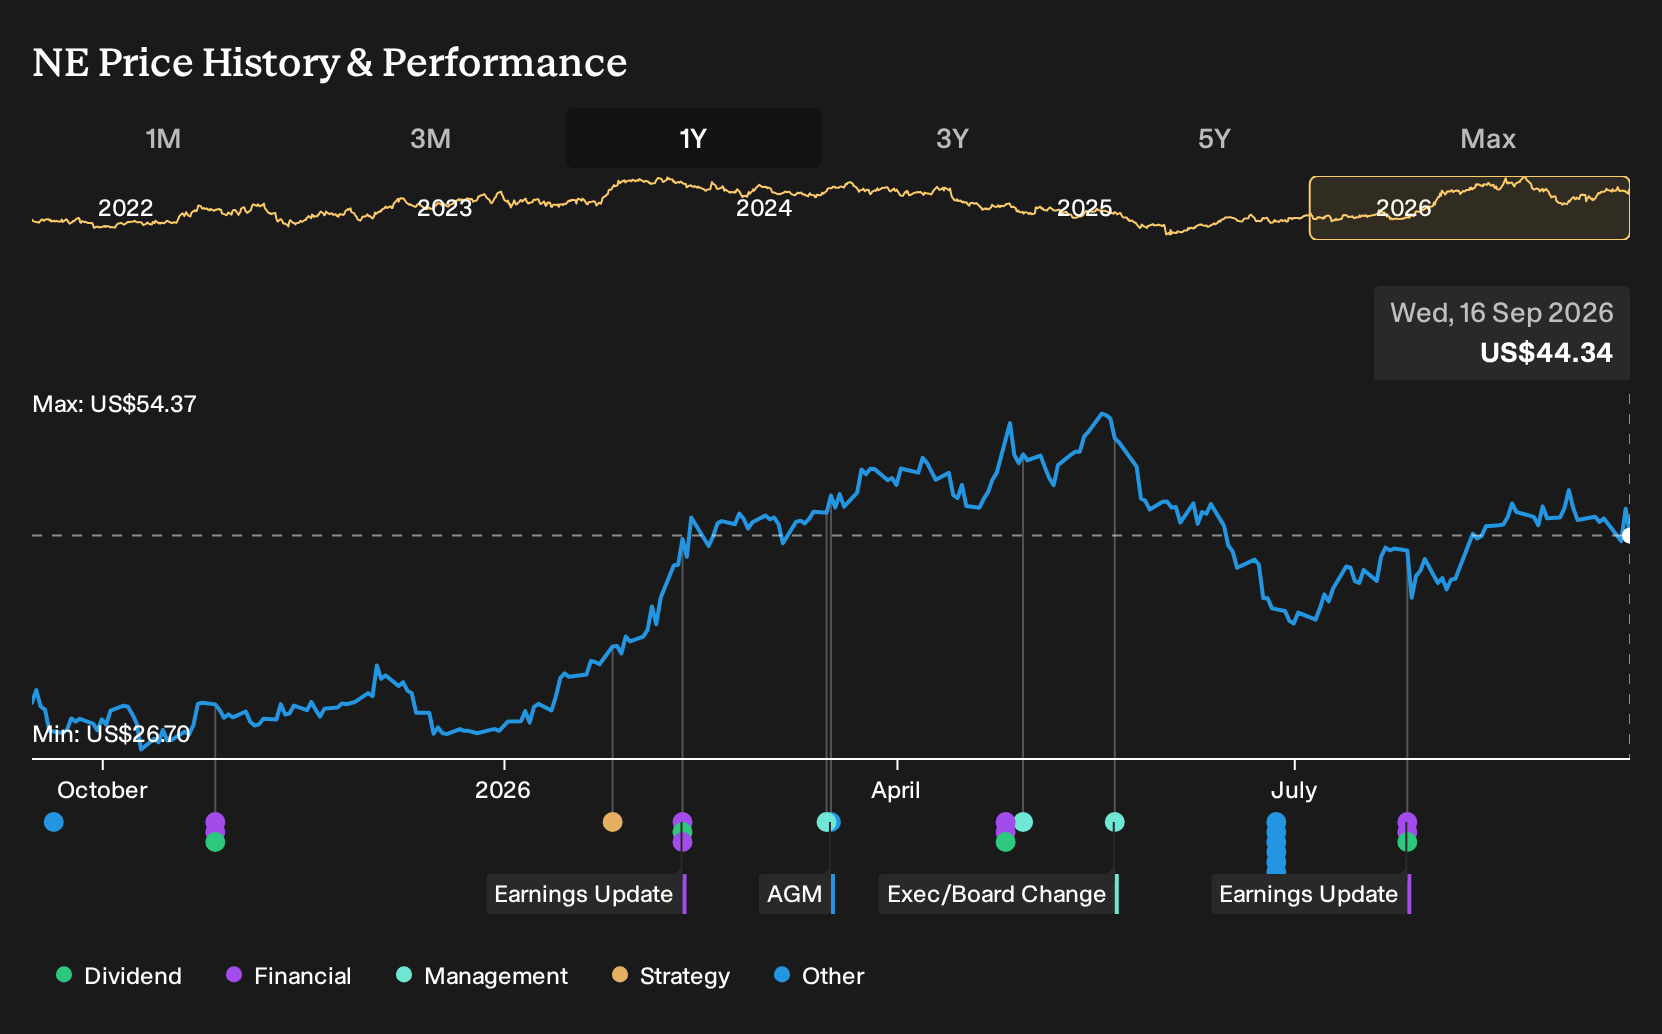
Price targets flow from that earnings and multiple mix. The consensus goal sits at US$48.09 per share, compared with a spot price of US$41.01, with individual analyst estimates stretching from US$35.00 up to US$60.00. In simple terms, the forecast asks you to accept that Noble can compound revenue at 8.5% a year, lift margins sharply, and earn US$743.2 million by 2029, while the market applies a lower P/E than it does today.
For a shareholder working through the Q2 hiccups, the key question is how much the Brazil rig suspensions and any future downtime undermine those building blocks. If idle periods keep recurring, it becomes harder for Noble to deliver the earnings ramp the consensus has pencilled in. If management can keep most of the fleet working at the assumed dayrates, the long term math in those models stays intact even as short term quarters come in choppy.
Uncover why Noble's fair value indicates an 8% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One alternate Noble story leans on backlog strength rather than downtime risk. The most optimistic analysts were pencilling in about US$3.8b of revenue and US$879.6 million of earnings by 2029 before this Brazil update, which assumes tight contracts and high utilization. You can compare that upbeat view against today’s disruption and decide which narrative feels closer to reality.
Explore 3 other Noble fair value estimates, including one that suggests as much as 215% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Noble research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Noble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Noble's overall financial health at a glance.
Looking For More Investment Ideas Beyond Noble?
If Noble's story has you thinking more broadly about where to put fresh capital to work, the next step is to widen your watchlist. The Simply Wall St Screener can help you move quickly from a single stock to a shortlist of other opportunities that better fit your own risk, income, or quality preferences.
- If you want potential value with stronger fundamentals, start by scanning a curated pool of 33 high quality undervalued stocks that combine balance sheet strength with discounted pricing.
- If income matters more to you than excitement, focus on cash flow reliability and payout support by reviewing a hand picked set of 6 dividend fortresses.
- If capital preservation is your priority, concentrate on steadier performers by filtering through 11 resilient stocks with low risk scores that score well on resilience and financial health.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com