
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Cronos Contract Win Will Impact Halliburton (HAL) Stock
- Halliburton Company recently announced a multi year bundled contract from Eni for the Cronos ultra deepwater gas development offshore Cyprus, covering integrated drilling, well construction, automation, and completions services supported by its existing Eastern Mediterranean infrastructure.
- The fully bundled scope concentrates well construction, fluids, testing, and coiled tubing with one provider. This structure could affect Halliburton’s project economics, execution risk profile, and use of its LOGIX automation platform on future offshore campaigns.
- We will now look at how Halliburton’s broader investment narrative could shift as this bundled Cronos contract ramps up.
Halliburton Investment Narrative Recap
To own Halliburton, you need to believe the business can keep turning a large, global oilfield services footprint into steadier earnings despite energy transition headwinds and a softer North American shale cycle. The Cronos contract fits that view because it adds multi year, gas focused offshore work that leans on Halliburton’s international reach and digital tools.
The key short term catalyst is whether international activity and higher value integrated projects offset pressure from decarbonization policies, regulatory costs, and any further slowdown in US drilling. The biggest risk is still exposure to fossil fuel capital spending cycles and a balance sheet with meaningful debt. This award helps, but does not remove that risk.
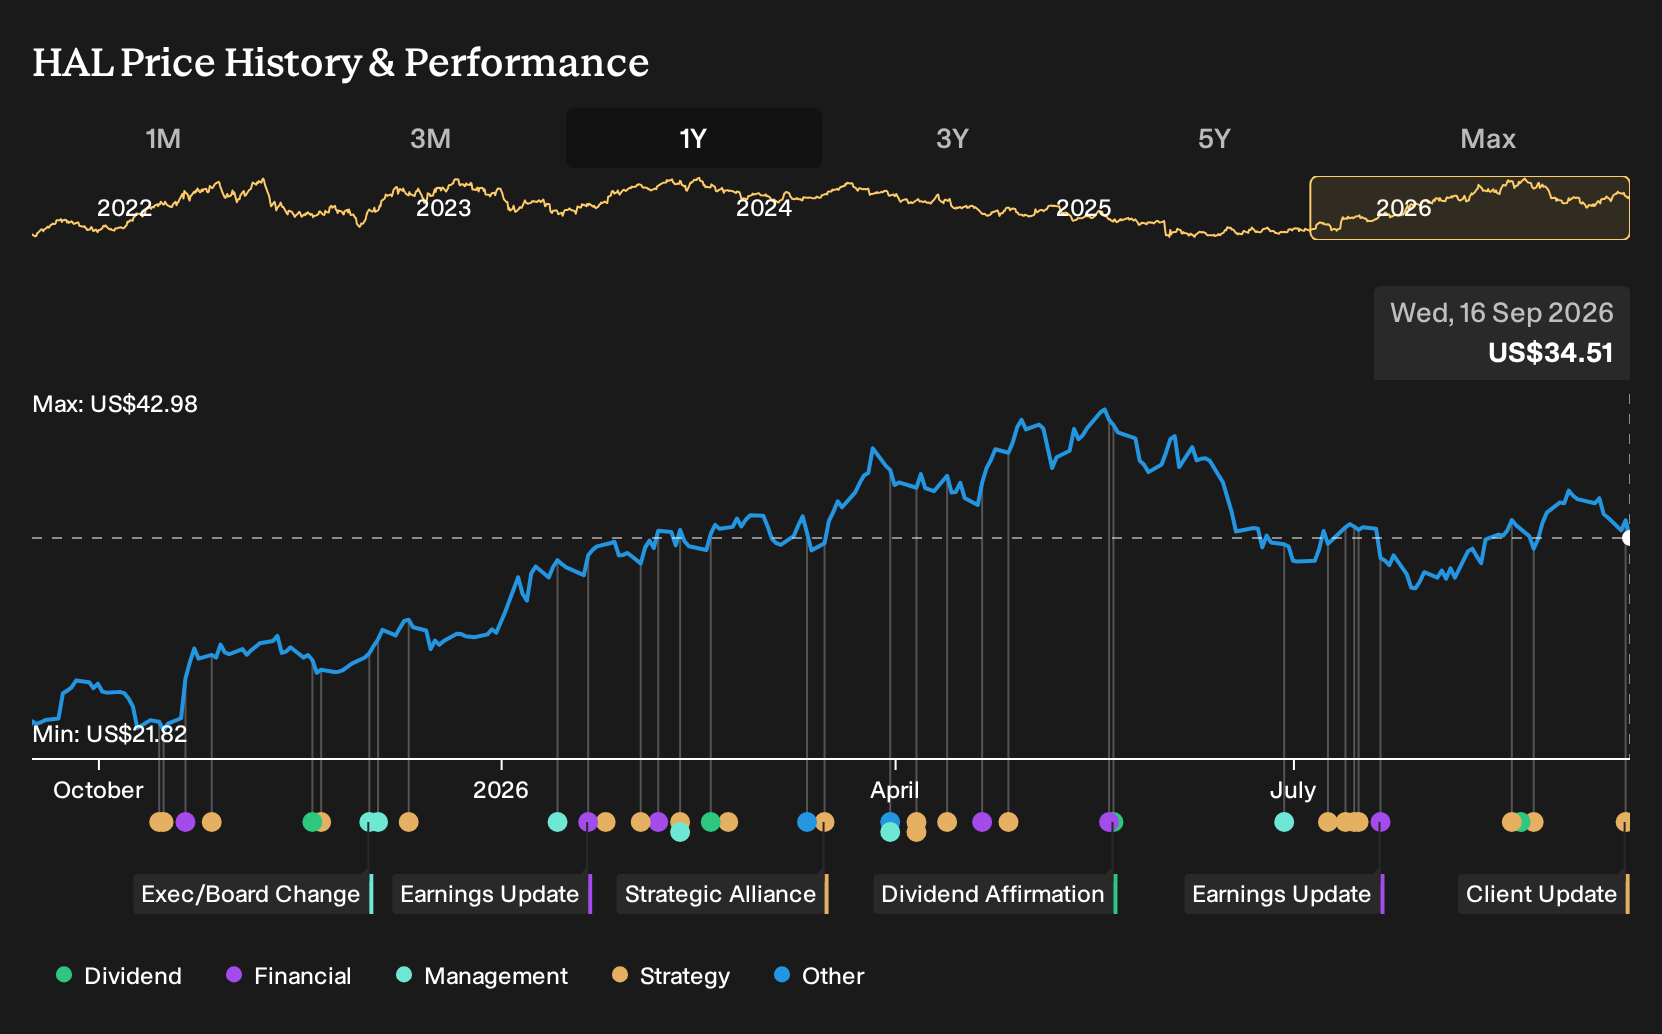
One announcement that ties directly into this is Halliburton’s plan to discuss third quarter 2026 results on the October 20 earnings call. That timing matters for Cronos because investors will watch how management frames the contract’s contribution to backlog, margins, and capital needs as the campaign ramps.
Use that call to stress test the current thesis. Listen for detail on how integrated offshore work, including Cronos, mixes with North American trends, debt management, and deployment of LOGIX automation. Analyst expectations for earnings growth and the current P/E only stay credible if execution on these large, bundled contracts shows up clearly in cash flow and profitability.
Halliburton's current analyst narrative points to revenues of US$25.1b and earnings of US$2.7b by 2029, based on a 4.0% yearly top line growth rate and an earnings move of about US$1.1b from US$1.6b today.
Uncover why Halliburton's fair value indicates a 25% potential upside to its current price before that discount to expectations begins to narrow.
Exploring Other Perspectives
The biggest swing factor the more cautious analysts watch is contract pricing pressure. Before this Cronos news, the lowest group only pencilled in Halliburton reaching about US$23.1b of revenue and US$2.8b of earnings by 2029, paired with an 11.7x P/E. You can compare that more skeptical view with your own and decide whether this new bundled win could shift it.
Explore 4 other Halliburton fair value estimates, including one that suggests it could be worth just $33.61.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Halliburton research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Halliburton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Halliburton's overall financial health at a glance.
Looking for more Halliburton style ideas?
If the Cronos contract has sharpened your interest in Halliburton, it can be useful to set it alongside other companies with different risk and return profiles. Use the Simply Wall St Screener to scan for stocks that fit the type of portfolio role you want Halliburton to play.
- For investors who want potential mispricing with quality fundamentals, review a curated set of 33 high quality undervalued stocks that might complement or contrast your view on Halliburton.
- If stability matters more than headline growth, track companies screened for resilience and financial robustness using the 11 resilient stocks with low risk scores as a reference point.
- To search beyond widely followed tickers and widen your opportunity set, consider a 16 high quality undiscovered gems that may offer different growth and risk profiles to large caps like Halliburton.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com