
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Energy Transfer (ET) Stock Looks Undervalued As Its 239% Run Tests Earnings
Energy Transfer has delivered a strong multi‑year run, and the units now sit at a level where you have to ask how firmly today’s price rests on the partnership’s earnings power. With that backdrop and fresh corporate developments in play, the key issue is whether the current valuation still lines up with what the business earns.
- Over the past 5 years, Energy Transfer has returned about 238.7%, which puts a lot of accumulated optimism on the line if the earnings story does not keep pace.
- Recent news around new natural gas projects, higher capital spending plans and a future move to the Texas Stock Exchange can influence expectations for profit growth, cash generation and the timing of returns to unitholders.
- There is a second opinion on Energy Transfer worth weighing. See what analysts think Energy Transfer's shares could be worth.
The stock's next move may depend on whether its current price is justified by the earnings that Energy Transfer generates today and is expected to produce in the future.
If you are comparing Energy Transfer with similar income-focused investments, it can be helpful to see how other high-yield opportunities measure up using 6 dividend fortresses.
Does Energy Transfer Look Undervalued on Earnings?
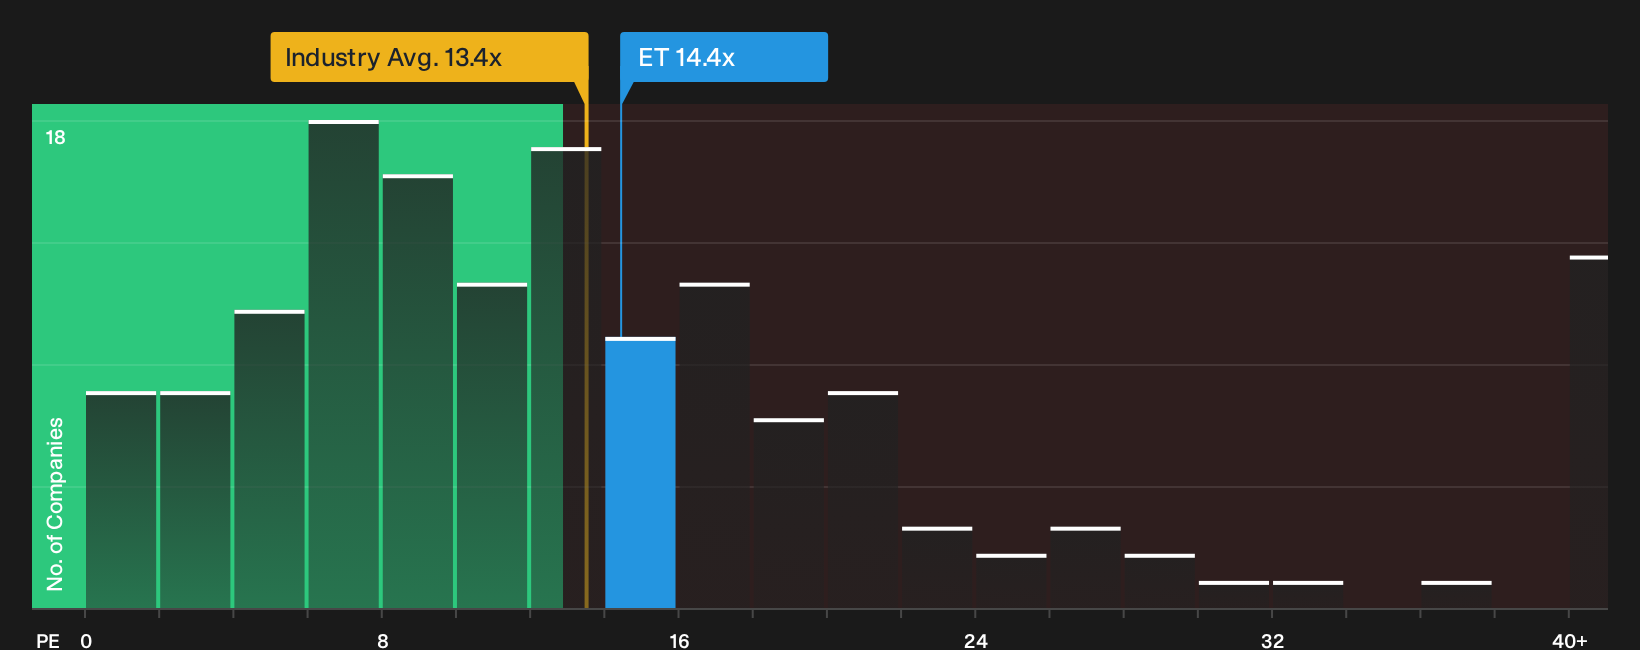
The P/E ratio is a useful way to see what you are paying for each dollar of Energy Transfer’s earnings. Using this lens, the units trade on about 14.4x earnings, which is slightly above the Oil and Gas industry average of roughly 13.4x yet below a peer group closer to 18.4x.
Because Energy Transfer’s current multiple sits below the level suggested by a tailored fair P/E benchmark that factors in its risk profile and business mix, the stock screens as undervalued on this measure. Despite the plan to shift the listing to the Texas Stock Exchange and the attention that move has attracted, the P/E still prices Energy Transfer at a discount to what this framework implies could be justified. Explore the numbers behind Energy Transfer's P/E valuation.
The Energy Transfer Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Energy Transfer leaves off by spelling out in plain terms which paths for future growth, margins and earnings would need to play out for the units to be worth materially more or less than today’s price on the Community page. Each narrative ties a fair value estimate to a clear storyline about Energy Transfer's potential catalysts and key risks, so you can track over time which version of events appears to be unfolding.
One of the top community narratives on Energy Transfer: 12% undervalued
"Recent long-term, investment-grade customer commitments on multi-billion-dollar projects de-risk cash flows and improve visibility into earnings growth…"
Discover why this Narrative puts Energy Transfer at 12% undervalued.
Energy Transfer’s valuation still leaves one piece of the puzzle unanswered
Price multiples tell you what the market pays for Energy Transfer today. At the same time, broker models sketch out where they think earnings and cash flows could land a few years from now. Explore where analysts expect Energy Transfer to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com