
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nebius Group (NBIS) Stock Looks Expensive Even With Strong Sales Hopes
Nebius Group has delivered a very strong share price run over the past few years, yet the latest pullback raises a fresh question for investors about how far its current valuation stretches relative to its sales base. With the stock now reflecting both rapid AI infrastructure ambitions and a recent bout of volatility, the key issue is how much revenue power is realistically baked into that price.
- Over the past 5 years the stock has gained about 165.7%, which puts a lot of weight on whether Nebius Group's sales can support that kind of rerating.
- The announced plan to deploy 5 GW of AI infrastructure and raise about US$200b more financing, including US$5b of convertible notes, can shape future sales growth expectations while also concentrating attention on how efficiently those revenues might be converted into returns on such heavy capex.
- The analysts covering Nebius Group have run their own numbers. See what analysts think Nebius Group's shares could be worth.
The stock's next move may depend on whether Nebius Group's current share price is well aligned with what its sales performance can reasonably justify.
If you want a second reference point while you assess Nebius Group's AI infrastructure story against its sales, it can help to run the same lens over 60 AI infrastructure stocks.
Does Nebius Group Look Pricey on Sales?
P/S is doing most of the heavy lifting for Nebius Group because the story today is far more about top line potential than near term earnings or book value.
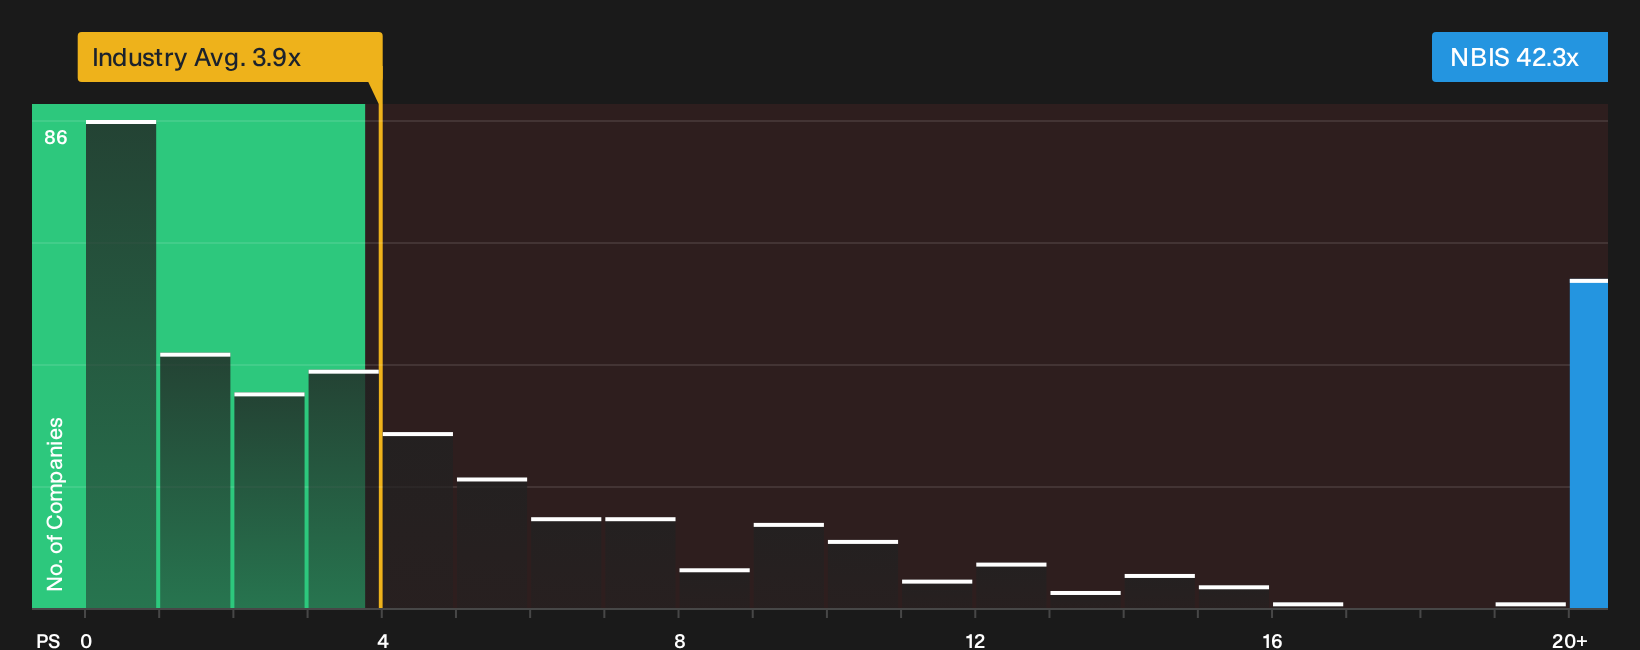
The stock trades on a P/S ratio of about 42.3x, compared with a Software industry average around 3.9x and a peer group closer to 9.9x. On this framework, the Fair Ratio model, which blends factors like growth profile, profitability, size and risk, points to a lower level than the current P/S, so the shares screen overvalued on sales. Despite the recent Palantir partnership giving Nebius extra AI infrastructure credibility, the valuation already assumes a very strong revenue engine relative to what typical software peers are priced on. Explore the numbers behind Nebius Group's P/S valuation.
The Nebius Group Narrative: What Would Justify Today's Price?
Nebius Group's Narratives pick up where the valuation puzzle leaves off and describe the mix of future growth, margins and earnings that would need to play out for the stock to be worth materially more or less than it is today, using the Community page as their home base. Rather than relying on a single ratio or model output, they unpack the set of business outcomes that figure rests on, so you can monitor over time whether those conditions still appear realistic.
Community views on Nebius Group are split between those who see the AI buildout as underappreciated and those who think the current pricing already incorporates much of that story.
Bull case: 33% undervalued
"Nebius leverages rapid AI demand, global expansion, strategic partnerships, advanced technology, and strong funding to drive recurring revenue, margin growth, and long-term profitability..."
Discover why this Narrative puts Nebius Group at 33% undervalued.
Bear case: 74% overvalued
"Surging capital expenditures, as evidenced by the company's commitment to $2 billion in 2025 alone and a multi year power plan, will likely drive down free cash flow and pressure net margins for years..."
Explore why this Narrative puts Nebius Group at 74% overvalued.
One more Nebius Group check that belongs beside the valuation work
Price ratios and growth stories only tell part of what you need to know about Nebius Group. Separate risk checks have flagged specific concerns that deserve your own closer look. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com