
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ArcBest (ARCB) Could Be 24% Undervalued On Its Managed Solutions Narrative
ArcBest (ARCB) heads into Morgan Stanley's 14th Annual Laguna Conference on September 15, 2026, with investors watching how management frames its integrated logistics model, recent share performance, and longer term returns.
Recent trading has cooled after a strong run, with ArcBest's share price falling 3.6% over the past day and about 10% over both the past month and past quarter. Even so, the year to date share price return sits at 68.4% and the 1 year total shareholder return is 86.4%, pointing to strong longer term gains despite fading short term momentum ahead of the conference.
Compare ArcBest's conference catalyst with other transport and logistics players by scanning our hand picked list of list of solid balance sheet and fundamentals (22 results).
The recent pullback raises a straightforward question: Are investors reassessing ArcBest’s underlying logistics earnings power, or simply cooling on a stock that moved faster than the business? The valuation answers start to show up in the numbers.
Most Popular Narrative: 24% Undervalued
ArcBest's most followed valuation story pegs fair value around $170.77 per share, compared with the recent $129.97 close. This puts the conference spotlight firmly on whether that gap is justified by future freight earnings and cash flows.
Ongoing shift toward Managed Solutions and Asset-Light business, with double-digit growth and improved profitability in these segments, supports revenue diversification and higher-margin earnings potential, aligning with changing customer needs amid e-commerce growth and omnichannel supply chain adoption.
See why 4 investors see ArcBest as 24% undervalued.
Result: Fair Value of $170.77 (UNDERVALUED)
Still, the story can change quickly if freight demand stays soft or if higher labor expenses and execution risks around leadership shifts begin to weigh on ArcBest’s margin narrative.
Find out about the key risks to this ArcBest narrative.
Another View: What Multiples Say About ArcBest
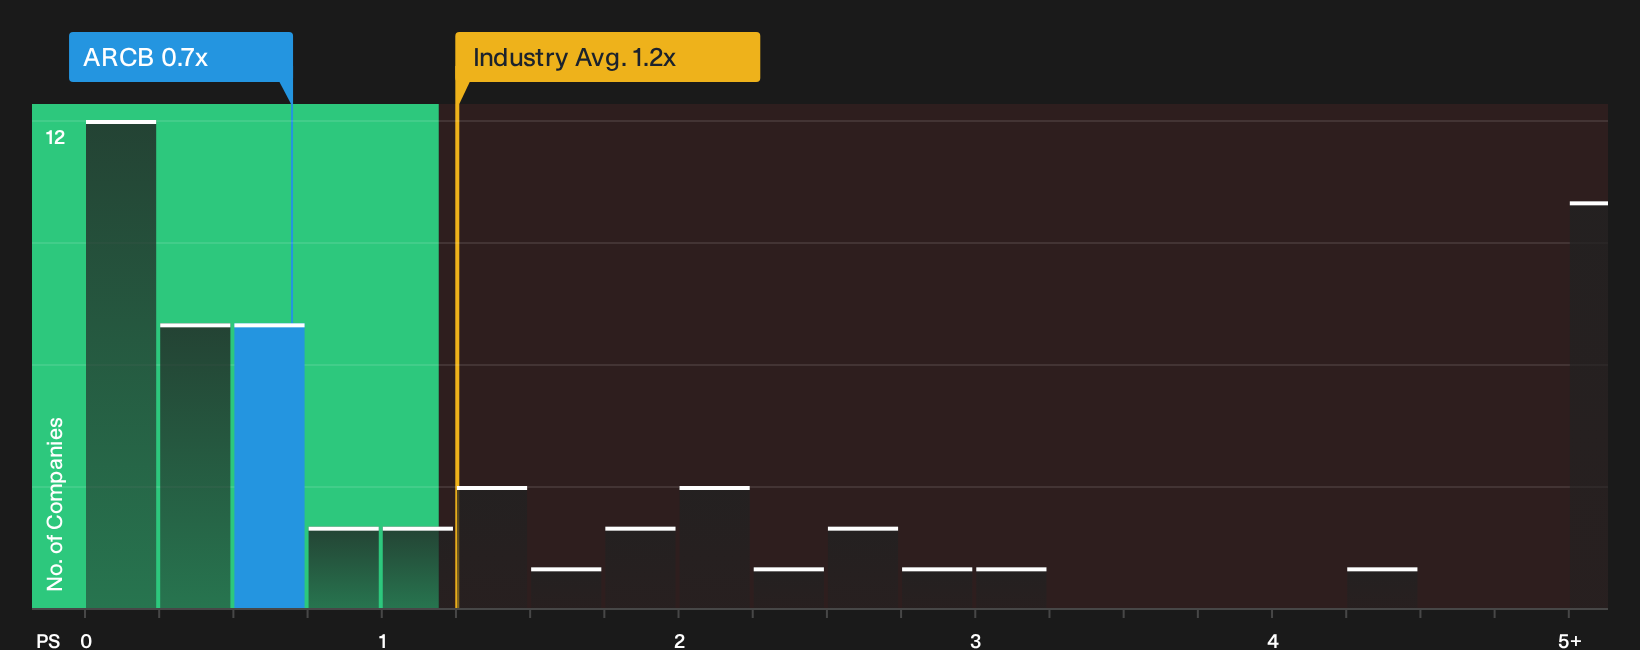
The earlier story paints ArcBest as materially undervalued using a fair value of $170.77 per share. A simpler price to sales lens looks different. ArcBest trades at 0.7x sales versus a fair ratio of 0.6x, which points to a richer tag on this metric.
That 0.7x level still sits under both the US Transportation industry at 1.2x and the 0.8x peer average, so the stock screens cheaper than many rivals even if it is above the fair ratio suggested by the model. The gap leaves you weighing whether this premium to fair ratio is justified or if it signals less room for error if the story slips.
To see how this pricing framework fits with the rest of the numbers, including earnings forecasts and margin assumptions, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the ArcBest story can either be a warning or an opening. Move quickly, test the data yourself, and weigh the 3 key rewards and 3 important warning signs.
Looking for more ArcBest investment ideas?
Do not stop with ArcBest. The market is full of other opportunities, and a few minutes with the right screeners can surface ideas you would otherwise miss.
- Target quality at a discount by checking companies that pass our value filters through the 33 high quality undervalued stocks.
- Prioritise resilience by scanning stocks that combine strong finances with steadier risk profiles in the 11 resilient stocks with low risk scores.
- Get ahead of the crowd by reviewing lesser known businesses with solid fundamentals using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com