
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Navigator Holdings (NVGS) Stock Looks Fully Valued On Current Earnings
Navigator Holdings has delivered a strong share price run in recent years, which naturally puts a spotlight on what investors are really paying for. The open question is whether the current valuation is supported by the earnings that underpin the business.
- Over the past 5 years the stock has returned 210.4%, which puts real weight on whether today’s valuation lines up with the company’s profit engine.
- The business model relies heavily on converting shipping activity into consistent earnings, so the durability of margins and cash generation can be crucial for how much investors are prepared to pay per dollar of profit.
- There is a second opinion on Navigator Holdings worth weighing. See what analysts think Navigator Holdings's shares could be worth.
For investors, the debate is whether Navigator Holdings' current share price is justified by the earnings it produces today and is expected to produce in the future.
If you are weighing Navigator Holdings on its earnings, it can help to compare it with a focused list of other companies screened on clear criteria such as 33 high quality undervalued stocks.
Is Navigator Holdings Getting Expensive on Earnings?
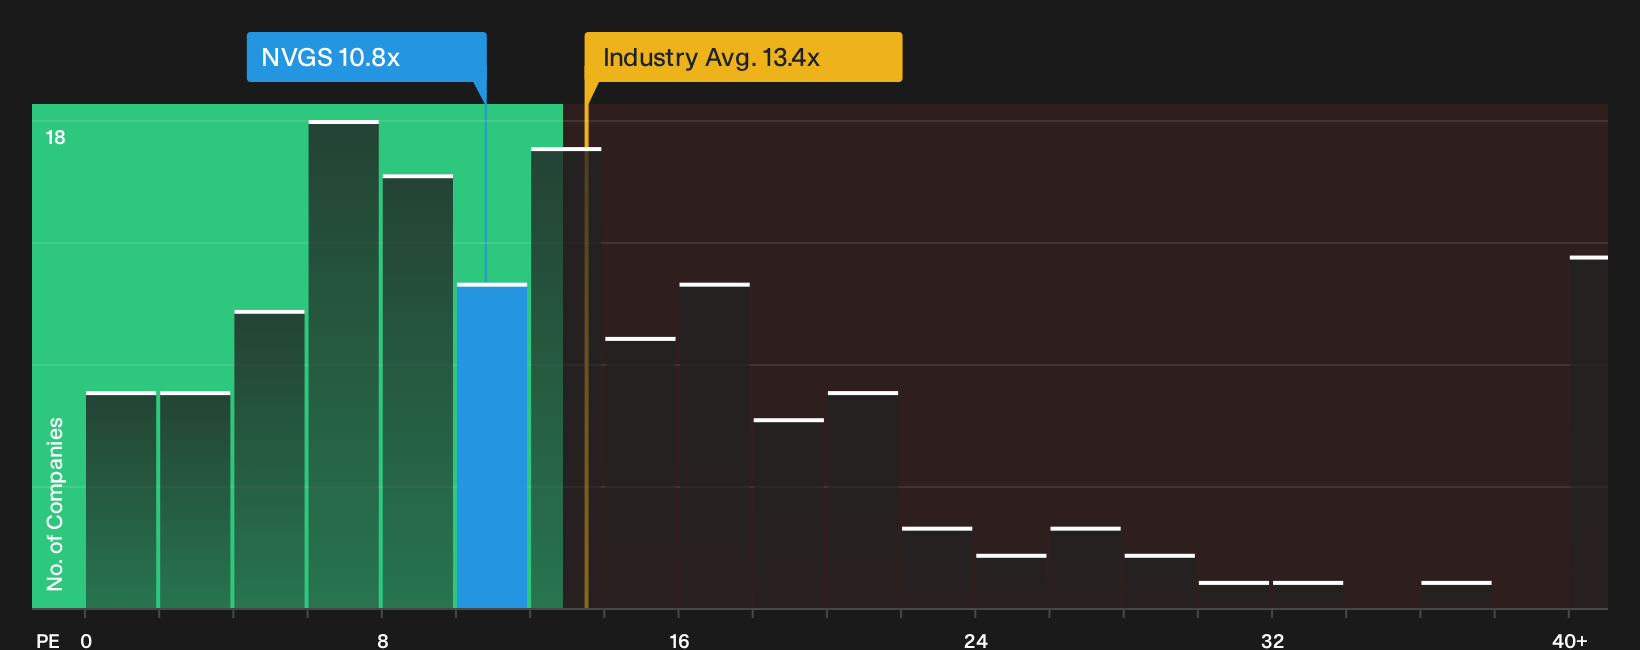
The P/E ratio is a useful lens for Navigator Holdings because earnings are central to how investors usually think about shipping businesses. On this measure, the stock trades on roughly 10.8x earnings, which is below the Oil and Gas industry average of about 13.4x and also under the broader peer group around 15.5x.
The fair multiple implied by a tailored model that factors in Navigator Holdings' own growth profile, profitability and risks sits lower than where the shares change hands today. That gap points to the stock screening as overvalued on this earnings yardstick, even though it appears cheaper than the wider sector on simple comparisons. For anyone weighing this, the key question is whether the quality and resilience of Navigator Holdings' profits justify paying more than what its fundamentals alone might support. Explore the numbers behind Navigator Holdings's P/E valuation.
The Navigator Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Navigator Holdings pick up where the P/E puzzle leaves off and spell out what kind of growth, margins and earnings path would need to play out for the stock to look meaningfully cheaper or richer than today's share price. Rather than relying on a single multiple or model output, each narrative sets out the assumptions behind its view of fair value so you can compare those expectations with Navigator Holdings' actual results as they come through, all within the Community page setting.
One of the top community narratives on Navigator Holdings: roughly fairly valued
"Navigator's fleet renewal program and newbuild investments position the company to benefit from tightening environmental regulations and efficiency gains..."
Discover why this Narrative puts Navigator Holdings at roughly fairly valued.
One more piece of the Navigator Holdings puzzle before you move on
Before acting on any view of Navigator Holdings' valuation, it is worth asking who is steering the ship, how they are rewarded, and whether those incentives truly line up with your interests as a shareholder. See who runs Navigator Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com