
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Three Days Left Until Miramar Hotel and Investment Company, Limited (HKG:71) Trades Ex-Dividend
Regular readers will know that we love our dividends at Simply Wall St, which is why it's exciting to see Miramar Hotel and Investment Company, Limited (HKG:71) is about to trade ex-dividend in the next 3 days. The ex-dividend date is usually set to be two business days before the record date, which is the cut-off date on which you must be present on the company's books as a shareholder in order to receive the dividend. The ex-dividend date is an important date to be aware of as any purchase of the stock made on or after this date might mean a late settlement that doesn't show on the record date. In other words, investors can purchase Miramar Hotel and Investment Company's shares before the 21st of September in order to be eligible for the dividend, which will be paid on the 9th of October.
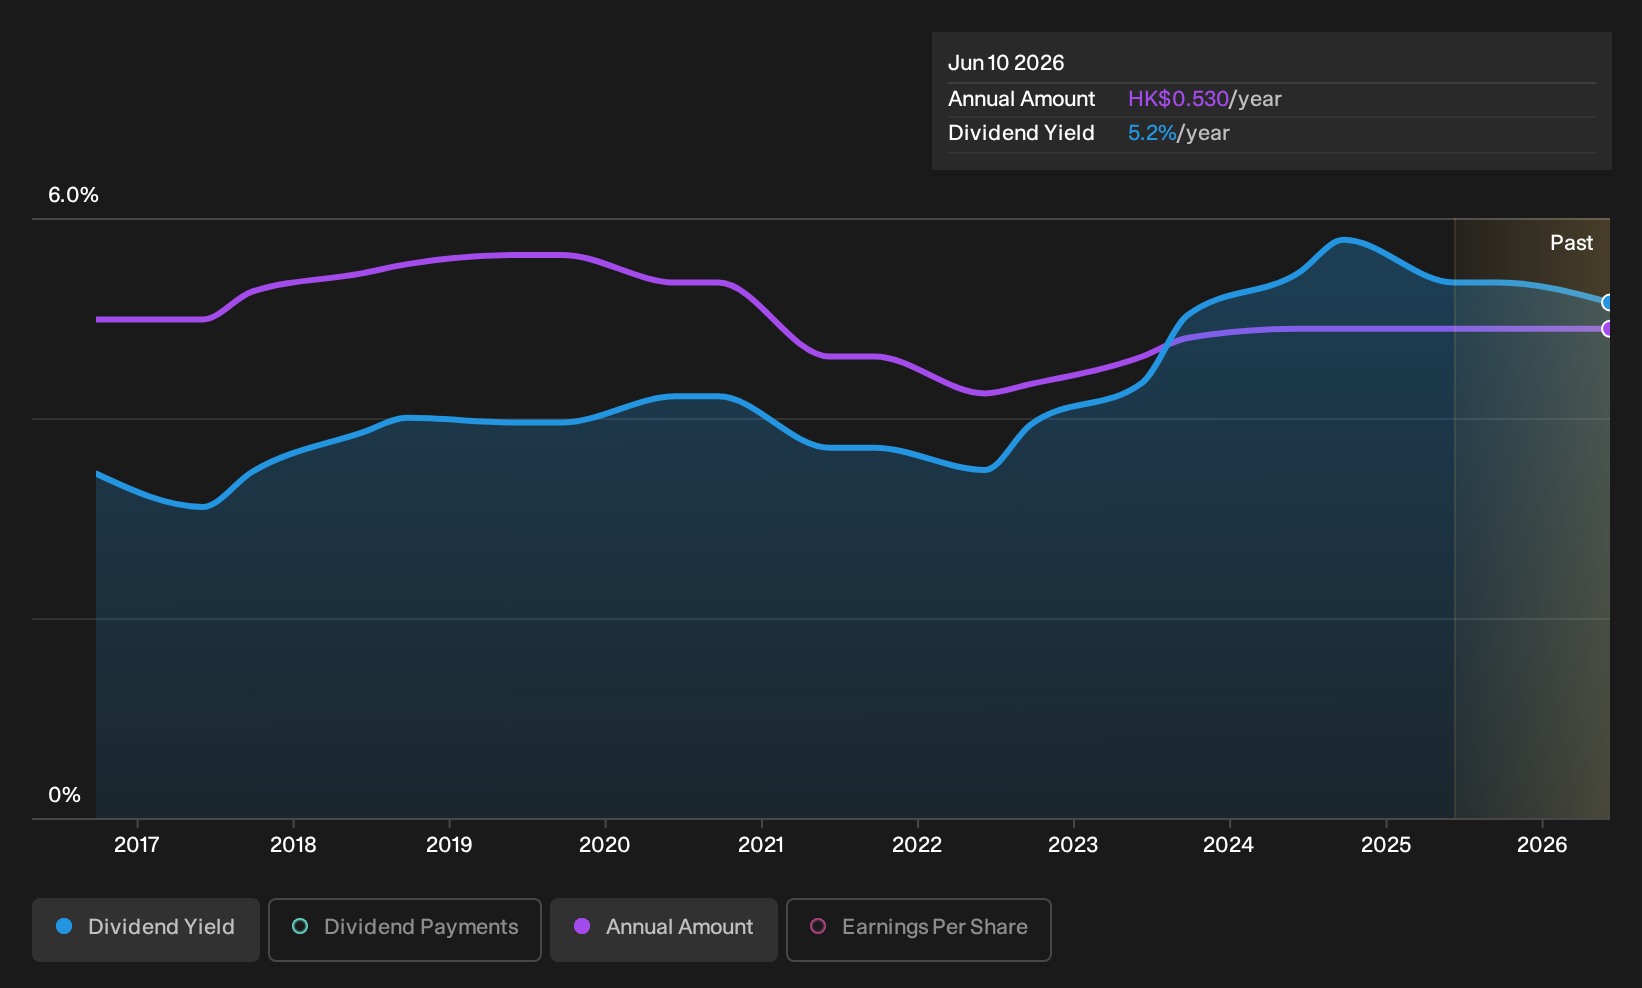
The company's next dividend payment will be HK$0.23 per share. Last year, in total, the company distributed HK$0.53 to shareholders. Based on the last year's worth of payments, Miramar Hotel and Investment Company has a trailing yield of 5.3% on the current stock price of HK$10.02. Dividends are an important source of income to many shareholders, but the health of the business is crucial to maintaining those dividends. That's why we should always check whether the dividend payments appear sustainable, and if the company is growing.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. Miramar Hotel and Investment Company paid out more than half (53%) of its earnings last year, which is a regular payout ratio for most companies. A useful secondary check can be to evaluate whether Miramar Hotel and Investment Company generated enough free cash flow to afford its dividend. It paid out more than half (59%) of its free cash flow in the past year, which is within an average range for most companies.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
View our latest analysis for Miramar Hotel and Investment Company
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If earnings decline and the company is forced to cut its dividend, investors could watch the value of their investment go up in smoke. For this reason, we're glad to see Miramar Hotel and Investment Company's earnings per share have risen 18% per annum over the last five years. Miramar Hotel and Investment Company has an average payout ratio which suggests a balance between growing earnings and rewarding shareholders. Given the quick rate of earnings per share growth and current level of payout, there may be a chance of further dividend increases in the future.
Another key way to measure a company's dividend prospects is by measuring its historical rate of dividend growth. Miramar Hotel and Investment Company's dividend payments are effectively flat on where they were 10 years ago.
Final Takeaway
Is Miramar Hotel and Investment Company an attractive dividend stock, or better left on the shelf? It's good to see earnings are growing, since all of the best dividend stocks grow their earnings meaningfully over the long run. That's why we're glad to see Miramar Hotel and Investment Company's earnings per share growing, although as we saw, the company is paying out more than half of its earnings and cashflow - 53% and 59% respectively. Overall we're not hugely bearish on the stock, but there are likely better dividend investments out there.
Want to learn more about Miramar Hotel and Investment Company? Here's a visualisation of its historical rate of revenue and earnings growth.
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.