
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Defense Health Contract Altering The Investment Case For Everforth (EFOR)?
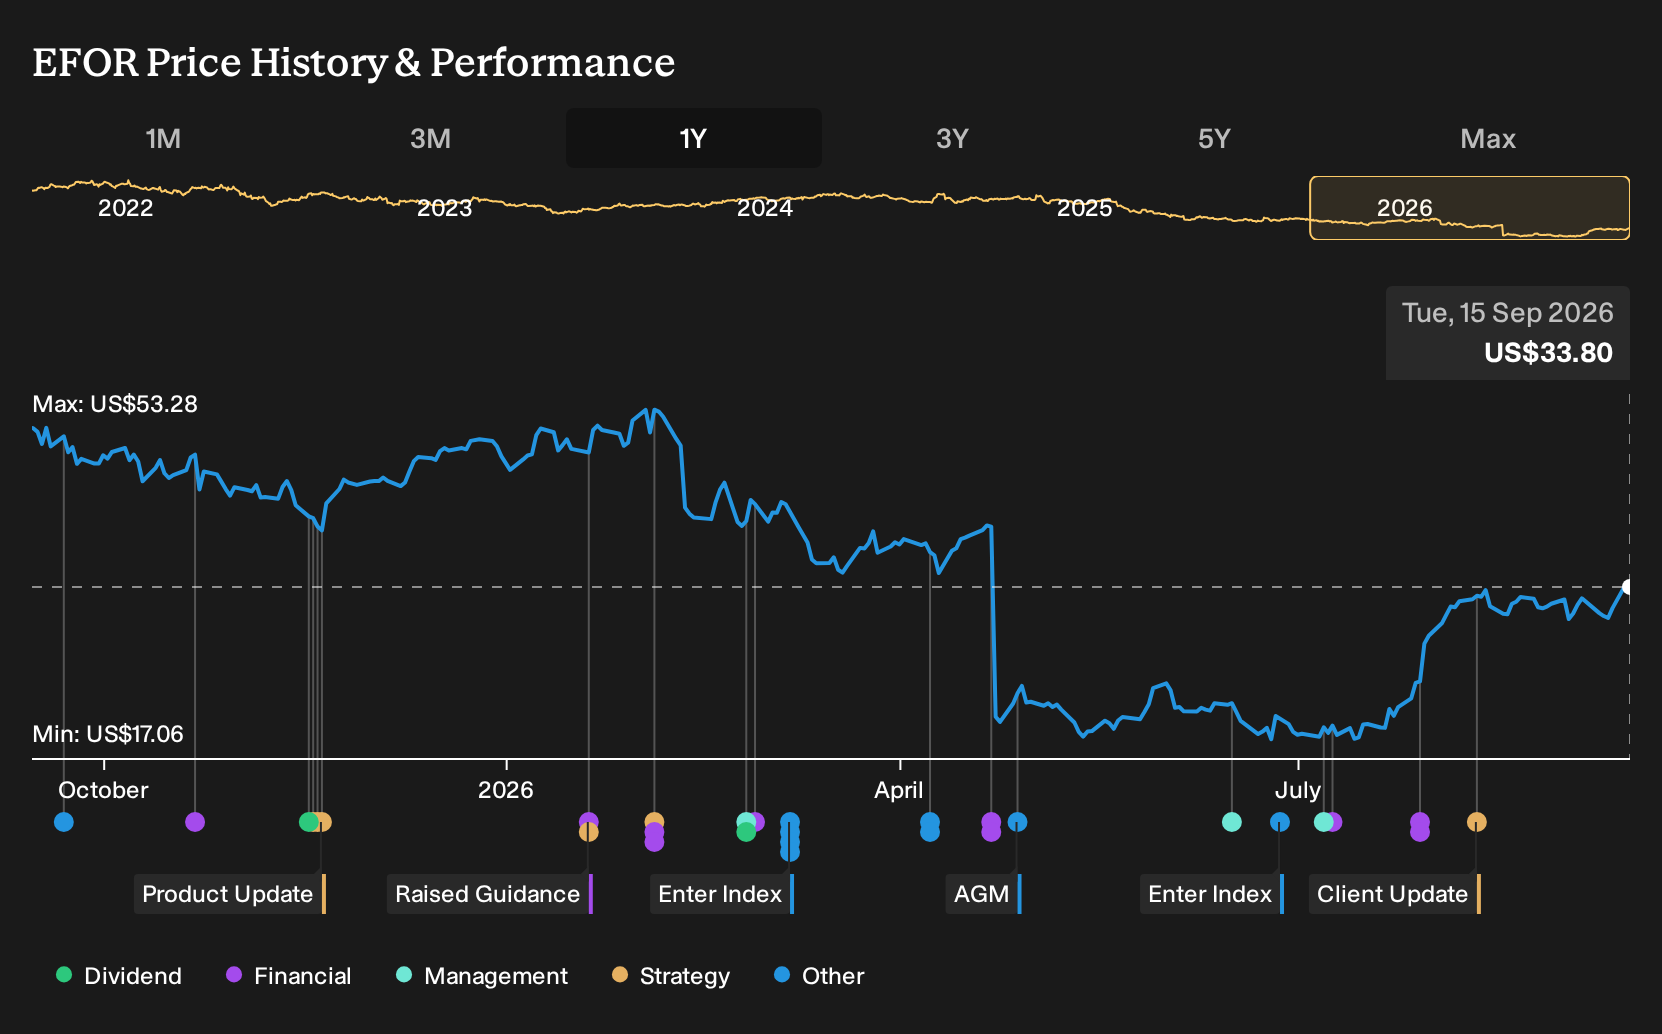
- Everforth's federal unit, Everforth ECS, recently secured a four-year, US$30 million contract to support the Defense Health Agency's technology modernization program, alongside second-quarter results that exceeded management's guidance despite year-over-year declines in total revenue and profit.
- The win highlights ongoing strength in Everforth's federal operations, even as the segment's book-to-bill ratio of 0.8 to 1 points to a shrinking backlog and questions about future workload.
- The focus now shifts to how Everforth's investment narrative incorporates a shrinking federal backlog alongside this new Defense Health Agency contract.
Scan how Everforth's contract win and backlog pressure compare with other government technology contractors by reviewing the hand picked list of solid balance sheet and fundamentals (22 results) that may better balance resilience and contract momentum.
Everforth Investment Narrative Recap
To stay in Everforth, you need to believe this IT services group can turn a mixed picture into cleaner growth. The business has a solid position across commercial and federal clients, but you are balancing a shrinking federal backlog, softer assignment revenue and thin net margins at 2.1%. In the near term, the key swing factor is whether consulting and higher value work can offset pressure in traditional staffing.
The recent Defense Health Agency win helps the story on execution but does not fully change the short term risk profile. The main opportunity is better mix and margin in consulting, while the key risk is that weak bookings, macro slowdowns and debt that is not well covered by operating cash flow keep earnings under strain.
Among recent developments, the four year, US$30 million contract for Everforth ECS with the Defense Health Agency is the clearest operational proof point tied to the current thesis. It supports the idea that the federal arm still wins relevant modernization work in cloud, cybersecurity and data, even as overall revenue and profit have declined year over year.
For catalysts, this contract matters because federal consulting is typically higher value than legacy staffing and can support gross margin resilience if executed well. The tension for you as an investor is straightforward: contract momentum like this points to execution upside, while the 0.8 to 1 book to bill ratio, softer margins versus last year and debt coverage concerns keep the risk side of the ledger heavy.
Everforth Forecasts And What Needs To Go Right
Analysts sketch a relatively modest path for Everforth, with revenue projected to grow by 1.6% per year and earnings expected to move from $98.1 million today to $141.8 million by 2029. That shift implies an earnings increase of about $43.7 million and hinges on profit margins stepping up from 2.5% now to 3.4% over the same period.
Everforth's narrative projects US$4.2 billion revenue and $141.8 million earnings by 2029. This requires 1.6% yearly revenue growth and an earnings increase of about $43.7 million from $98.1 million.
On the valuation side, the consensus view ties that 2029 earnings figure to a P/E of 9.2x, compared with roughly 7.3x today, to support an aggregate price target of $27.33. For context, the analysts with the most optimistic stance see earnings at $203.6 million, while the most cautious sit closer to $126.9 million, which signals a wide range of possible outcomes rather than a single, tight path for the business.
Uncover why Everforth's fair value indicates a 16% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For Everforth, the biggest swing factor in the bullish alternate story is AI led consulting. The most optimistic analysts were modeling revenue at about US$4.4b and earnings of roughly US$200.9 million by 2029 before this Defense Health Agency contract. That is far above the US$4.2b and US$141.8 million consensus path and could shift again as views update.
Explore another Everforth fair value estimate, including one that suggests potential upside of up to 100% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Everforth research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Everforth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everforth's overall financial health at a glance.
Looking For More Investment Ideas Beyond Everforth?
If Everforth has sharpened your thinking but you want a wider set of options, it can help to line it up next to other businesses with different strengths. The Simply Wall St Screener gives you quick shortcuts to focused lists so you can compare balance sheets, income profiles and risk levels without getting lost in thousands of tickers.
- If capital protection is front of mind, start with companies that combine resilience and low risk by reviewing 11 resilient stocks with low risk scores that pass a tougher quality filter.
- For investors aiming at future re rating potential, look through 16 high quality undiscovered gems that pair strong fundamentals with less attention from the market.
- If steady income matters more than headline growth, focus on 6 dividend fortresses that offer higher yields backed by more robust financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com