
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tamboran Resources (ASX:TBN) Starts Beetaloo Gas Sales, Is A 23% Discount Justified?
Tamboran Resources event overview
Tamboran Resources (ASX:TBN) has started initial gas sales from its Shenandoah South Pilot Project in the Beetaloo Basin, marking first delivery of Beetaloo volumes into the Northern Territory gas market.
Tentative momentum has been building around Tamboran Resources, with a 1 month share price return of 11.54% and a year to date share price gain of 45.00%, supported by milestones such as the Shenandoah South pilot entering the Northern Territory gas market.
Scan beyond Tamboran Resources and compare this gas milestone with other energy plays on our hand picked 38 power grid technology and infrastructure stocks poised to benefit from growing demand for reliable supply.
Tamboran Resources has already logged a strong run, yet the first Beetaloo gas now flowing under a long-term contract suggests the story may not be fully priced. How does the current valuation stack up against that momentum?
Most Popular Narrative: 23% Undervalued
Tamboran Resources last closed at A$0.29 compared with a narrative fair value of A$0.38, so the story skews to upside potential if those assumptions play out. That gap rests on Beetaloo gas moving from pilot to contracted volumes and reshaping the earnings profile over time.
Progress towards first gas from the Beetaloo Basin Pilot Area in the third quarter of calendar 2026, supported by an 88% complete compression facility and an APA owned pipeline in final commissioning, is expected to move Tamboran Resources from a pre revenue phase toward contracted gas sales. This is likely to affect revenue visibility and cash flow generation.
See why 4 investors see Tamboran Resources as 23% undervalued.
Result: Fair Value of A$0.38 (UNDERVALUED)
Still, the Tamboran Resources narrative leans heavily on timely Beetaloo project execution and ongoing access to fresh capital. Setbacks on either front could quickly challenge that upside case.
Find out about the key risks to this Tamboran Resources narrative.
Another view on Tamboran Resources valuation
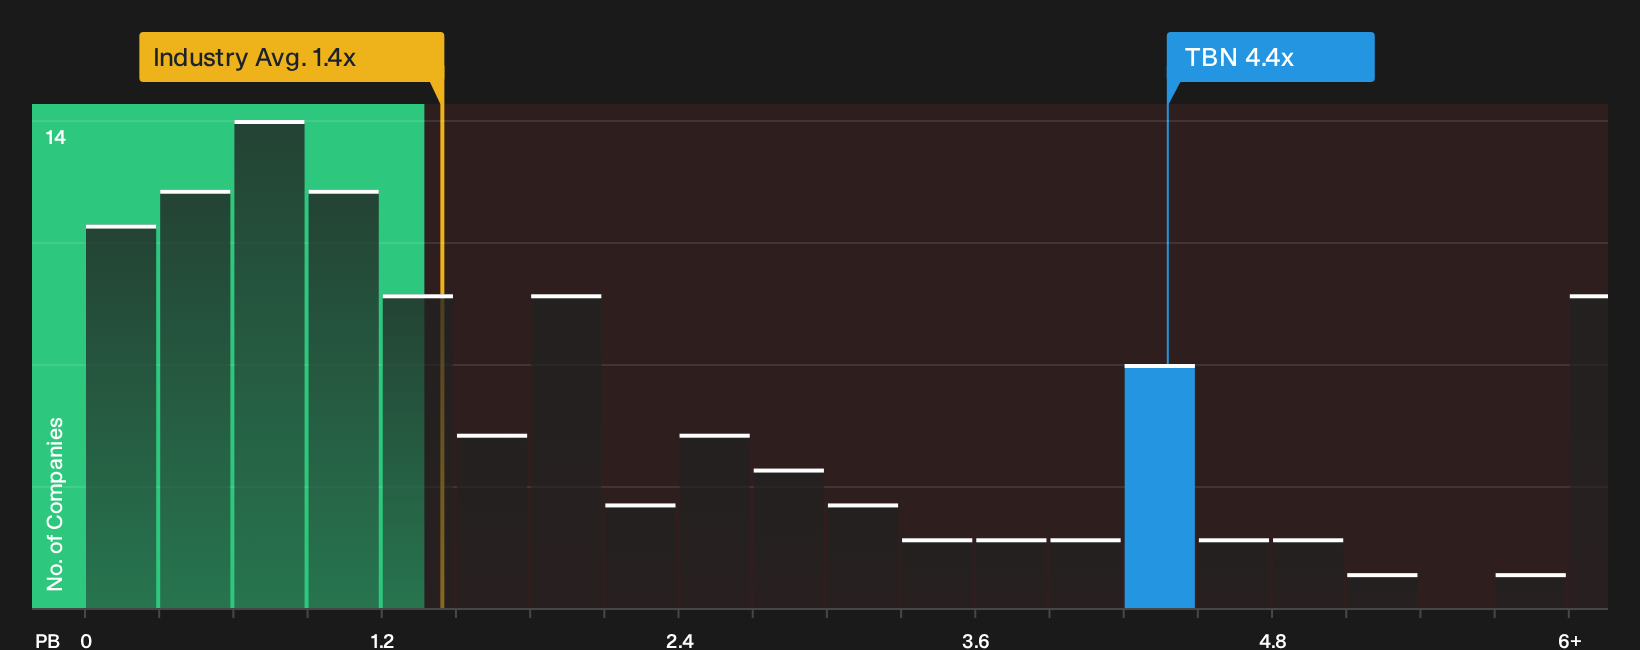
The story around Tamboran Resources looks supportive when anchored to a narrative fair value of A$0.38, but the market is sending a different signal through plain book value maths. On a P/B of 4.4x versus 1.4x for the Australian Oil and Gas industry and 1.1x for peers, the shares screen as expensive. If the ratio drifts closer to those benchmarks over time, today’s optimism could feel like a valuation risk rather than an opportunity.
See what the numbers say about this price in more detail with our valuation breakdown, including how that premium P/B compares across the sector, in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this Tamboran Resources story feels finely balanced between promise and pressure, act quickly, review the numbers yourself, and weigh both sides with the 1 key reward and 4 important warning signs.
Looking for more Tamboran Resources investment ideas?
If Tamboran Resources has your attention, do not stop here. Broaden your watchlist with a few focused screeners that surface very different kinds of opportunities.
- Target quality at a discount and zero in on companies that combine strong fundamentals with appealing prices using the 5 high quality undervalued stocks.
- Prioritise resilience and stress test your portfolio against shocks by filtering for companies on the 3 resilient stocks with low risk scores.
- Hunt for tomorrow’s potential standouts before the crowd catches on by scanning the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com