
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tenet Healthcare (THC) Stock Looks Undervalued Despite Its 282% Three Year Run
Tenet Healthcare has been on a remarkable multi year run, and with the stock now around US$265.78, the question is whether that price still lines up with what its earnings can support. Recent headlines around its operations and balance sheet add fresh context to that valuation puzzle for investors trying to anchor expectations to the underlying business.
- Over the past 3 years the stock has returned about 281.9%, which puts a lot of weight on the idea that future earnings can justify such a step up.
- Management is reshaping parts of the group, including layoffs at revenue cycle arm Conifer Health Solutions and a US$2.0b upsized notes offering to refinance nearer term debt. These moves can influence both cost structure and the timing of future interest expenses that feed directly into earnings power.
- Your read on Tenet Healthcare is one view; the desks covering it have another. See what analysts think Tenet Healthcare's shares could be worth.
The issue now is whether Tenet Healthcare's current share price is adequately supported by the earnings profile implied by these developments.
If you are weighing Tenet Healthcare against other earnings driven stories, it can help to line it up beside 33 high quality undervalued stocks.
Does Tenet Healthcare Look Undervalued on Earnings?
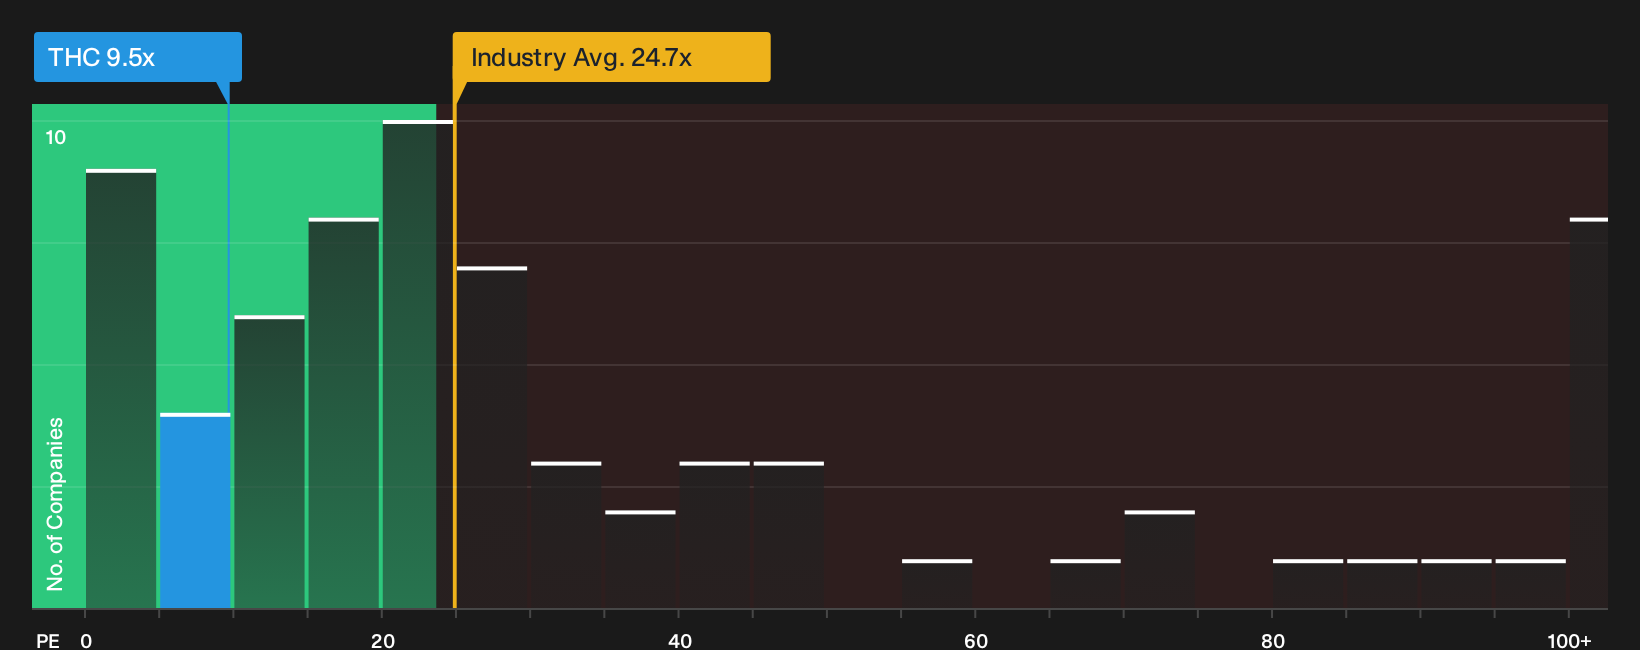
The P/E ratio fits Tenet Healthcare because earnings drive so much of how investors frame the story. On this yardstick, Tenet Healthcare trades on roughly 9.5x earnings, which is less than half the wider healthcare sector level of about 24.7x and also below a peer group that averages around 19.9x. That gap suggests the market is applying a sizeable discount even though the business is profitable.
Because the P/E that might be expected given Tenet Healthcare's size, margins and risk profile sits above the current 9.5x level, the stock screens as undervalued on this earnings multiple. Despite the recent US$2.0b upsized notes offering to refinance nearer term debt, equity investors are still pricing the shares at a lower earnings multiple than both peers and the tailored benchmark this model points to. Explore the numbers behind Tenet Healthcare's P/E valuation.
The Tenet Healthcare Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Tenet Healthcare pick up where the valuation puzzle leaves off and explain what growth, margin and earnings paths would need to occur for the stock to be worth meaningfully more or less than today’s price on the Community page. Each scenario links its implied number to a clear view of how Tenet Healthcare's prospects and risk profile might evolve, which you can revisit whenever fresh information becomes available.
Community views on Tenet Healthcare split between a modest discount to its earnings story and a premium that already prices in a lot of execution.
Bull case: 7% undervalued
"Expanded reliance on technology driven cost efficiencies, including automation and AI supported processes, can support margins in the near term..."
Discover why this Narrative puts Tenet Healthcare at 7% undervalued.
Bear case: 10% overvalued
"Tenet Healthcare is seeing increased reliance on supplemental Medicaid programs and state-directed payments, including US$92 million of out-of-period supplemental Medicaid revenues..."
Explore why this Narrative puts Tenet Healthcare at 10% overvalued.
One more Tenet Healthcare piece worth checking before you move on
Before you lean too hard on today’s multiples and scenarios, it helps to see how professional analysts currently sketch out this hospital group a few years from now, and how that picture lines up with the price on your screen. Explore where analysts expect Tenet Healthcare to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com