
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Amazon AI Chip Deal Change Qualcomm Stock Narrative
- Qualcomm Technologies announced a multi generation collaboration with Amazon to supply customized AI inference silicon and high speed optical connectivity, including up to 1.6T links, for large scale data centers, while also deepening its own use of Amazon AI tools to reduce chip design cycles.
- The arrangement ties potential AI chip purchases of up to US$60b to Amazon receiving purchase linked warrants worth about US$4b in Qualcomm equity, aligning both companies around scaling Qualcomm's data center hardware as the firm seeks to rely less on smartphones and modem contracts.
- We will now look at how Qualcomm's multiyear Amazon AI data center deal could reshape its investment narrative around diversification.
QUALCOMM Investment Narrative Recap
To own QUALCOMM, you need to believe its push beyond smartphones into AI infrastructure, automotive and IoT can offset pressure from handset cycles and shrinking Apple modem revenue. The Amazon AI data center agreement speaks directly to that pivot, but the lack of minimum purchase commitments means it does not yet change the short term reality of unproven data center demand.
The key near term swing factor remains execution on diversification while protecting margins in core mobile chips in the face of MediaTek and in house OEM silicon. The biggest risk is that AI and data center initiatives stay expensive and early stage, with higher R&D and integration costs but limited revenue traction.
The Amazon collaboration is the announcement that matters most for this thesis. QUALCOMM is now aligned with a top hyperscaler on multi generation AI inference silicon and 1.6T class optical links, and is also leaning on Amazon AI tools to shorten chip design cycles. That directly targets the current bottlenecks around power efficiency and bandwidth in large AI data centers.
For investors tracking catalysts, this agreement is an operational proof point that QUALCOMM is being considered for meaningful AI infrastructure roles alongside its work with partners like Cornelis Networks. The warrant structure tied to up to US$60b of potential chip purchases creates a clear incentive to scale deployments, but it still leaves execution risk and timing uncertainty squarely on management.
QUALCOMM's narrative projects US$60.5b revenue and US$11.5b earnings by 2029. This assumes 11.1% yearly revenue growth and an earnings increase of about US$2.2b from US$9.3b today.
Discover how QUALCOMM's fair value indicates a 6% potential upside to its current price, which could close quickly if QUALCOMM's AI data center story gains traction.
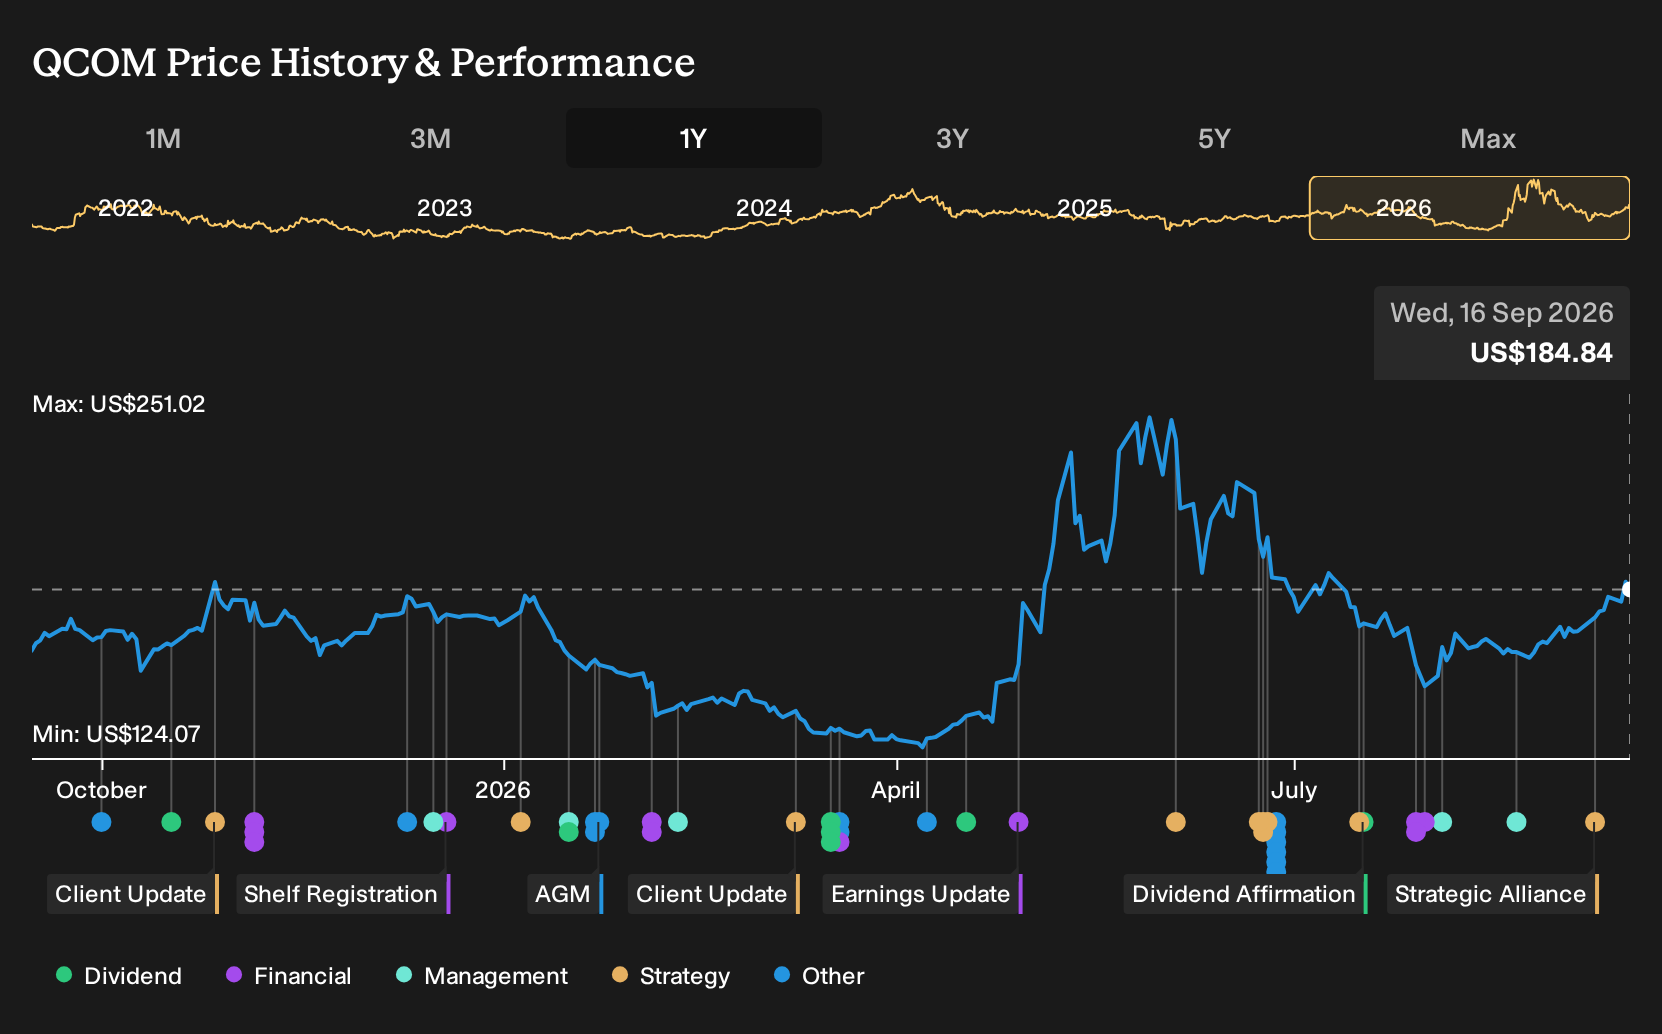
Exploring Other Perspectives
Some of the lowest Qualcomm analysts focus less on the Amazon AI data center deal and more on geopolitical risk. They were assuming only 3.2% yearly revenue growth and about US$9.2b in earnings by 2029, with a US$100 price target. That is a much harsher read. Use it as a reminder that opinions can differ widely and may shift as this Amazon agreement is incorporated into new research.
Explore 8 other QUALCOMM fair value estimates, including one that suggests as much as 6% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your QUALCOMM research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QUALCOMM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate QUALCOMM's overall financial health at a glance.
Looking for more investment ideas beyond QUALCOMM?
Once you have a view on QUALCOMM, it can help to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener gives you a fast way to spot stocks that line up with your own goals rather than someone else's model portfolio.
- If capital preservation matters most to you, focus on businesses that have tempered risk profiles and consistent fundamentals using the 11 resilient stocks with low risk scores.
- For investors hunting for potential mispricings, filter for companies that combine quality metrics with valuations that look restrained through the 33 high quality undervalued stocks.
- If reliable cash returns are a priority, concentrate on companies that currently offer stronger yield support and cash distributions through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com