
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Earnings Beat Change The Bull Case For Mohawk Industries Stock (MHK)?
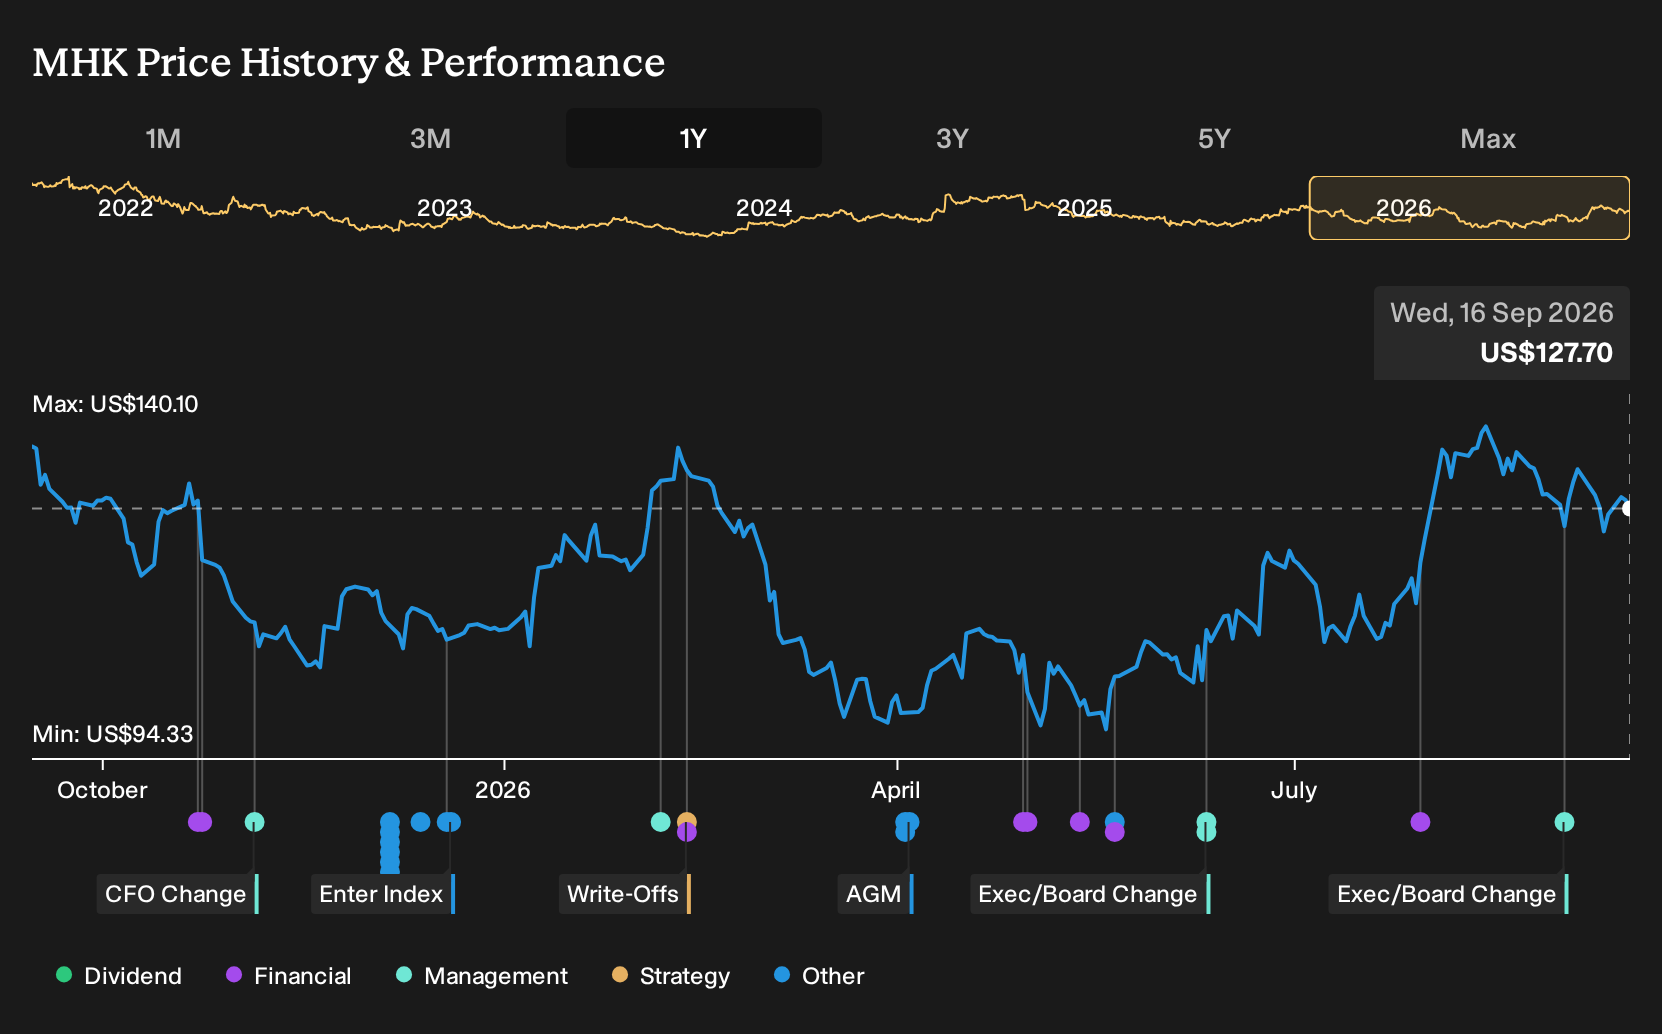
- Mohawk Industries recently reported a strong Q2, with both revenue and forward EPS guidance coming in ahead of analyst expectations for the period.
- The flooring producer also delivered the fastest reported revenue growth and largest estimate beat within its home furnishings peer group, highlighting relative operating strength.
- We will now examine how Mohawk Industries' stronger than expected Q2 guidance could reshape the existing investment narrative around the business.
See how Mohawk Industries' earnings surprise compares with other potential movers by reviewing our hand picked list of 33 high quality undervalued stocks.
Mohawk Industries Investment Narrative Recap
To own Mohawk Industries, you need to believe the flooring producer can turn a cyclical, construction linked business into steadier cash generation through efficiency, product mix and disciplined pricing. The latest Q2 beat helps that case in the near term, since it suggests current demand and cost controls are holding up better than many feared.
The key short term catalyst is whether that operational momentum carries into the next few quarters while residential remodeling and new builds remain uneven. The biggest immediate risk still looks tied to volume and pricing pressure if homeowners keep delaying projects and competitors lean harder on discounts, which could quickly squeeze margins again.
One useful way to frame this Q2 is against Mohawk Industries’ existing profitability profile. Net profit margin sits at 4.2%, a touch below 4.4% a year ago, and Return on Equity is 5.4%, which is described as low. The stronger quarter does not erase that margin backdrop, but it does show the cost base and pricing structure are capable of supporting better earnings than many expected.
That matters because analysts expect earnings to grow 12.9% per year and revenue is forecast to increase 2.3% annually. This points to a thesis built more on margin repair than on explosive top line expansion. Recent results, coupled with guidance that exceeded expectations, bring more attention to execution on cost, mix and capacity decisions, as well as familiar risks around overcapacity, higher input costs and trade policy that can still undercut that profitability story.
What The Current Analyst Story Implies For Mohawk Industries
Mohawk Industries is currently modeled on a relatively simple set of moving parts. Analysts are baking in modest 2.2% yearly revenue growth, a lift in net margin from 4.2% today to 6.1% in three years, and a step up in earnings from US$464.1 million now to US$723.6 million by 2029. Put differently, consensus assumes the business adds roughly US$259.5 million in profit over that stretch, mainly by squeezing more earnings out of each dollar of sales rather than chasing aggressive top line expansion.
On those same projections, the consensus view is that Mohawk Industries could be generating about US$11.9b of revenue and US$723.6 million of earnings in 2029. That path implies 2.2% annual revenue growth and an earnings increase of roughly US$259.5 million from current earnings of US$464.1 million.
Uncover why Mohawk Industries' fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You are seeing one clear fork in the Mohawk Industries story. The lowest analysts worry that the heavy US$480 million 2026 spend and new plants could lag, so their pre earnings models were closer to US$11.6b of revenue and US$710.8 million of profit by 2029. That more cautious playbook may shift after this Q2 surprise.
Explore 2 other Mohawk Industries fair value estimates, including one that suggests it could be worth just $135.79.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mohawk Industries research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Mohawk Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mohawk Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Mohawk Industries?
If Mohawk Industries has sharpened your focus on quality and execution, it can be useful to widen the lens and compare it with other listed businesses using the Simply Wall St Screener.
- For investors who want potential upside with discipline on quality, review a curated group of 16 high quality undiscovered gems that combine solid fundamentals with less crowded coverage.
- If resilience matters more than excitement, filter for 11 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- When capital preservation and financial robustness sit at the top of your checklist, start with a list of solid balance sheet and fundamentals (22 results) that can help you focus on companies with stronger fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com