
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Record Q3 Results Just Shift Adobe (ADBE) Investment Narrative?
- Adobe reported record fiscal Q3 2026 results with US$6.76b in revenue, AI-first annual recurring revenue above US$650m, updated full year guidance, large share repurchases, expanded Acrobat and Student Spaces AI features, and confirmed a CEO transition to Anil Chakravarthy from December 1, 2026.
- New Acrobat and Student Spaces capabilities show Adobe using AI to deepen engagement across documents and education, while buybacks and leadership changes reshape capital allocation and execution priorities.
- We will now look at how Adobe's record Q3 revenue and AI-first ARR above US$650m could influence the investment narrative.
Compare Adobe's AI pivot with a curated set of enterprise software stocks that pair recurring revenue with strong balance sheets in our list of solid balance sheet and fundamentals (22 results)
Adobe Investment Narrative Recap
To own Adobe, you need to believe its AI push across Creative Cloud, Acrobat and Experience Cloud can keep users engaged and paying, even as growth moderates. Record Q3 revenue of US$6.76b and AI first ARR above US$650m support that thesis, but slower net new ARR and cautious Q4 guidance keep execution under the microscope.
The key near term swing factor is whether the freemium and AI feature strategy converts very large user numbers into recurring spend without eroding margins. The biggest operational risk is that rising competition and higher AI investment weigh on pricing and profitability while average billings and subscription trends stay soft.
The most relevant update for that debate is Adobe’s new Q4 2026 and full year outlook. Management now targets Q4 revenue of US$6.80b to US$6.85b and full year revenue of US$26.576b to US$26.626b, with GAAP operating margins of 34% in Q4 and 35% for the year.
Those numbers frame the near term catalyst clearly. You are watching whether AI first ARR momentum and new Acrobat and Student Spaces features show up in subscription additions and cash generation, or whether slower billings growth and flat margins signal that competition, higher AI spend and a pending CEO transition are starting to bite.
Adobe's narrative projects US$32.8b revenue and US$9.6b earnings by 2029. This requires 9.2% yearly revenue growth and an earnings increase of about US$2.4b from US$7.2b today.
Uncover why Adobe's fair value indicates a 10% potential upside to its current price that may not last much longer.
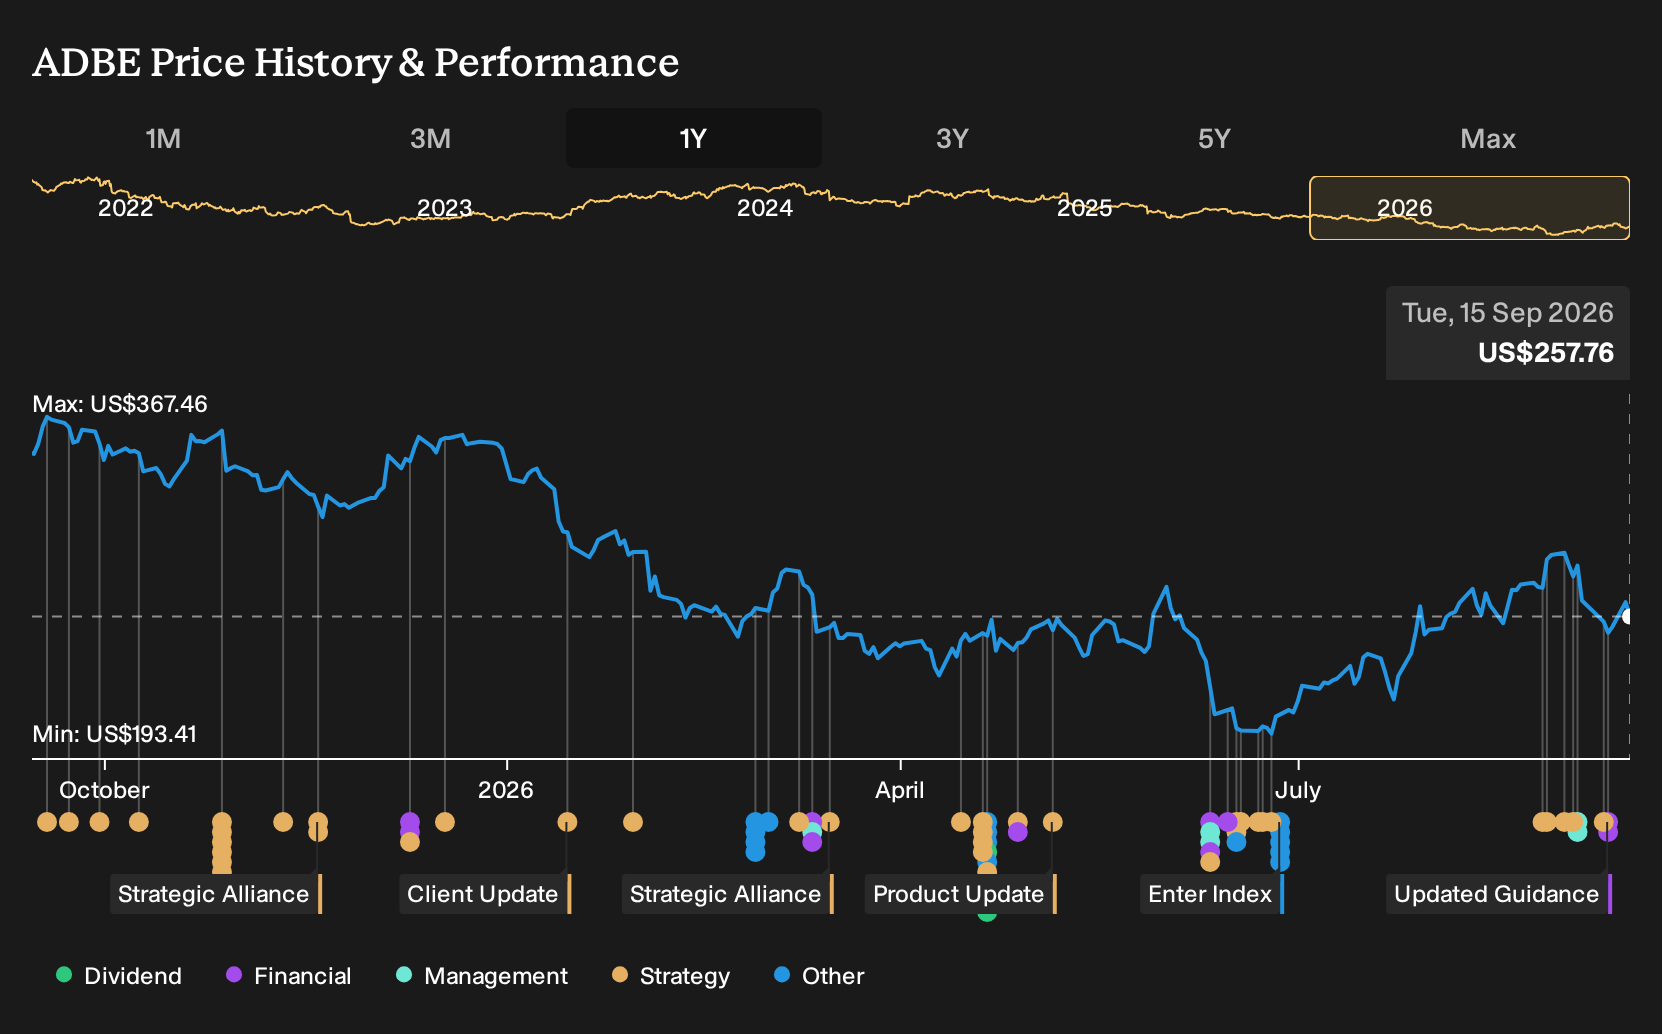
Exploring Other Perspectives
One alternate view focuses less on AI product upside and more on margin pressure. The most bearish Adobe analysts were modelling only 8.5% yearly revenue growth and profit margins edging down to 28.4%, with earnings of about US$9.1b by 2029. That is a cooler story than consensus, and Q3’s AI-first ARR and new guidance could still shift it.
Explore 55 other Adobe fair value estimates, including one that suggests as much as 24% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Adobe research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Adobe. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adobe's overall financial health at a glance.
Looking For More Adobe Investment Ideas Beyond One Stock
If Adobe sits at the center of your watchlist but you want a broader set of options, the Simply Wall St Screener can help you line up other businesses with characteristics that match your style, from resilience to income focus to under the radar opportunities.
- If capital preservation is your priority, start with resilient companies that aim to keep risk contained using our 11 resilient stocks with low risk scores.
- If income matters most, focus on businesses with higher yields and robust payouts through the 6 dividend fortresses.
- If you prefer underfollowed stories with solid fundamentals, scan a curated set of potential future leaders using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com