
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Rollins Stock Could Change Following Weak Quarterly Results
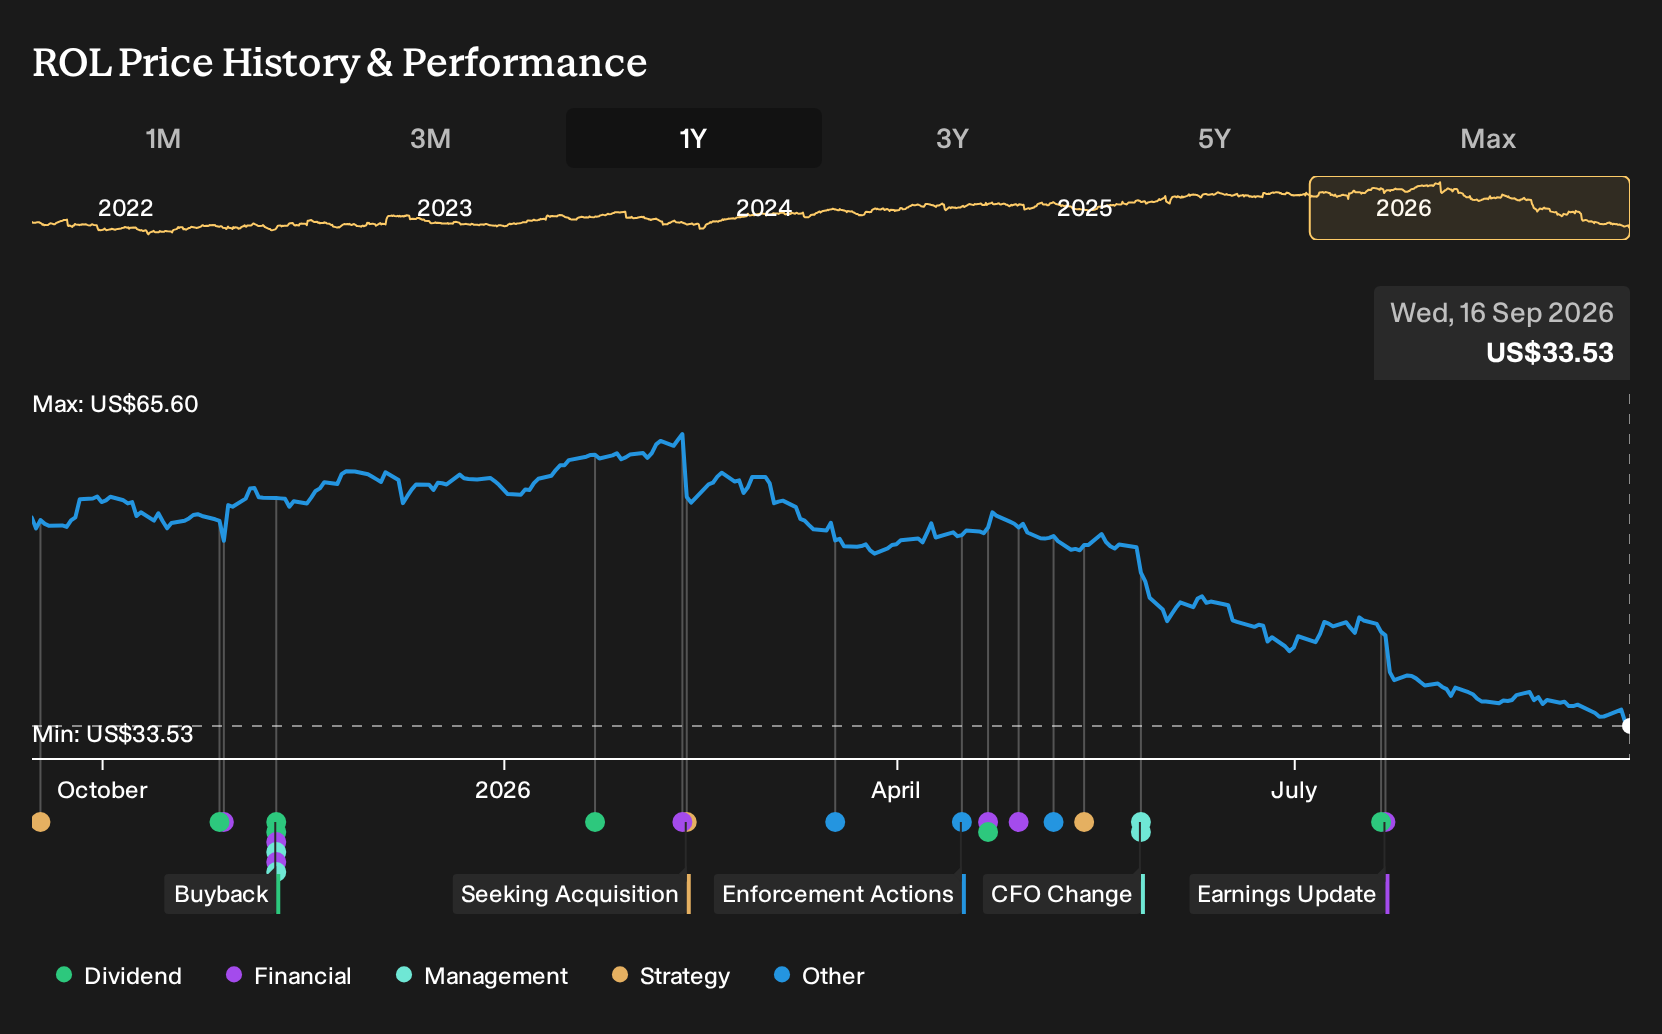
- Rollins recently reported a weaker second quarter, missing Wall Street expectations on adjusted EPS, revenue, and adjusted EBITDA, raising questions about momentum in its pest control operations.
- The shortfall in organic growth points to operational and demand pressures inside Rollins' core business, which matter more for long term value than any short term analyst sentiment.
- We will now explore how Rollins' softer quarterly performance and slower organic growth could reshape the investment narrative around the business.
Rollins Investment Narrative Recap
To own Rollins, you need to believe its pest and termite services can keep attracting recurring customers in both residential and commercial markets, even through softer patches. The latest quarter challenges that view a bit because weaker organic growth hints at some pressure on demand and on the day to day execution model. For the near term, the key swing factor is whether core volumes and service intensity stabilize.
The biggest operational risk right now is that cost inflation in areas like fleet and staffing combines with slower activity and squeezes margins further. Macro weakness, especially for residential customers, could make that worse. On the other side, incremental efficiency work and more disciplined spending could limit the earnings hit if management executes well.
The most relevant recent development tied to this setup is Rollins leaning on acquisitions such as Saela Pest Control alongside its existing multi brand structure. Saela is expected to contribute meaningful revenue in 2025, so integration quality and customer retention from that portfolio become important to watch after a softer quarter.
For you as a shareholder, that means near term catalysts are less about new deals and more about how effectively Rollins folds acquired routes into its network, maintains service levels and protects margins. Any stumble would add to concerns already raised by the miss on adjusted EPS, revenue and adjusted EBITDA, while smooth integration would help support the broader recurring revenue story.
Rollins Forecasts Put Under the Microscope
Rollins' narrative projects US$5.0b revenue and US$732.6m earnings by 2029. That profile aligns with analysts who assume 8.6% yearly revenue growth and an earnings increase of about US$200.9m from US$531.7m today.
Uncover how Rollins' fair value indicates a 36% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate view on Rollins leans heavily on regulatory risk. The most cautious analysts already expected revenue of about US$4.8b and earnings near US$698.1m by 2029, below the consensus path. That cohort presents a more pessimistic outlook, so the latest earnings miss may prompt you to reassess which camp you align with.
Explore 5 other Rollins fair value estimates, including one that suggests as much as 52% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Rollins research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rollins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rollins' overall financial health at a glance.
Looking for more investment ideas beyond Rollins?
Once you have a view on Rollins, it can help to line it up against other potential opportunities using the Simply Wall St Screener so you can see how quality, valuation and risk stack up side by side.
- For investors who want income at the center of their plan, check out a focused group of 6 dividend fortresses that currently offer higher yields and may warrant a closer look.
- If capital preservation and steadier profiles matter most to you, start with a curated set of 11 resilient stocks with low risk scores that score well on resilience and risk controls.
- To broaden your watchlist with potential future leaders, scan a targeted collection of 16 high quality undiscovered gems that combine solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com