
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Asian Growth Companies With High Insider Ownership For September 2026
As geopolitical tensions and rising oil prices continue to shape the economic landscape, Asian markets are navigating through a period of volatility. Amidst these challenges, growth companies with high insider ownership often stand out as they typically indicate strong confidence from those closest to the business.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 116.3% |
| Ningbo Sanxing Medical ElectricLtd (SHSE:601567) | 24.9% | 56.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| HUMAN MADE (TSE:456A) | 23.9% | 28.8% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 31.9% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
Let's uncover some gems from our specialized screener.
Shanjin International Gold (SZSE:000975)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Shanjin International Gold Co., Ltd. engages in the exploration, mining, and trading of precious and non-ferrous metal ores in China, with a market cap of CN¥73.53 billion.
Operations: The company's revenue primarily comes from Metal Commodities Trading, generating CN¥8.99 billion, and Non-Ferrous Metal Mining and Processing, contributing CN¥8.52 billion.
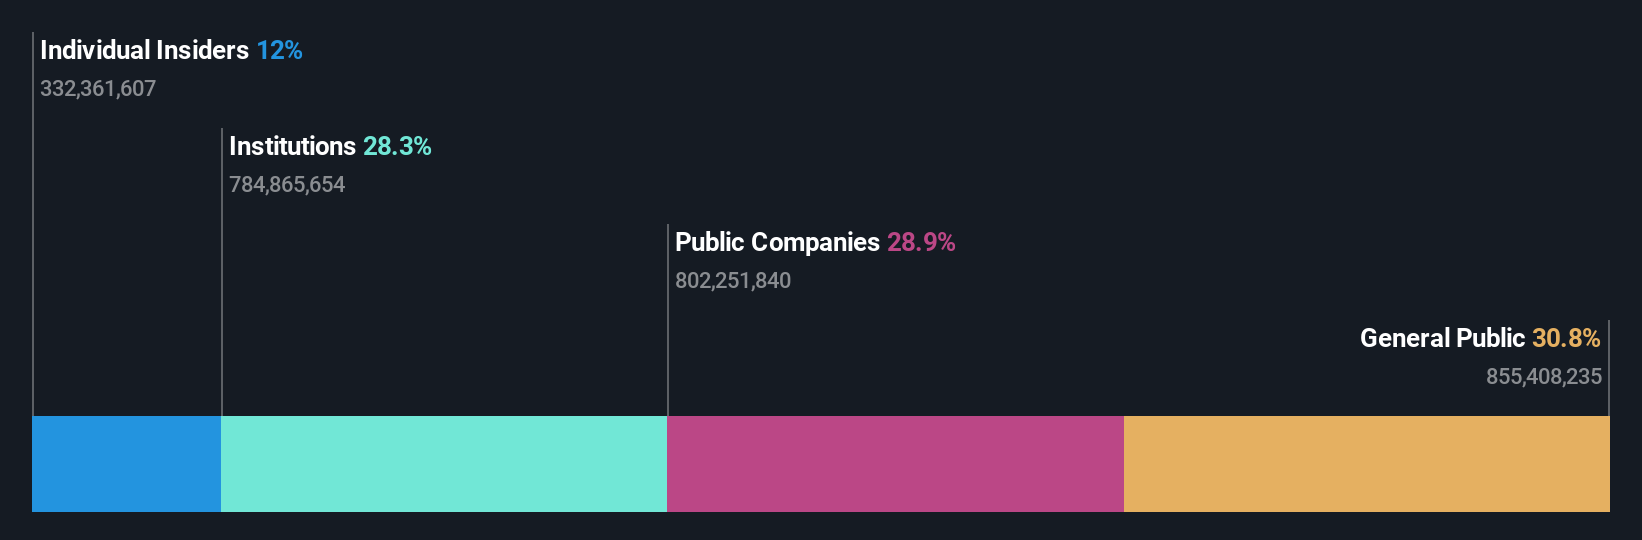
Insider Ownership: 12%
Shanjin International Gold demonstrates strong growth potential, with earnings rising 40.8% over the past year and forecasts indicating a significant annual profit growth of 32%. Despite unstable dividends, the company trades at a substantial discount to its estimated fair value. Recent board changes include Xu Jianxin as a non-independent director. With revenue expected to grow faster than the Chinese market, Shanjin maintains good relative value compared to industry peers.
- Dive into the specifics of Shanjin International Gold here with our thorough growth forecast report.
- The analysis detailed in our Shanjin International Gold valuation report hints at an deflated share price compared to its estimated value.
Hubei DinglongLtd (SZSE:300054)
Simply Wall St Growth Rating: ★★★★★★
Overview: Hubei Dinglong Co., Ltd. focuses on the research, development, production, and service of circuit design, semiconductor materials, and printing and copying consumables with a market cap of CN¥67.20 billion.
Operations: The company generates revenue through its involvement in circuit design, semiconductor materials, and printing and copying general consumables.
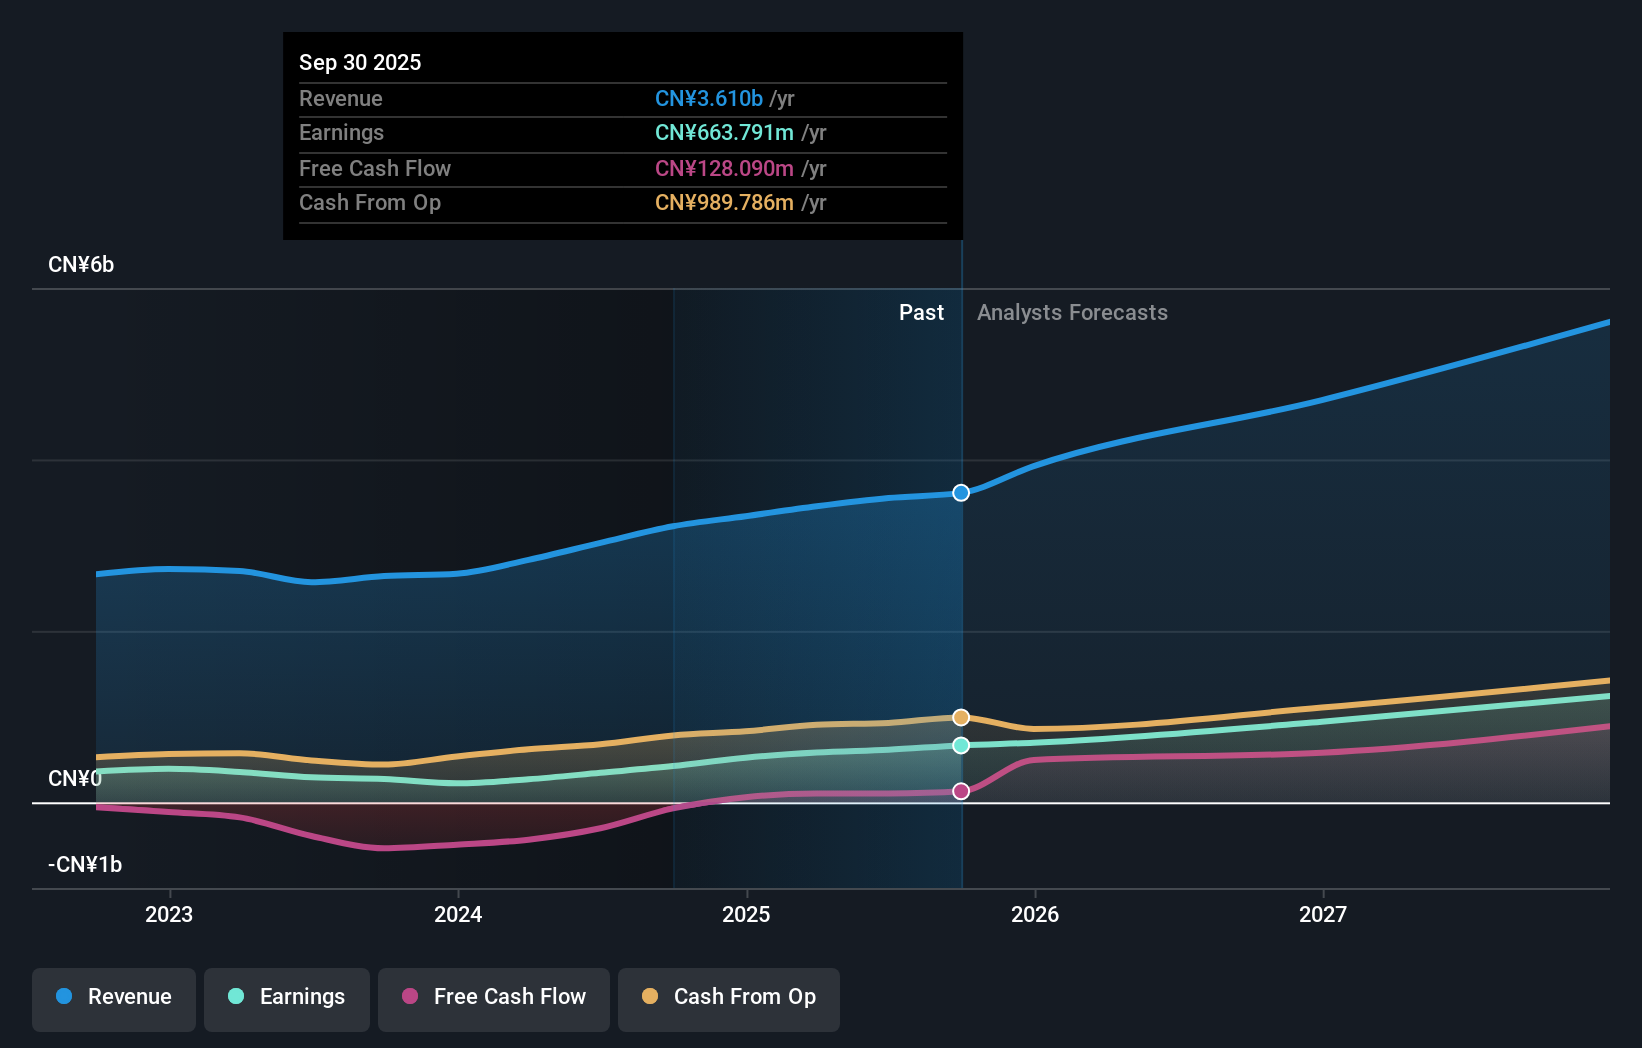
Insider Ownership: 29.3%
Hubei Dinglong Ltd. shows promising growth prospects, with earnings rising 52.9% over the past year and revenue forecasted to grow at 21.9% annually, outpacing the Chinese market average. Recent earnings reported CNY 529.44 million net income for the half-year, reflecting strong performance. The company initiated a share buyback program worth up to CNY 200 million to protect shareholder value amid high insider ownership and anticipated significant annual profit growth of 28.4%.
- Get an in-depth perspective on Hubei DinglongLtd's performance by reading our analyst estimates report here.
- Our valuation report here indicates Hubei DinglongLtd may be overvalued.
Wuhan Jingce Electronics Group (SZSE:300567)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Wuhan Jingce Electronics Group Co., Ltd. specializes in the research, development, production, and sale of semiconductor, display, and new energy testing equipment across China and internationally, with a market cap of CN¥57.70 billion.
Operations: The company's revenue is primarily derived from its Electron Product segment, which generated CN¥3.78 billion.
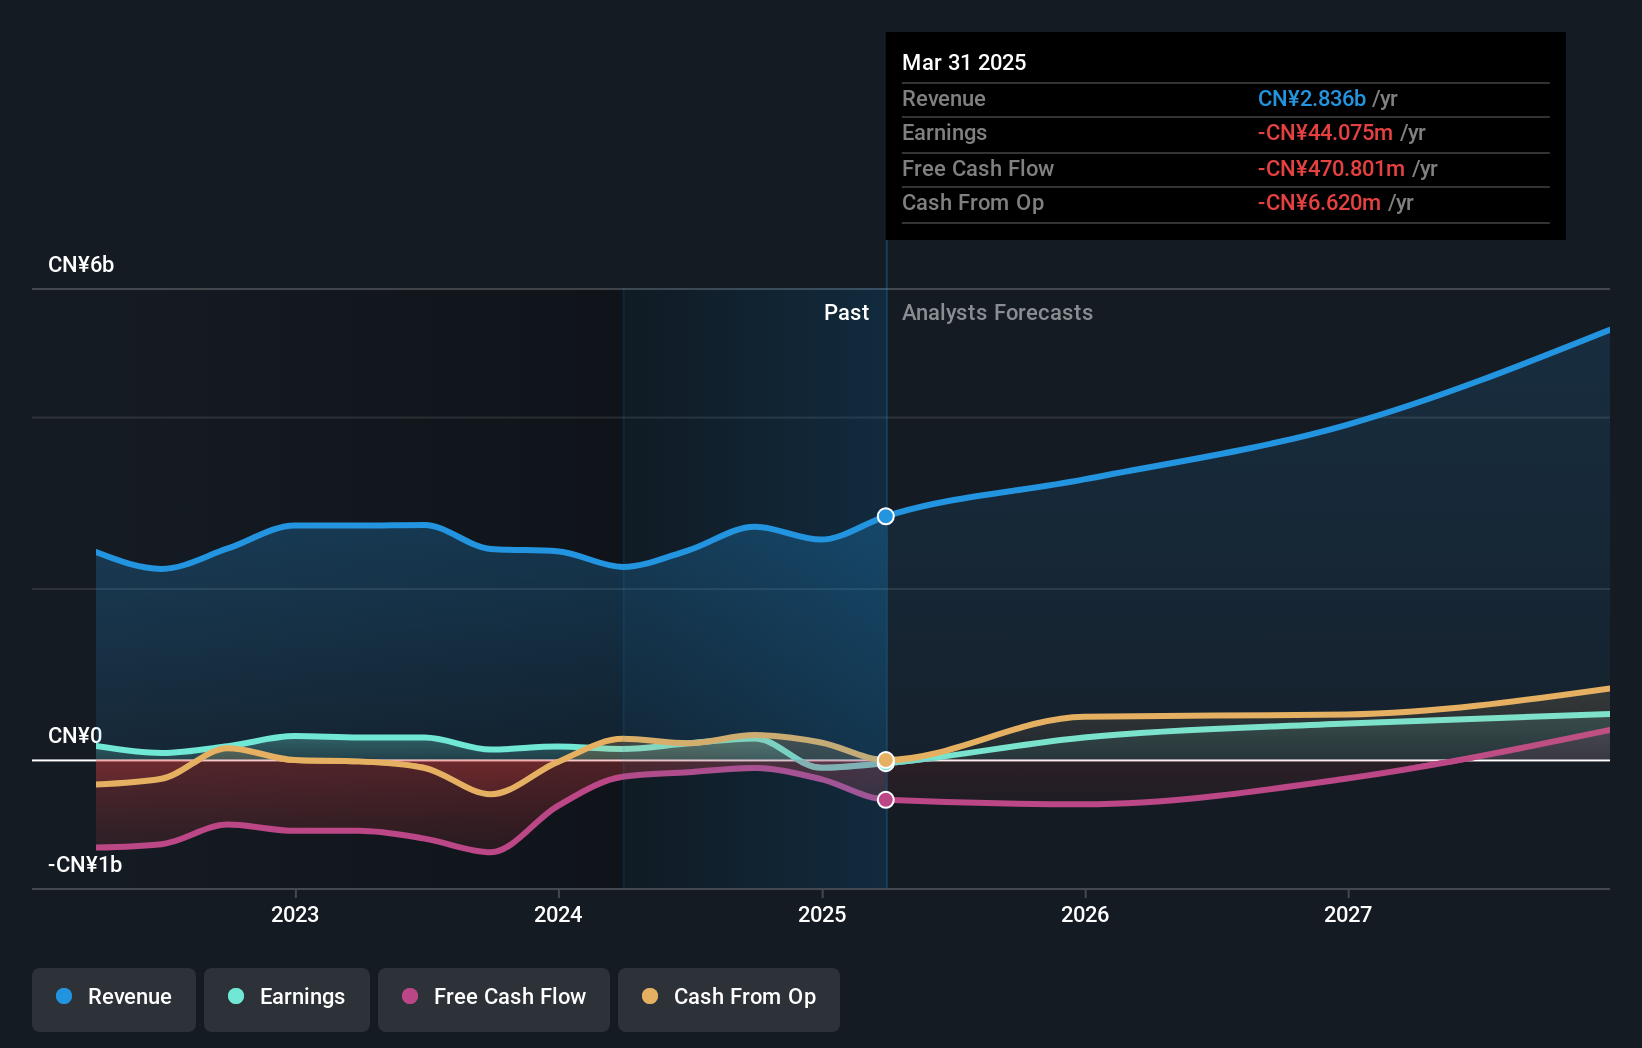
Insider Ownership: 32.1%
Wuhan Jingce Electronics Group anticipates substantial growth, with earnings projected to rise 63.6% annually, significantly outpacing the Chinese market. Revenue is expected to grow 28.9% per year, while recent half-year results showed sales of CNY 1.78 billion and net income of CNY 75.03 million, indicating strong performance compared to last year. However, interest payments are not well covered by earnings and share price volatility persists despite high insider ownership stability.
- Take a closer look at Wuhan Jingce Electronics Group's potential here in our earnings growth report.
- Our expertly prepared valuation report Wuhan Jingce Electronics Group implies its share price may be too high.
Seize The Opportunity
- Dive into all 498 of the Fast Growing Asian Companies With High Insider Ownership we have identified here.
- Interested In Other Possibilities? We've found 7 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com