
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Waters (WAT) Following Product Launches And Partnership Is The Stock Already Fairly Valued
Waters (WAT) is back in focus after two announcements in quick succession: a global launch of the BD FACSDiscover A7 Cell Analyzer and a new Everlywell partnership for at-home HPV screening.
The recent product launch and Everlywell partnership arrive as Waters trades at US$417.09, with a 90-day share price return of 16.83% and a 1-year total shareholder return of 37.62%. This points to momentum that has been building rather than fading.
Explore other lab and diagnostics companies that show similar momentum and product depth using our curated list of list of solid balance sheet and fundamentals (22 results).
After a 37.62% 1-year total return and a move toward analysts’ US$442.71 target, Waters now trades at a 6% to 14% discount. Is that market caution, or is the stock mispriced based on recent execution?
Most Popular Narrative: 5% Undervalued
Waters is trading at $417.09 against a widely followed fair value estimate of $439.70. This frames the recent news flow as a modest undervaluation story built on long-term earnings power rather than short term price swings.
Recurring revenues are accelerating (up 11% this quarter), underpinned by expanding service plan attachments and e-commerce adoption. This enhances revenue stability and net margins, setting up the combined company for more resilient earnings across CapEx cycles.
See why 13 investors see Waters as 5% undervalued.
Result: Fair Value of $439.70 (UNDERVALUED)
Still, the Waters story can change quickly if the BD integration underdelivers on its expected cost and revenue synergies, or if weaker academic and government lab spending persists longer than analysts currently factor in.
Find out about the key risks to this Waters narrative.
Another View: Waters Looks Expensive On Sales
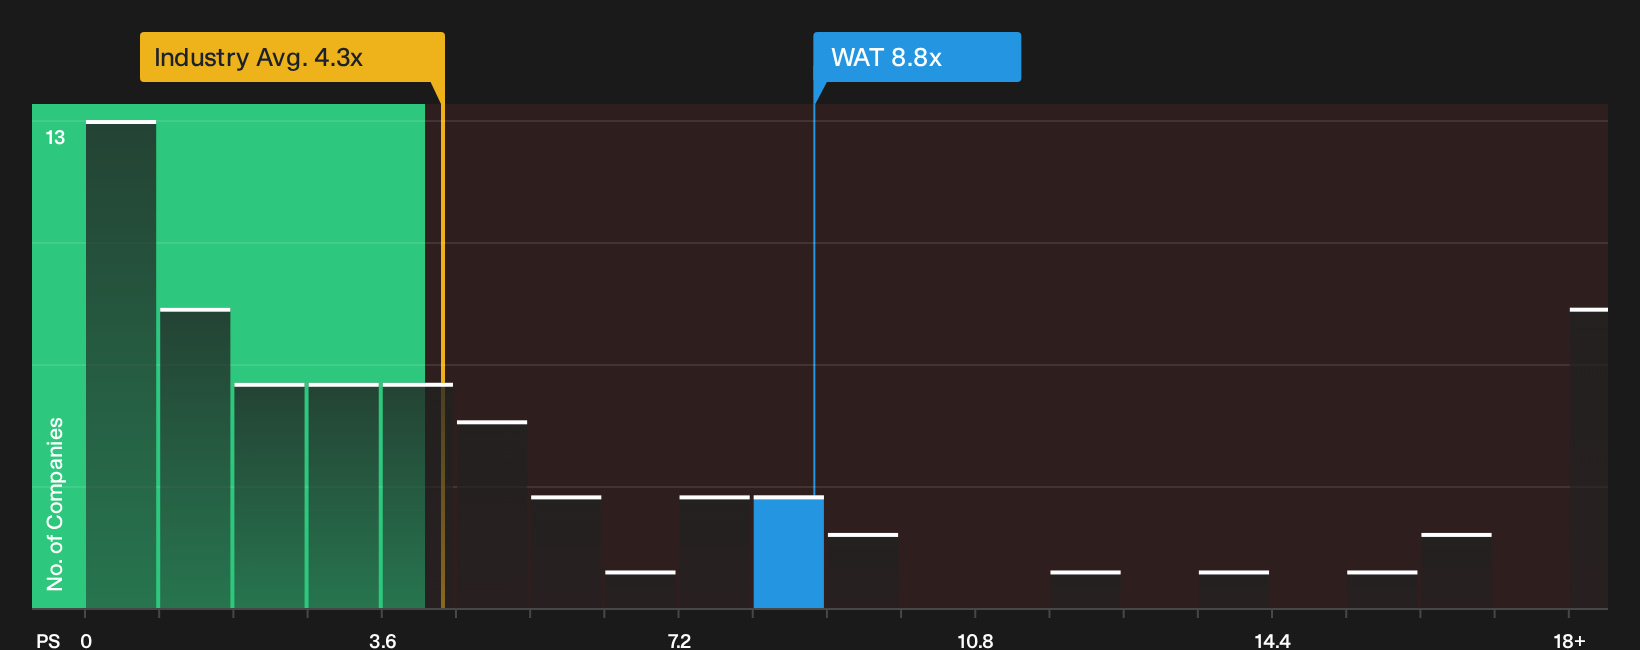
The earlier fair value work points to Waters trading below an estimated cash flow value, yet the price tag tells a different story. On a P/S of 8.8x versus 4.2x for the US Life Sciences group and 5.6x for peers, the stock carries a clear premium.
The fair ratio for Waters sits at 7.4x. That is still below the current 8.8x level, which signals less room for error if margins or growth forecasts fall short. Is this a quality premium that holds, or a valuation that leaves little cushion for disappointment?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Waters and its price tag can create strong opinions quickly. Act promptly, review the full data set, and weigh the 2 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Waters?
Do not stop your research with Waters. Use the Simply Wall St screener to uncover other opportunities that match your goals before the market prices them in.
- Target steadier returns by reviewing companies that score well on resilience and financial risk using our 11 resilient stocks with low risk scores.
- Hunt for quality at a discount by scanning fundamentally strong businesses trading below their estimated value through the 34 high quality undervalued stocks.
- Round out your watchlist with robust balance sheets and solid underlying metrics by tapping into the list of solid balance sheet and fundamentals (22 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com