
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Kemira (HLSE:KEMIRA) Could Change Following Iron Phosphate Pilot Launch
- Kemira Oyj has begun pilot iron phosphate production at its Helsingborg, Sweden site, supplying a key precursor for lithium iron phosphate batteries used in electric vehicles and energy storage.
- The pilot line allows Kemira to move from laboratory work to larger scale customer trials, testing whether its inorganic chemistry expertise can support a new role in Western battery material supply chains.
- We will now examine how Kemira's investment narrative could be influenced by this new iron phosphate pilot for battery materials.
Scan beyond Kemira Oyj and this pilot project to see which battery and electrification suppliers are already on investors' radar with our curated 38 power grid technology and infrastructure stocks
Kemira Oyj Investment Narrative Recap
For Kemira Oyj, you effectively need to believe the traditional water, pulp and packaging chemicals portfolio can keep funding selective bets in newer, regulation driven niches. The iron phosphate pilot fits that pattern. It widens the optionality into battery materials without committing heavy capital yet, so it supports the story but does not transform it on its own.
The near term swing factor still sits in restoring profitability where margins have compressed and end markets look mature, especially in Packaging & Hygiene Solutions and pulp related demand. Execution risk around cost actions, volumes and working capital management remains central. The pilot facility neither removes that risk nor meaningfully adds to it today.
With no other recent announcements listed, the iron phosphate pilot itself is the operational move to focus on. It links directly to Kemira Oyj's existing strengths in inorganic and iron based chemistries and to its track record of taking processes from lab to commercial scale in water and fiber chemicals.
From a catalyst angle, this pilot gives investors a concrete checkpoint for whether Kemira can secure customer qualifications and progress toward any larger scale investment. The risk is that resources and attention shift toward a new vertical while core segments still face margin pressure, currency swings and structurally slower revenue growth than the wider Finnish market.
Kemira Oyj's current analyst narrative points to revenues of €3.0b and earnings of €234.9 million by 2029. This setup assumes 3.4% yearly revenue growth and an earnings increase of about €89.9 million from earnings today of €145.0 million.
Uncover why Kemira Oyj's fair value indicates an 11% potential upside to its current price that could narrow quickly.
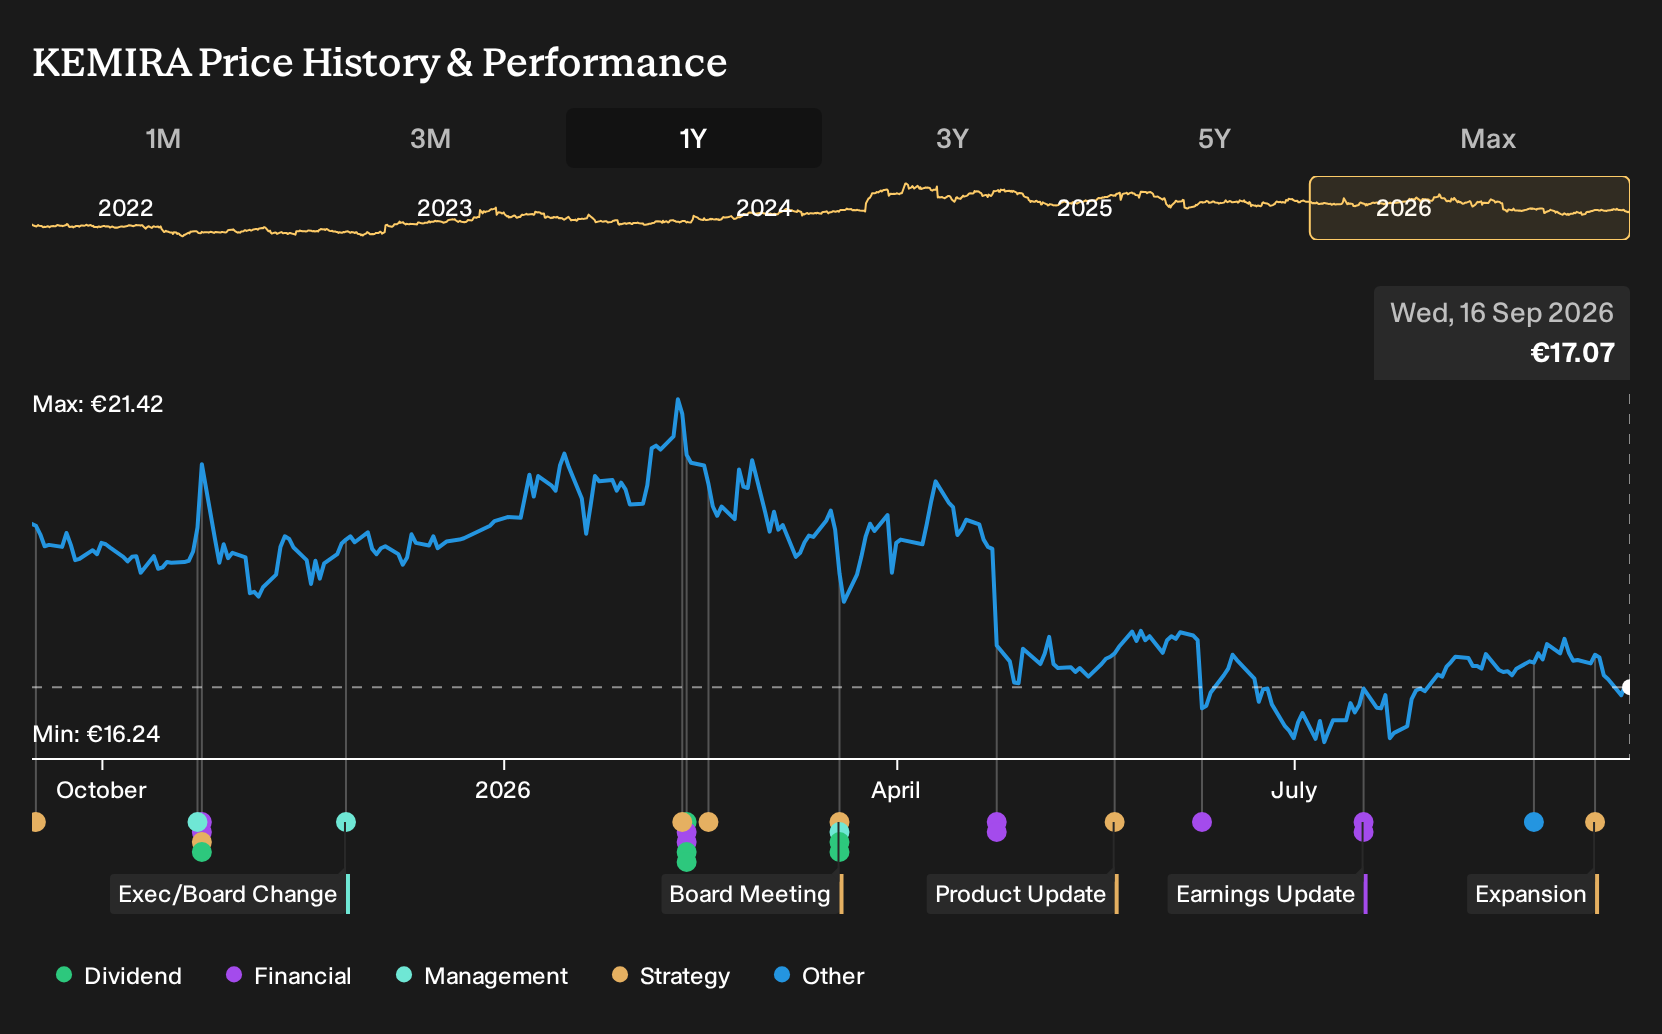
Exploring Other Perspectives
One alternate view pins the key risk on Kemira Oyj’s ongoing growth projects and acquisitions. The most cautious analysts were only baking in about €2.9b of revenue and €234.9 million of earnings by 2029 before this battery materials news. That is a much flatter story. Consider that gap as a way to explore how your own expectations might shift now.
Explore 4 other Kemira Oyj fair value estimates, including one that suggests it could be worth just €18.95.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kemira Oyj research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kemira Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kemira Oyj's overall financial health at a glance.
Looking For More Ideas Beyond Kemira Oyj?
If the Kemira Oyj story has sharpened your thinking, you can use that same framework to scan for other businesses that fit your risk and return preferences across the electrification theme and beyond.
The Simply Wall St Screener can help you quickly filter for opportunities that line up with your investing style through curated shortlists such as:
- For investors who want income upfront with a yield focus, review a curated group of higher yielding companies through our 163 dividend fortresses.
- If capital preservation and steadier profiles matter most to you, start with a pre filtered collection of 103 resilient stocks with low risk scores that score well on our risk checks.
- When you want quality that is not already crowded with attention, scan through a hand picked set of 618 high quality undiscovered gems that pair solid fundamentals with lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com