
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Did PureCycle Technologies (PCT) Stock Drop After Its Latest Update?
PureCycle Technologies (PCT) just moved from pilot work to full commercial production, reporting Q2 2026 results that included 173% revenue growth and the first large-scale output for Procter & Gamble.
The share price of PureCycle Technologies has retreated sharply despite the operational progress, with the stock down 19.7% on a 30 day share price return and the 1 year total shareholder return falling 58.5%. This suggests sentiment has cooled even as commercial milestones accumulate.
Scan beyond PureCycle Technologies to see how other recycling and materials stocks are setting up right now with our hand-picked 16 high quality undiscovered gems
Bulls see PureCycle Technologies as a rare way to play commercial traction in recycled plastics after a sharp selloff, while bears focus on losses and execution risk. Which side lines up better with the current valuation setup?
Most Popular Narrative: 47% Undervalued
PureCycle Technologies closed at $5.58, while the most followed narrative anchors fair value at $10.60. The gap between price and story is wide and very visible for anyone watching the stock.
Growing interest from large consumer brands and quick service restaurant chains in circular packaging solutions for coffee lids, cups and snack packaging is creating a pipeline of high volume applications that management links to 40 million to 50 million pounds of potential annual demand. This directly targets future revenue scale.
See why 3 investors see PureCycle Technologies as 47% undervalued.
Result: Fair Value of $10.60 (UNDERVALUED)
Still, the PureCycle Technologies narrative leans heavily on a few large customers and on new facilities ramping smoothly. As a result, delays or funding setbacks could quickly test that optimism.
Find out about the key risks to this PureCycle Technologies narrative.
Another View: PureCycle Technologies Through a P/B Lens
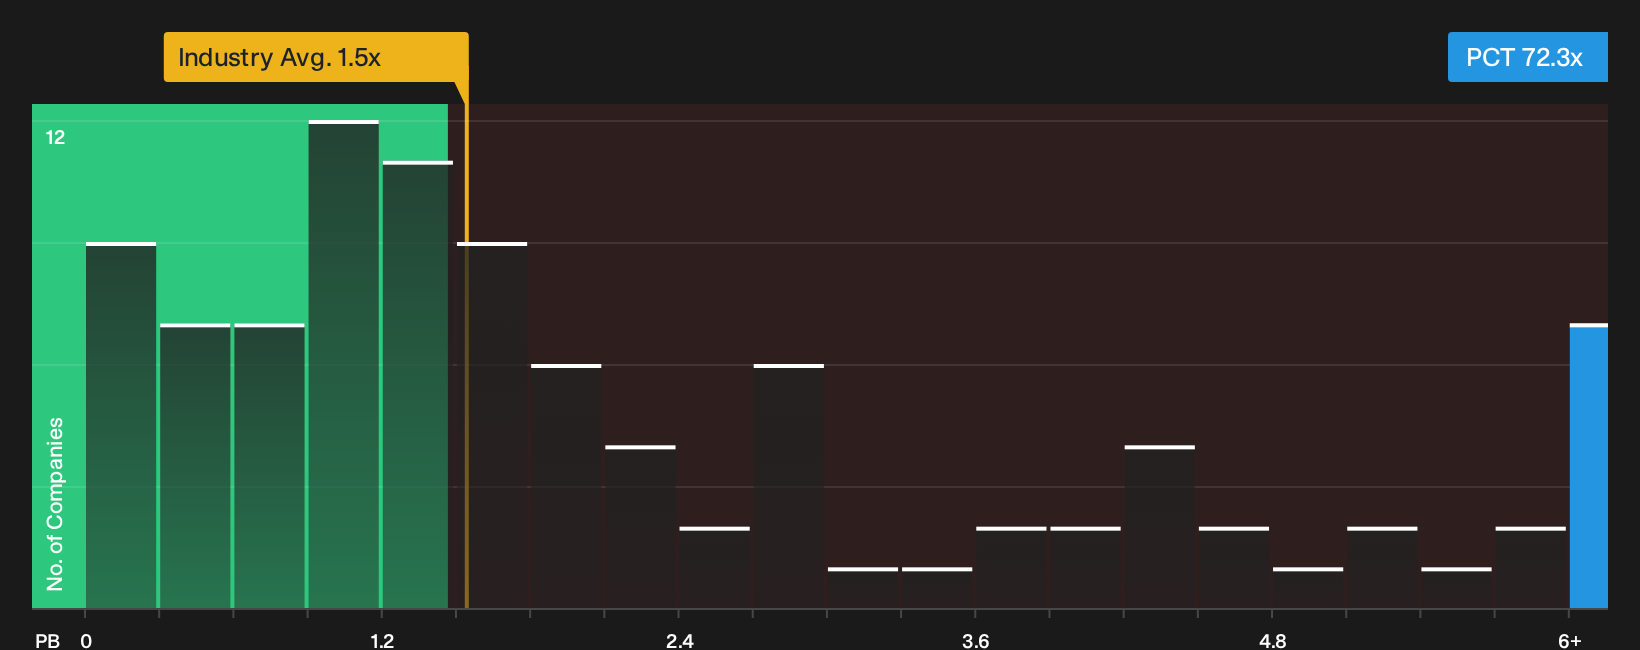
The story around PureCycle Technologies looks very different when you swap the narrative fair value for a plain ratio check. On a P/B basis, the stock trades at 72.3x compared with about 1.5x for both the US Chemicals industry and its peer group, which points to a very rich valuation that leaves little room for execution missteps.
This kind of gap can matter in practice because it suggests investors are paying many times more for each dollar of net assets than the broader sector, even while PureCycle remains loss making and relies on higher risk funding sources. If that premium were to compress toward more typical levels, how confident are you that the growth story would still feel compelling enough at a lower implied price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around PureCycle Technologies is clearly split. This means your edge comes from getting closer to the numbers yourself and deciding quickly how the mix of risk and upside stacks up for your portfolio, starting with the 1 key reward and 2 important warning signs.
Looking for more PureCycle Technologies style investment ideas?
If PureCycle Technologies has you thinking about what else might be mispriced or overlooked, now is the time to widen your search using targeted screeners.
- Spot potential bargains early by scanning companies that combine quality metrics with lower valuations through the 34 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with robust balance sheets and solid fundamentals using the list of solid balance sheet and fundamentals (22 results).
- Hunt for less crowded opportunities by filtering for underfollowed stocks with strong underlying data via the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com