
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Workiva (WK) Cheap After Its Agent Studio Launch?
Workiva (WK) used its Amplify 2026 conference to introduce Agent Studio, a no-code AI agent builder, along with new tools focused on regulatory reporting and automated internal audit testing.
Workiva shares closed at US$74.81, with a 1-day share price return that declined 1.42%. However, the 90-day share price return of 55.76% points to strong recent momentum, following a year-to-date share price return that is down 9.83% and a 5-year total shareholder return that is down 49.51%.
Look beyond Workiva's latest AI initiative and compare it with a curated list of 76 profitable AI stocks that aren't just burning cash.
Bulls see Workiva’s AI push and 13.3% annual revenue growth as a platform turning point, while bears point to a 5 year shareholder return that is down 49.51%. Which story do the current valuation numbers back up?
Most Popular Narrative: 5% Undervalued
With Workiva last closing at $74.81 against a widely followed fair value of $78.73, the current price sits just under that narrative line in the sand, leaving investors weighing whether the recent AI push and guidance are fully reflected.
Workiva's focus on multi-solution platform deals and larger contracts, particularly with Fortune 50 and Fortune 100 companies, is anticipated to drive revenue growth through increased account expansion and higher contract values. There is a strong demand for Workiva's sustainability reporting solutions in light of new regulations like the CSRD in Europe, along with a growing market for science-based target reporting, which is expected to enhance their subscription revenues significantly.
See why 7 investors see Workiva as 5% undervalued.
Result: Fair Value of $78.73 (UNDERVALUED)
Still, the Workiva story can break if European sustainability rules change course, or if partner led deployments disappoint customers and weaken renewal economics.
Find out about the key risks to this Workiva narrative.
Another View: Workiva Through The P/E Lens
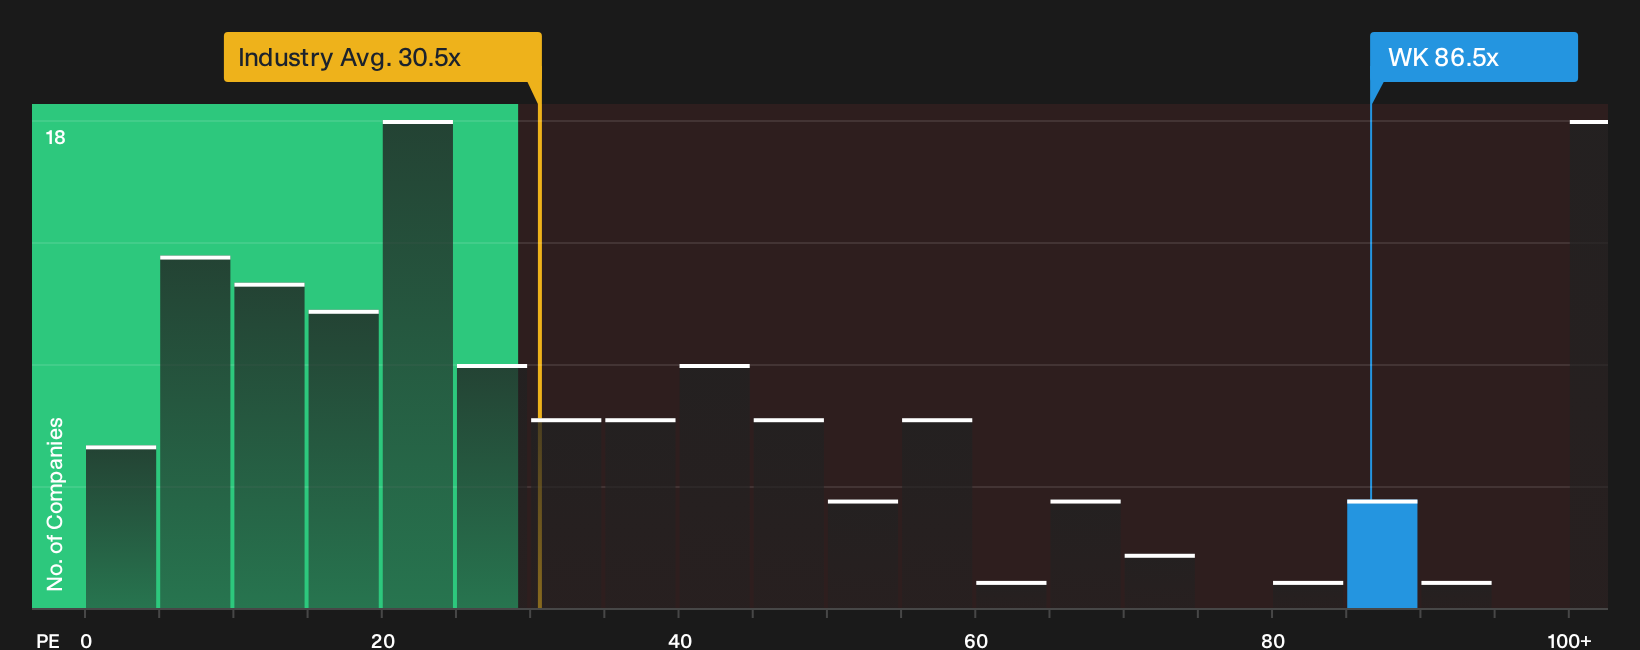
The fair value narrative paints Workiva as 5% undervalued, yet the earnings multiple tells a very different story. The stock trades on a P/E of 86.5x compared with 30.3x for the US Software group, 54.7x across peers, and a fair ratio of 42.5x. That gap suggests investors are paying a rich premium. Is that pricing power or valuation risk?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Workiva is clearly split, so if this story matters to you, move quickly through the underlying data and weigh both sides for yourself with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Workiva?
If Workiva has sharpened your thinking about valuation and risk, you can use that momentum to scan for other opportunities before the market moves on.
- Explore potential upside by reviewing companies that screen as quality and priced below fair value through the 34 high quality undervalued stocks.
- Support portfolio resilience by focusing on businesses with sturdier financial footing in the list of solid balance sheet and fundamentals (22 results).
- Identify underfollowed opportunities by reviewing a curated pool of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com